📋 Quick Summary
In this article:
Quick Answer: What Does Business Interruption Insurance Do?
What Is Business Interruption Insurance?
Why Business Interruption Cover Matters
1. What Costs Can Business Interruption Insurance Cover?
2. What Events Can Trigger Coverage?
3. What Business Interruption Insurance Usually Does Not Cover
4. Understand the Waiting Period and Indemnity Period
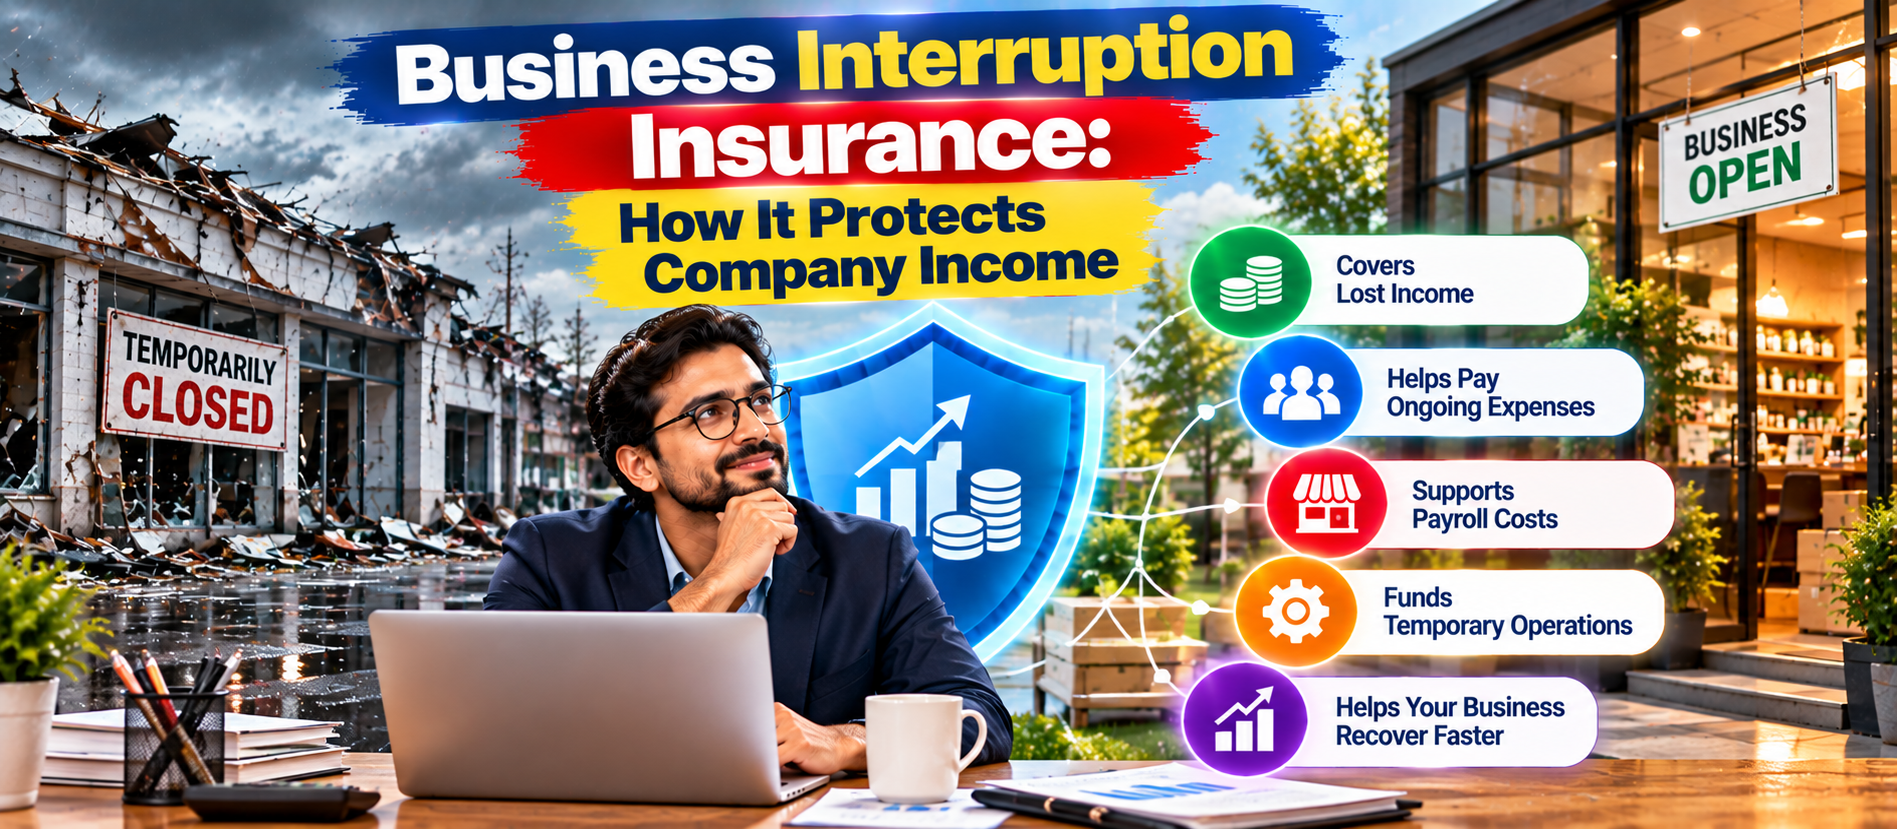
Business interruption insurance can help a company manage lost income when a covered event forces it to pause or reduce operations. It may also help pay certain ongoing expenses during the recovery period. The exact protection depends on the policy wording, the cause of the disruption, and the limits selected.
A temporary closure can affect more than sales. Rent, loan payments, payroll, supplier costs, and other bills may continue even when customers cannot be served. Business interruption cover is designed to help eligible businesses handle some of that financial pressure after a covered loss.
Quick Answer: What Does Business Interruption Insurance Do?
Business interruption insurance may replace lost business income and cover certain continuing operating expenses when a covered event disrupts normal operations. In many policies, the interruption must result from covered physical damage to insured property, such as damage caused by a fire or certain storms. Some policies may offer extensions for specific events, subject to their terms.
It usually does not cover every reason a business loses sales. A general drop in demand, a voluntary closure, or a disruption that does not meet the policy trigger may not qualify. Check the insured causes of loss, waiting period, indemnity period, limits, exclusions, and documentation requirements before buying.
What Is Business Interruption Insurance?
Business interruption insurance is coverage that may help a business recover financially after an insured event interrupts its operations. It is often included in a commercial property policy or a business-owner package. It may also be called business income insurance or loss-of-profits cover in some markets.
The goal is to help the business return to the financial position it might reasonably have reached if the covered interruption had not happened, subject to the policy’s calculation method and limits. It is not designed to guarantee profits or pay for every business problem.
For example, a fire may damage a shop and force it to close while repairs take place. The business may lose sales but still need to pay rent, certain staff costs, utilities, and loan payments. If the event and resulting interruption are covered, the policy may help pay eligible lost income and continuing expenses.
Coverage terms differ by insurer and country. Some policies require physical damage to insured property. Others may include limited extensions for specified events, such as certain service interruptions or restrictions imposed by authorities. Never assume an extension exists unless it appears in the contract.
Why Business Interruption Cover Matters
Many businesses rely on steady cash flow to meet regular commitments. A short closure can create a cash shortage, especially for a company with high fixed costs or limited savings.
Business interruption cover may help with several pressures:
- Lost income: It may compensate for eligible income lost during a covered interruption.
- Continuing expenses: It may help pay covered costs that continue while operations are disrupted.
- Recovery time: It can give the business financial support while repairs or replacement work takes place.
- Employee retention: Depending on the policy, it may help cover certain payroll costs so key workers can remain with the business.
- Cash-flow stability: It may reduce some financial strain during recovery, although claim payments are subject to terms and timing.
Insurance is only one part of a continuity plan. Emergency savings, backup suppliers, data backups, alternate work locations, and clear response procedures can also help a business recover.
1. What Costs Can Business Interruption Insurance Cover?
The policy schedule and wording determine which costs qualify. Common coverage elements may include the following.
Lost business income
A policy may cover the reduction in income caused by a covered interruption. The insurer may compare actual results during the interruption with an estimate of the income the business would likely have earned without the event. The calculation can consider historical records, trends, seasonal changes, and other relevant factors.
The policy may define income differently from accounting profit. Read the definition carefully and ask how the insurer calculates the loss. The payment may be reduced by expenses that the business did not incur during the closure.
Continuing operating expenses
Some expenses may continue even when the business cannot operate normally. Examples can include rent, certain loan payments, insurance premiums, essential service charges, and other eligible fixed costs. Coverage depends on the policy and the expense involved.
Payroll and employee costs
Some policies include all or part of eligible payroll, while others allow a business to select payroll coverage or set a limit. Keeping key employees may help a business resume operations more quickly, but payroll treatment varies. Confirm which staff costs are included and for how long.
Extra expense
Extra expense cover may help pay reasonable additional costs needed to avoid or reduce a shutdown. Examples might include renting temporary premises, using alternative equipment, or paying for expedited delivery of replacement machinery. The expense must meet the policy’s requirements and may need insurer approval.
Temporary relocation
If a covered event makes the usual premises unusable, a policy may help with eligible costs of operating from a temporary location. Check whether rent, moving costs, setup costs, and temporary equipment are included or limited.
2. What Events Can Trigger Coverage?
Business interruption cover is not a stand-alone promise to pay whenever sales fall. The event must meet the policy’s trigger. Many standard policies require direct physical loss or damage to insured property caused by an insured peril.
Depending on the policy, covered property damage might result from:
- Fire or smoke damage.
- Certain storms or wind events.
- Some forms of water damage, subject to exclusions.
- Vandalism or other insured physical damage.
- Other causes specifically listed or not excluded under the selected policy form.
Coverage for floods, earthquakes, equipment breakdown, utility interruption, or damage at a supplier’s premises may require separate cover or a specific extension. Terms differ. Check whether the relevant property and cause of loss are insured.
Some policies offer extensions for interruption caused by restricted access, damage to nearby property, or certain public utility failures. These extensions can have narrow definitions, sub-limits, waiting periods, and conditions. Do not rely on them without reading the exact wording.
3. What Business Interruption Insurance Usually Does Not Cover
Exclusions are critical. A policy may not respond to a loss unless the event and the resulting interruption meet its terms.
- Ordinary loss of demand: A decline in sales due to competition, changing tastes, or weaker demand may not be covered.
- Voluntary closure: Closing for convenience or routine maintenance may not trigger cover.
- Uninsured physical damage: If the underlying damage is excluded or the affected property is not insured, interruption cover may not apply.
- Flood or earthquake: These risks may be excluded unless added or covered by a separate policy.
- Cyber incidents: Standard property-based cover may not pay for a cyberattack or digital outage unless a relevant extension or cyber policy applies.
- Supplier disruption: A supplier’s closure may not be covered unless the policy includes suitable contingent business interruption protection.
- Known events or prior damage: Losses linked to circumstances that existed before cover began may be excluded.
- Fines and penalties: These are often excluded or treated under separate terms.
This is a general guide, not a complete list. Exclusions vary by country, insurer, policy form, and optional endorsements. Ask the insurer to explain any risk that could cause a major interruption for your business.
4. Understand the Waiting Period and Indemnity Period
Two policy terms can strongly affect a claim: the waiting period and the indemnity period.
Waiting period
A waiting period is the time that must pass after a covered event before certain interruption benefits begin. It may be measured in hours or another period stated in the contract. A longer waiting period can leave the business responsible for more of the early costs.
Ask when the waiting period starts, whether it applies to all benefits, and whether separate waiting periods apply to different extensions.
Indemnity period
The indemnity period is the maximum time for which eligible loss may be considered after the covered event, subject to the wording. The period should reflect how long it could take to repair the premises, replace equipment, restore supply chains, regain customer demand, and return to normal trading.
Do not estimate recovery time based only on the fastest possible repair. Construction delays, permits, specialist equipment, seasonal demand, and supplier lead times can extend recovery. Ask an insurance professional to help assess a suitable period.
5. How Insurers Calculate a Business Interruption Claim
Claim calculations can be complex. The insurer will usually need evidence of the business’s financial performance and the effect of the interruption. The policy defines the calculation method and which costs can be included.
Records that may help include:
- Profit and loss statements and balance sheets.
- Sales reports, invoices, and transaction records.
- Tax returns and accounting records.
- Payroll records and staff schedules.
- Supplier invoices and purchase orders.
- Repair estimates, invoices, and timelines.
- Evidence of extra expenses and steps taken to reduce the loss.
- Records showing seasonal trends or planned changes in the business.
The insurer may compare actual results with a reasonable estimate of expected performance. It may adjust the calculation for saved expenses, trends, seasonality, or other policy-defined factors. A business should not assume that every lost sale or expense will be paid in full.
Keep records in secure digital storage and back them up. Good documentation can make it easier to explain the financial effect of an interruption.
6. Business Interruption vs. Commercial Property Insurance
Commercial property insurance and business interruption insurance often work together, but they serve different purposes.
| CoverageMain purposeExample | ||
| Commercial property | May pay for covered physical damage to insured buildings, equipment, stock, or contents. | Repairing a shop after covered fire damage. |
| Business interruption | May help with eligible lost income and continuing costs during a covered interruption. | Managing lost sales and certain ongoing expenses while the shop is repaired. |
| Extra expense | May help pay eligible additional costs to reduce or avoid a shutdown. | Renting temporary equipment to resume work sooner. |
Some package policies combine these protections. However, business interruption cover may depend on the underlying property loss being insured. Review the trigger and any separate limits. Buying property insurance alone does not guarantee that lost income is covered.
7. Who Should Consider Business Interruption Insurance?
This coverage may be worth considering for businesses that rely on a physical location, specialist equipment, stock, or steady customer access. It may also matter when a short shutdown would leave the company unable to meet fixed expenses.
- Retail stores: A covered fire or property loss may stop in-person sales.
- Restaurants and cafes: Damage to a kitchen or dining area may prevent service during repairs.
- Manufacturers: Damage to essential machinery may stop production and delay orders.
- Professional offices: A covered event may make the premises or essential equipment unusable.
- Clinics and service providers: A closure can affect appointments and continuing operating costs.
- Online businesses: Property damage to stock or a warehouse may interrupt fulfillment; cyber-related losses may need separate review.
- Wholesalers and distributors: Damage to inventory or storage facilities may delay deliveries.
A home-based business should not assume that a personal home policy covers business income or equipment. Ask whether the business activity needs separate commercial cover. Businesses with few fixed costs or strong alternative operations may have different needs, but should still assess their exposure.
8. How to Estimate the Right Amount of Coverage
The right limit depends on the income at risk, continuing expenses, expected recovery time, and the policy’s calculation method. Start with current financial records and realistic scenarios.
- Review recent performance. Use monthly sales, costs, and profit reports, including seasonal changes.
- List continuing expenses. Identify costs that would continue during a shutdown and determine which may qualify under the policy.
- Estimate recovery time. Consider repairs, permits, replacement equipment, supplier delays, and the time needed to restore sales.
- Assess extra expenses. Estimate the cost of temporary premises, alternate equipment, or expedited shipping.
- Check policy limits and definitions. Confirm how income is defined and whether payroll or extra expense has separate limits.
- Review the estimate annually. Update it as revenue, costs, premises, equipment, or business plans change.
Do not rely only on last year’s revenue. Growth, inflation, new contracts, and seasonal peaks can change the amount of protection needed. A broker or accountant may help you model possible losses, while the insurer can explain how its policy calculates claims.
9. Practical Ways to Reduce Interruption Risk
Insurance can help after a covered loss, but preventing disruption is also important. A business continuity plan can reduce downtime and support a faster recovery.
- Maintain fire detection, suppression systems, and electrical equipment.
- Back up essential data and test recovery procedures.
- Identify alternate suppliers for critical materials.
- Keep emergency contacts and response steps up to date.
- Store important records securely away from the main premises.
- Consider backup power or alternate work arrangements where suitable.
- Review equipment maintenance and replacement plans.
- Train employees on safety, evacuation, and incident reporting.
- Test how the business would handle a temporary closure.
Some measures may also help when discussing risk with an insurer, but a discount or lower premium is not guaranteed. Ask what evidence the insurer needs and whether any safety conditions are written into the policy.
10. How to Compare Business Interruption Insurance Policies
Policy summaries can look similar while the details differ. Compare the full terms, not just the premium.
- Trigger: What event must happen for the cover to apply?
- Covered locations: Are all relevant premises and operations included?
- Income definition: How does the policy calculate eligible lost income?
- Continuing expenses: Which costs can be included?
- Waiting period: When do benefits start?
- Indemnity period: How long can benefits continue?
- Limits and sub-limits: Are they sufficient for a realistic disruption?
- Extra expense: Can the policy pay costs that reduce downtime?
- Extensions: Are utility failures, supplier interruptions, restricted access, or cyber events included?
- Exclusions and conditions: What could prevent a claim from being paid?
- Claim evidence: Which records must the business maintain?
Request quotes using the same business details and desired limits. Ask the insurer or licensed adviser to explain any important differences in writing.
11. Common Mistakes to Avoid
- Assuming every closure is covered: The cause must meet the policy trigger.
- Choosing an indemnity period that is too short: Recovery may take longer than expected.
- Underestimating income or expenses: Limits based on outdated figures may not be enough.
- Ignoring exclusions: Flood, cyber, utility, or supplier disruptions may need separate cover.
- Failing to keep records: Poor financial documentation can make a claim harder to support.
- Forgetting extra expenses: Temporary premises or expedited equipment may create significant costs.
- Not updating the policy: New locations, equipment, revenue, or operations can change the exposure.
- Relying only on the sales summary: The full wording defines the actual protection.
12. What to Do After a Business Interruption Event
If an event disrupts your business, focus first on safety and preventing further damage. Contact emergency services where needed. Follow reasonable instructions from authorities and take steps that are safe and appropriate to protect people and property.
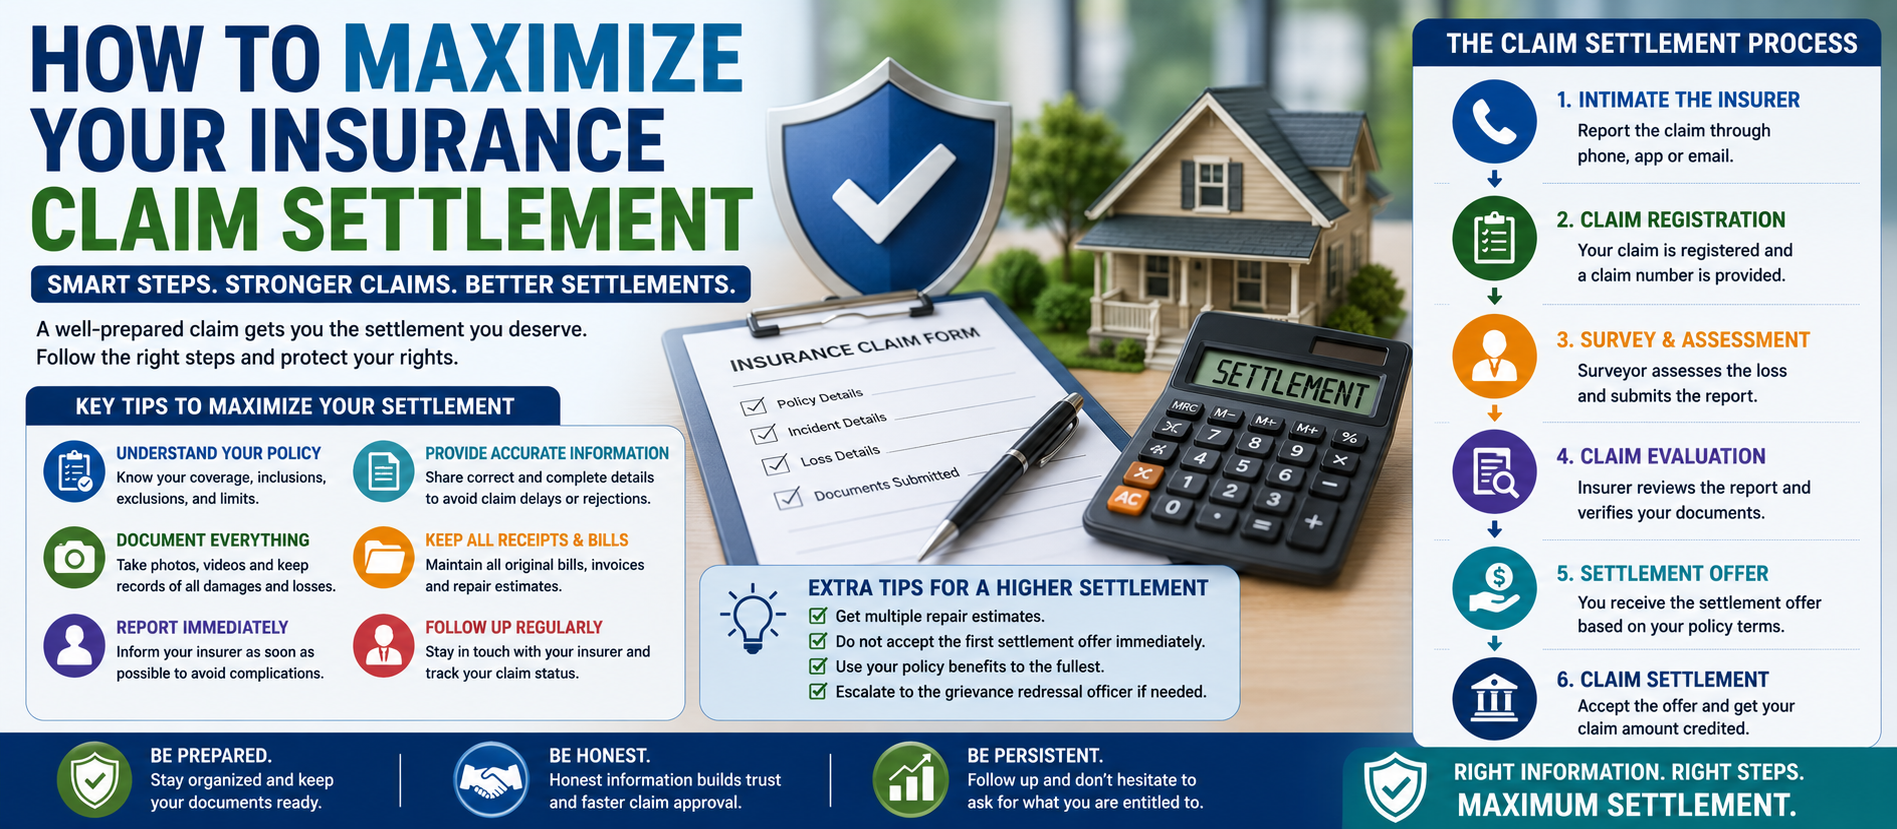
Then contact your insurer or broker promptly and ask how to report the claim. Keep a record of the event, damaged property, closure dates, repairs, lost sales, and extra expenses. Take photos where safe and preserve invoices, financial reports, and supplier communications.
Before making major commitments or disposing of damaged property, ask the insurer about inspection and documentation requirements when practical. Keep copies of all messages and claim references. Follow the policy’s deadlines and cooperate with reasonable requests for information.
Do not assume that all emergency spending will be reimbursed. Ask which temporary measures may be covered and whether approval is required. In urgent circumstances, protect people and follow official safety instructions first.
Frequently Asked Questions About Business Interruption Insurance
What does business interruption insurance cover?
It may cover eligible lost income and certain continuing expenses after a covered event interrupts operations. Many policies require covered physical damage to insured property, while extensions may provide limited protection for specified events. The policy wording controls.
Does business interruption insurance cover lost sales for any reason?
No. A general decline in demand, voluntary closure, or event that does not meet the policy trigger may not be covered. Check the insured causes of loss and exclusions.
Does it cover payroll during a closure?
Some policies include all or part of eligible payroll, while others apply specific limits or options. Confirm which employee costs are included and for how long.
Is business interruption insurance included in property insurance?
It may be included in a commercial property package or business-owner policy, but not every policy includes it. Check the declarations and full wording to confirm.
Does it cover a cyberattack?
Not necessarily. Standard property-based business interruption cover may not respond to a cyber incident. A cyber policy or specific extension may be needed, subject to its terms.
What is the indemnity period?
It is the period during which eligible interruption losses may be considered after a covered event, subject to the policy. Choose a period that reflects realistic repair and recovery times.
Can a small business buy this coverage?
Many insurers offer business interruption cover to eligible small businesses, often alongside commercial property insurance. Availability and terms vary by business type, location, and insurer.
How is a business interruption claim calculated?
The insurer follows the policy’s calculation method and may review financial records, expected income, actual results, saved expenses, and extra costs. Keep accurate records and ask the insurer what evidence is required.
Does it cover a supplier shutting down?
Only if the policy includes applicable contingent business interruption cover or another relevant extension and the event meets its terms. Do not assume supplier failures are automatically covered.
How often should I review my policy?
Review it at renewal and whenever your business changes. Revenue, operating costs, premises, equipment, suppliers, and recovery needs can change over time.
Final Thoughts: Protect Income and Plan for Recovery
Business interruption insurance can help a company manage lost income and certain continuing costs after a covered disruption. It can support recovery, but it does not cover every closure or guarantee that all lost revenue will be replaced.
Before buying, understand the policy trigger, waiting period, indemnity period, income calculation, limits, extensions, and exclusions. Estimate realistic recovery costs and keep reliable financial records. Compare policies with the same assumptions and review cover as the business grows.
Combine insurance with a practical continuity plan, strong safety practices, data backups, and alternate suppliers. Preparation can reduce disruption and make it easier to recover after an unexpected event.
Explore more practical business guides at Digiifrog — www.digiifrog.com.
Disclaimer: This article is for general educational purposes only and is not insurance, legal, or financial advice. Coverage terms and availability vary by insurer and location. Read the full policy wording and consult a licensed insurance professional or relevant local regulator for advice about your business.
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.

Comments (0)
Log in to leave a comment.