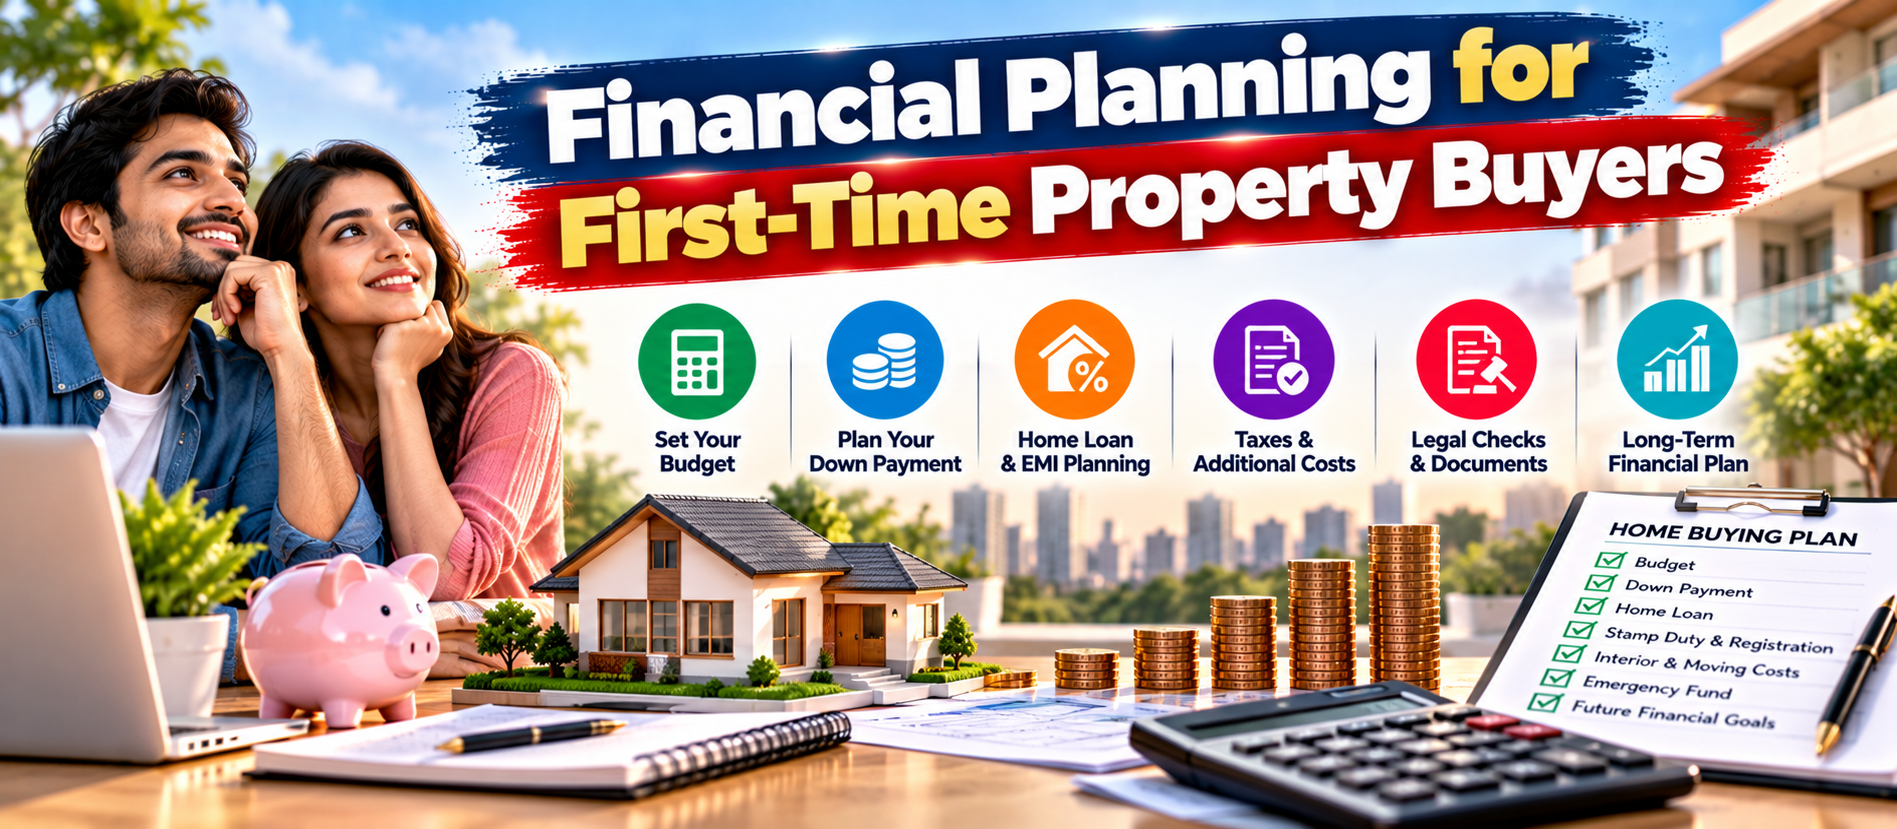
📋 Quick Summary
In this article:
Quick Answer: How Should First-Time Buyers Plan Financially?
Step 1: Define Why You Want to Buy a Property
Step 2: Calculate a Realistic Home-Buying Budget
Start with take-home income
Step 3: Build the Down Payment and Keep an Emergency Fund
Step 4: Understand the Full Cost of Buying a Home
Step 5: Compare Home Loans Beyond the Advertised Interest Rate
Fixed, floating, and reset terms
Buying your first home is a major financial decision. It can bring stability and a sense of ownership, but it also creates long-term responsibilities. The purchase price is only one part of the cost. You must also plan for the down payment, loan repayments, stamp duty, registration, repairs, moving, maintenance, and unexpected expenses.
⚠ Watch Out
Good financial planning helps you buy a property that fits your life instead of stretching your finances to the limit. It also helps you compare home loans, protect your emergency savings, and avoid rushing into a decision because of pressure from a seller or developer.
This guide focuses on first-time buyers in India. It explains how to set a realistic budget, prepare for a home loan, estimate hidden costs, check a property, and build a plan that remains manageable after you receive the keys.
Quick Answer: How Should First-Time Buyers Plan Financially?
Start by calculating what you can comfortably afford, not the maximum amount a lender may offer. Save for the down payment and purchase costs while keeping an emergency fund separate. Compare home loans by interest rate, total cost, fees, and repayment flexibility. Check the property's legal documents and construction status before paying a large amount.
After purchase, make sure the EMI leaves enough room for food, transport, healthcare, insurance, savings, family responsibilities, and repairs. A home should support your financial life, not consume every rupee of it.
Step 1: Define Why You Want to Buy a Property
Before browsing listings, clarify the purpose of the purchase. Are you buying a home to live in, a property for your family, or an investment? Your purpose affects the location, size, budget, and time horizon.
- For self-use: Focus on commute, schools, healthcare, safety, daily services, maintenance, and the suitability of the home for your household.
- For a future family need: Consider whether the property can meet likely needs over the next several years without forcing you to move too soon.
- For investment: Compare rental demand, vacancy risk, maintenance, taxes, liquidity, and the total return after costs. Do not assume property prices will always rise.
Buying a home also reduces flexibility. Selling can take time and involve brokerage, taxes, legal work, and market uncertainty. If your job or family situation may change soon, renting for a while may be a reasonable choice. Compare the financial and personal trade-offs rather than treating ownership as a compulsory milestone.
Step 2: Calculate a Realistic Home-Buying Budget
Set a budget before you choose a property. The advertised price may not include all the money you will need to complete the purchase and make the home ready to live in.
Start with take-home income
Use the income that reliably reaches your bank account after tax and regular deductions. If you earn commissions, bonuses, or business income, be conservative. Do not base a long-term EMI on a bonus that may not arrive every year.
List your monthly commitments
Write down household expenses, existing loan EMIs, school fees, insurance premiums, family support, transport, groceries, subscriptions, and savings goals. Include irregular expenses such as annual insurance renewals, festivals, travel, and medical costs. A budget that ignores these items can make a loan appear more affordable than it is.
Estimate a safe EMI
There is no single EMI-to-income ratio that suits every household. A household with dependants, variable income, or existing debt may need a lower EMI than a household with stable income and few commitments. Test the proposed payment against a realistic monthly budget and leave room for savings.
Ask yourself: Could I pay this EMI if one income stopped for a few months? Could I still handle a medical bill or urgent repair? Would I need to stop all long-term saving? If the answer reveals serious pressure, reduce the property budget or build more savings before buying.
Step 3: Build the Down Payment and Keep an Emergency Fund
A down payment is the portion of the property price you pay from your own funds. The lender finances the remaining eligible amount, subject to its rules and the property's valuation. The required contribution varies with the loan amount, lender policy, property type, and applicable regulations.
Do not assume a bank will finance every rupee of the total purchase cost. Stamp duty, registration, documentation, and other charges may need to be paid separately. The Reserve Bank of India has issued housing-loan guidance on loan-to-value (LTV) limits and has clarified that certain purchase-related charges are generally not included in the financed property cost for LTV purposes, subject to applicable rules and exceptions.
Set a savings target
Calculate the expected down payment and add estimated purchase costs. Then add moving expenses, basic furnishing, immediate repairs, and a cash buffer. Keep your emergency fund separate from this target.
Protect emergency savings
After paying the down payment, you should still have accessible money for essential expenses and unexpected events. The right reserve depends on job security, dependants, health needs, and whether your income is stable or variable. Many households use several months of essential expenses as a starting point, then adjust based on their circumstances.
Do not invest money needed for an imminent property payment in a volatile asset. If the market falls just before the payment date, you may be forced to sell at a loss. Match the savings method to the time when you need the money.
Step 4: Understand the Full Cost of Buying a Home
The total cost of ownership is higher than the sale price. Make a written list of expected and possible charges, and confirm which ones apply to your transaction.
- Down payment: Your contribution towards the property price.
- Stamp duty and registration: Charges that depend on the state, property value, ownership details, and applicable rules.
- Loan processing and documentation: Fees charged by the lender, which may include legal or valuation charges.
- Brokerage: If an agent is involved, confirm the fee and when it becomes payable.
- Legal review: Independent review of title, agreements, approvals, and related documents.
- Technical inspection: Checks for structural issues, water leakage, electrical concerns, and construction quality.
- Maintenance deposit or society charges: These may apply depending on the property and development.
- Parking, amenities, or other charges: Confirm that every charge is disclosed in the agreement and legally applicable.
- Moving and setup: Transport, appliances, basic furniture, internet, curtains, and other essentials.
- Repairs and renovation: Keep a contingency for work needed before occupation.
- Ongoing costs: Property tax, maintenance, utilities, insurance, and repairs.
Ask for a written cost sheet. Compare it with the agreement and the lender's offer. Avoid relying only on verbal promises about waived charges or future discounts.
Step 5: Compare Home Loans Beyond the Advertised Interest Rate
A home loan is a long-term commitment. Even a small difference in interest rate, fees, or repayment terms can affect the total amount you pay. Compare offers from more than one suitable lender, and read the key facts and loan documents before signing.
Fixed, floating, and reset terms
Loan products can have different interest-rate structures. A floating-rate loan can change when the applicable benchmark or spread changes under the contract. A fixed-rate offer may have conditions about how long the rate stays fixed or how later resets work. Read the terms instead of relying on the label alone.
Compare the full cost
Ask each lender for the interest rate, benchmark and spread where relevant, processing fees, legal and valuation costs, prepayment conditions, late-payment charges, and the total repayment illustration. Check whether an advertised rate is available to you or depends on credit score, income, loan amount, or other conditions.
Choose a manageable tenure
A longer tenure can reduce the EMI but usually increases total interest if the loan remains outstanding for longer. A shorter tenure can reduce total interest but may create a high monthly burden. Choose a term that balances monthly affordability with the overall cost.
Some borrowers prefer to make additional principal payments when they have surplus funds. Before relying on this strategy, check the lender's rules, the loan type, applicable charges, and whether the extra payment is applied to principal. Keep emergency savings before making large voluntary repayments.
Check the loan agreement
Read the sanction letter and final agreement. Confirm the sanctioned amount, disbursement conditions, rate-reset terms, EMI date, tenure, insurance requirements if any, and procedures for partial prepayment or closure. Ask the lender to explain anything you do not understand.
Step 6: Understand EMI and Interest with an Example
An equated monthly instalment (EMI) generally includes principal repayment and interest. In the early years of many standard amortising loans, a larger share of the EMI goes towards interest. As the principal falls, the interest portion usually reduces and the principal portion increases.
For illustration, imagine borrowing ₹40 lakh for 20 years at a hypothetical annual interest rate of 8.5%, assuming the rate remains unchanged and monthly repayment follows a standard amortisation schedule. The EMI would be roughly ₹34,700 per month. Actual figures will vary with the lender's calculation, fees, rate changes, and loan terms.
Use a reliable EMI calculator to compare different loan amounts, rates, and tenures. Then add the EMI to your complete household budget. Do not treat the calculator result as a loan offer or a guarantee that a lender will approve the amount.
Stress-test the loan
Check whether the EMI remains manageable if a floating rate rises, income falls, or household expenses increase. A plan that works only under perfect conditions may be too fragile. Consider choosing a lower property price, making a larger down payment without exhausting reserves, or waiting until income and savings improve.
Step 7: Check Your Credit Profile Before Applying
Lenders commonly review credit history and other financial information when assessing a home-loan application. A strong repayment record may help, but approval also depends on income, existing obligations, employment or business stability, property documents, and lender policy.
Before applying, review your credit report for incorrect balances, unfamiliar accounts, or payment records that do not belong to you. Raise disputes through the relevant credit bureau and lender if you find errors. Pay existing loan and card bills on time, and avoid taking unnecessary new debt while preparing for the purchase.
Do not submit many loan applications without a plan. Compare eligibility and terms first. Ask lenders what checks they will make and whether a formal application will involve a credit enquiry.
Step 8: Research the Property and Verify the Documents
Financial planning is not complete until you confirm what you are buying. A low price does not make a property a good purchase if the title is unclear, approvals are missing, or the building has serious defects.
Check ownership and title
Ask an independent property lawyer to review the title chain, ownership records, encumbrances, and documents relevant to the transaction. The exact checks depend on the state, property type, and history. Do not rely only on the seller's assurance or a broker's summary.
Check approvals and local requirements
Verify applicable building approvals, sanctioned plans, land-use permissions, completion or occupancy certificates where required, and other local records. Ask the lawyer which records must be obtained from the relevant authorities.
For under-construction property
Check the project's registration and disclosures under the applicable Real Estate (Regulation and Development) Act (RERA) framework. Confirm construction milestones, the payment schedule, possession terms, delay clauses, and the developer's track record. A project page or registration entry is useful, but it does not replace independent legal review.
Inspect the physical property
For a completed property, check water supply, drainage, dampness, cracks, electrical fittings, ventilation, lift condition, common areas, parking, and access. Consider a qualified technical inspection if you are not comfortable assessing these issues yourself.
Review the sale agreement carefully
Confirm the property description, total price, payment milestones, possession date, included fittings, maintenance obligations, default terms, refund conditions, and responsibility for outstanding dues. Ensure that any promise important to your decision is documented.
Step 9: Plan for Tax, Registration, and Legal Charges
Property purchases in India can involve stamp duty, registration charges, and other transaction costs. Rates and procedures vary by state and local rules. Confirm the amount with the relevant registration authority or a qualified professional before setting your final budget.
Tax rules may also affect the buyer or seller depending on the transaction. For example, certain purchases can trigger tax-deduction-at-source requirements. The applicable threshold, rate, forms, and responsibilities depend on the law and the transaction details. Do not assume that the seller or broker will handle every tax requirement for you.
Home-loan tax benefits may be available under specific provisions and regimes, but eligibility depends on factors such as the property, loan, use of the house, possession status, taxpayer's circumstances, and the law in force. Do not buy an expensive property solely because you expect a tax deduction. Calculate affordability before considering any possible tax benefit.
Because India's tax framework and section references can change, check current guidance from the Income Tax Department and consult a tax professional where needed. Treat tax benefits as a potential consideration, not as a substitute for a sound purchase budget.
Step 10: Protect Your Household After Purchase
Many first-time buyers focus so much on getting the keys that they overlook the financial changes that follow. Your home becomes part of your household balance sheet, but it also creates new expenses and risks.
Maintain an emergency fund
Keep cash or readily accessible savings for job loss, medical needs, urgent repairs, or temporary income disruption. Avoid using this fund for optional upgrades or furniture.
Review insurance needs
Consider whether you need suitable health, life, or home insurance based on your circumstances. Life cover may be important if family members depend on your income or if a loan would create hardship for them. Compare policy terms, exclusions, premiums, and coverage rather than buying a product only because it is offered with the loan.
Budget for maintenance
Set aside money for repairs, appliance replacement, painting, plumbing, electrical work, and society maintenance. New homes can also have defects or unexpected setup needs. A small monthly reserve can make these costs easier to manage.
Keep long-term savings active
Do not stop retirement contributions or other important savings automatically just to afford a larger home. Review your financial plan and adjust contributions if necessary, but try to preserve a path towards other major goals. A property is one asset; it should not be your only plan for the future.
Common Mistakes First-Time Buyers Should Avoid
- Buying at the top of the budget: Loan eligibility is not the same as comfortable affordability.
- Using every rupee for the down payment: You may be left without money for emergencies and move-in costs.
- Ignoring additional charges: Stamp duty, registration, repairs, and maintenance can materially increase the total cost.
- Comparing only interest rates: Fees, tenure, reset terms, and prepayment conditions also matter.
- Skipping legal review: Property documents can be complex and location-specific.
- Relying on expected future income: A promotion or bonus is not guaranteed.
- Assuming property prices always rise: Markets can stagnate or fall, and selling can take time.
- Over-renovating immediately: Prioritise safety and essential work before expensive upgrades.
- Ignoring household changes: A new child, job move, or care responsibility can change affordability.
- Rushing due to sales pressure: Do not skip checks because a seller says the offer expires today.
A First-Time Property Buyer's Financial Checklist
- Define the purpose, location, and essential needs for the property.
- Calculate a realistic maximum price using take-home income and monthly expenses.
- Save the down payment and purchase charges separately from emergency savings.
- Compare home-loan offers, full costs, tenure, and rate-reset terms.
- Review your credit report and reduce avoidable debt.
- Get a written estimate of stamp duty, registration, legal, and other charges.
- Verify title, approvals, RERA details where applicable, and the sale agreement.
- Inspect the building and estimate immediate repairs or setup costs.
- Stress-test the EMI against higher expenses or lower income.
- Keep an emergency fund and continue essential long-term savings after purchase.
Frequently Asked Questions
1. How much should I save before buying my first property?
Save for the down payment, stamp duty, registration, loan charges, legal checks, moving, basic setup, and repairs. Keep an emergency fund separate. The exact amount depends on the property's price, location, lender, and your financial situation.
2. How much home-loan EMI can I afford?
Choose an EMI that fits your take-home income after essential spending, existing debt, savings, and irregular costs. Stress-test the budget for a period of lower income or higher expenses. A lender's eligibility figure is not a personal affordability recommendation.
3. Should I use all my savings for a down payment?
Usually, no. Keep accessible funds for emergencies and near-term costs. Becoming cash-poor after purchase can make it difficult to handle repairs, medical bills, or an income disruption.
4. Is a fixed-rate home loan always better than a floating-rate loan?
No option is best for everyone. Compare how the rate is set, when it can change, the initial and ongoing costs, repayment flexibility, and your ability to handle higher EMIs. Read the actual loan terms.
5. What extra costs should I plan for in India?
Possible costs include stamp duty, registration, legal and technical checks, processing fees, brokerage, maintenance deposits, moving, repairs, furnishings, insurance, and ongoing property tax and maintenance. Confirm which charges apply locally.
6. What should I check before buying an under-construction home?
Check applicable RERA registration and disclosures, title, approvals, construction milestones, payment schedule, possession terms, delay clauses, and the developer's track record. Ask an independent property lawyer to review the documents.
7. Should I buy property mainly for tax benefits?
No. Tax benefits depend on eligibility and current law, and they do not make an unaffordable property affordable. Base the decision on your budget, housing needs, long-term plans, and the full cost of ownership.
8. How can I protect myself from a property scam?
Verify the seller's identity and ownership, use independent legal review, confirm records with the relevant authorities, read the agreement, and pay through traceable channels. Be cautious of pressure to make a large payment before checks are complete.
Conclusion: Buy a Home That Fits Your Financial Life
Financial planning for a first-time property purchase is about more than arranging a home loan. It means understanding the full cost, preparing a down payment, keeping emergency savings, choosing a manageable EMI, checking the property, and planning for life after possession.
Take your time. Compare lenders, read the documents, verify the legal status, and test your budget against less favourable situations. If the numbers feel tight, consider a less expensive property or wait until your savings improve. A home should provide stability without putting every other financial goal at risk.
For more practical information on personal finance and business, visit Digiifrog.
Official and Helpful References
- Ministry of Housing and Urban Affairs: RERA information
- Reserve Bank of India: Official website and housing finance guidance
- RBI: Master circular reference containing housing-loan guidance
- Income Tax Department: Official portal
- National Housing Bank: Housing finance information
Disclaimer: This article is for general educational purposes and is not individual financial, legal, tax, or property advice. Loan terms, stamp duty, registration charges, tax rules, and property regulations vary and can change. Verify current local requirements and seek qualified professional advice before signing or paying for a property.
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.

Comments (0)
Log in to leave a comment.