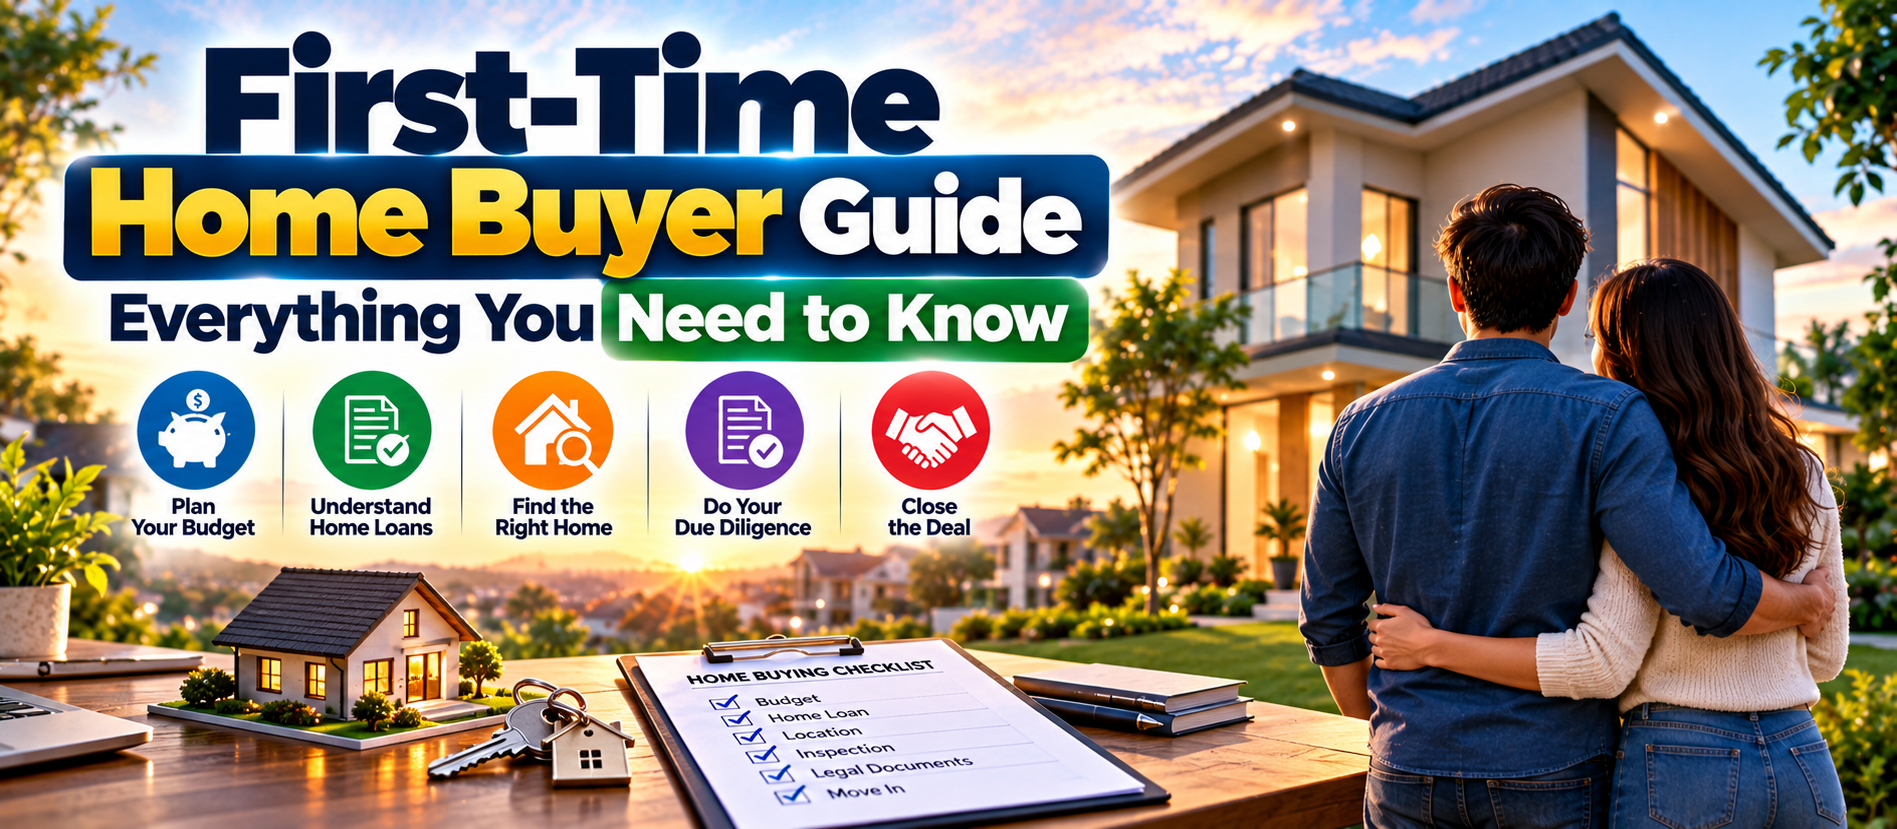
📋 Quick Summary
In this article:
Quick Answer: What Should a First-Time Home Buyer Do First?
1. Decide Whether You Are Ready to Buy
2. Know How Much Home You Can Actually Afford
3. Build a Complete Home-Buying Budget
4. Protect Your Emergency Fund
5. Save for the Down Payment
6. Understand Your Credit Profile
7. Get Pre-Qualified or Pre-Approved Before Serious House Hunting
8. Compare Multiple Lenders
9. Understand the Difference Between Rate and Total Loan Cost
Buying your first home is exciting. It is also a major financial decision. For many people, the process can feel confusing because there are many steps, unfamiliar terms, documents, costs, and decisions.
You may wonder how much home you can afford, how much money you need upfront, whether you should get a mortgage pre-approval, how to choose the right neighborhood, what to look for during a home inspection, how to make an offer, and what happens before you receive the keys.
The good news is that the process becomes much easier when you break it into clear stages.
This First-Time Home Buyer Guide explains the complete journey in simple language. It covers financial preparation, home loans, down payments, property search, due diligence, negotiation, closing, moving, and long-term ownership.
Mortgage rules, taxes, legal requirements, and government assistance vary by country and location. The principles in this guide are broadly useful, but buyers should always confirm local requirements with qualified professionals and official authorities.
Quick Answer: What Should a First-Time Home Buyer Do First?
Do not start by visiting dozens of properties. Start with your finances.
- Review your income, savings, debts, and credit profile.
- Set a comfortable monthly housing budget.
- Build an emergency fund.
- Estimate the down payment and purchase costs.
- Compare mortgage or home-loan options.
- Get pre-qualified or pre-approved where appropriate.
- Choose a realistic location and property type.
- Research properties carefully.
- Get an independent inspection or technical assessment.
- Review legal and ownership documents.
- Make an offer based on market value and your budget.
- Complete financing, legal checks, and closing.
- Keep cash available for repairs, moving, and unexpected expenses.
The goal is not simply to buy a home. The goal is to buy a home that you can comfortably afford and confidently own.
1. Decide Whether You Are Ready to Buy
Owning a home can provide stability and long-term wealth-building potential. But ownership also brings responsibilities that renters may not have.
You become responsible for repairs, maintenance, property taxes or local charges, insurance, utilities, and other ownership costs. The value of the property can also rise or fall.
Before buying, ask yourself:
- Is my income reasonably stable?
- Do I have emergency savings?
- Can I manage a monthly home payment without financial stress?
- Do I expect to stay in the area for several years?
- Can I handle unexpected repairs?
- Have I considered other financial goals?
The Consumer Financial Protection Bureau notes that buying can be risky if your employment is unstable or you may need to move again within a few years because buying and selling can involve significant transaction costs.
2. Know How Much Home You Can Actually Afford
One of the biggest first-time buyer mistakes is confusing what a lender will approve with what you can comfortably afford.
These are not always the same.
Your affordable monthly housing cost may include:
- Loan principal
- Loan interest
- Property taxes or equivalent local charges
- Home insurance
- Mortgage insurance where applicable
- Homeowners' or association fees
- Utilities
- Maintenance
- Repairs
Official consumer guidance recommends including these recurring costs when creating a home-buying budget.
A safe approach is to set your personal maximum before a lender tells you their maximum.
3. Build a Complete Home-Buying Budget
Your home-buying budget should have two parts:
Upfront Costs
- Down payment
- Registration or transfer charges
- Legal fees
- Loan processing fees
- Valuation or appraisal fees
- Inspection costs
- Insurance-related costs
- Moving expenses
- Initial repairs
- Furniture and appliances
Ongoing Costs
- Monthly loan payment
- Property taxes or local charges
- Insurance
- Utilities
- Maintenance
- Repairs
- Association or community fees
- Security and other services
Some official U.S. consumer guidance estimates closing costs at roughly 2% to 5% of purchase price, excluding the down payment, but actual costs vary by location, property type, lender, loan, and transaction.
For buyers outside the U.S., do not assume this percentage applies to your market. Check local taxes and transaction charges.
4. Protect Your Emergency Fund
Do not use every rupee, dollar, pound, or euro you have saved for the purchase.
Homeownership can produce unexpected expenses. A water leak, electrical problem, appliance failure, roof repair, plumbing issue, or urgent maintenance project can arrive at the worst possible time.
Keep an emergency cushion after closing.
CFPB guidance suggests considering an emergency cushion of at least three to six months of expenses when determining how much cash is available for the purchase.
Your personal reserve may need to be larger depending on your income stability, property age, family responsibilities, and local repair costs.
5. Save for the Down Payment
The down payment is the amount you contribute toward the purchase rather than borrowing.
A larger down payment can reduce the amount you borrow. Depending on the loan, it may also reduce mortgage insurance or other financing costs.
But putting more money down is not always automatically better.
If a larger down payment leaves you with no emergency savings, you may create unnecessary financial risk.
Think about the balance between:
- Down payment
- Emergency savings
- Retirement or long-term investments
- Moving expenses
- Renovation needs
- Other major financial goals
6. Understand Your Credit Profile
Lenders use financial information to assess your ability to repay a home loan. Depending on the country, this may include credit history, income, employment, existing debts, assets, and repayment behavior.
Before applying for a mortgage or home loan:
- Review your credit report where available.
- Check for errors.
- Pay bills on time.
- Reduce expensive short-term debt where practical.
- Avoid unnecessary new borrowing.
- Keep financial documents organized.
A stronger financial profile can improve your ability to obtain competitive loan terms, although the exact impact depends on the lender and local market.
7. Get Pre-Qualified or Pre-Approved Before Serious House Hunting
A pre-qualification or pre-approval can help you understand your likely borrowing capacity and show sellers that you are a serious buyer.
The exact meaning differs between lenders and countries. A pre-approval is not necessarily a final loan approval.
CFPB guidance recommends shopping for financing before choosing a home because once an offer is accepted, buyers may have limited time to arrange financing.
Getting financing organized early can also help you compare properties realistically.
8. Compare Multiple Lenders
Do not automatically choose the first bank or lender you speak with.
Compare:
- Interest rate
- Loan term
- Fixed or variable rate
- Processing fees
- Prepayment rules
- Late-payment charges
- Insurance requirements
- Other lender fees
- Total borrowing cost
CFPB guidance recommends comparing loan offers on an apples-to-apples basis and considering both the interest rate and the other costs attached to the loan. It also notes that borrowers can ask lenders whether they can improve their offer.
9. Understand the Difference Between Rate and Total Loan Cost
A low advertised interest rate does not automatically mean the cheapest loan.
A lender may compensate for a lower rate through higher upfront fees, points, processing charges, or other costs.
Ask:
- How much will I pay upfront?
- What is the monthly payment?
- What is the total interest cost?
- Can the rate change?
- Can the payment change?
- Are there prepayment penalties?
- What happens if I refinance?
Compare the complete cost rather than focusing on one number.
10. Choose the Right Location
Location affects your daily life, property value, commute, rental demand, resale potential, and long-term satisfaction.
Do not choose a location only because homes are cheap.
Study:
- Distance to work
- Schools and education
- Healthcare
- Public transportation
- Road connectivity
- Shopping
- Parks and recreation
- Safety
- Noise levels
- Future development
- Flood and environmental risks
- Local property taxes or charges
Visit the neighborhood at different times. A location that feels attractive during the day may feel different during rush hour, late evening, or weekends.
11. Choose the Right Property Type
Your first home does not have to be your dream home.
Choose a property type that fits your current financial position and lifestyle.
Possible options include:
- Apartment
- Condominium
- Townhouse
- Independent house
- Row house
- New construction
- Resale property
Each option has different maintenance, ownership, community, legal, and financial considerations.
12. Decide Between New Construction and Resale
New construction may offer modern layouts, new systems, warranties, and lower immediate repair needs. But buyers may face construction delays, development-area uncertainty, or additional charges.
Resale homes may offer established neighborhoods, mature landscaping, and a better understanding of the surrounding area. However, older systems may require repairs or replacement.
Compare both based on total cost, not just the advertised purchase price.
13. Research the Market Before Making an Offer
Look at recent sales and comparable properties.
Compare:
- Location
- Property size
- Age
- Condition
- Number of rooms
- Parking
- Amenities
- Floor level
- View
- Renovation quality
Do not assume that the seller's asking price represents market value.
Your offer should reflect evidence.
14. Visit More Than One Property
Your first property may feel perfect because it is the first one you see.
Visit several homes before deciding.
Use a comparison sheet and score each property for:
- Price
- Location
- Condition
- Layout
- Natural light
- Ventilation
- Storage
- Parking
- Noise
- Maintenance
- Resale potential
Writing down your observations makes emotional comparison easier.
15. Look Beyond Cosmetic Features
Fresh paint, attractive furniture, decorative lighting, and beautiful landscaping can make a home look better than it really is.
Look deeper.
Check for signs of:
- Water damage
- Dampness
- Cracks
- Roof problems
- Drainage issues
- Electrical problems
- Plumbing problems
- Poor ventilation
- Pest activity
- Old appliances
A beautiful interior cannot compensate for a serious structural or technical problem.
16. Get an Independent Home Inspection
A home inspection or technical assessment can identify problems that a first-time buyer may miss.
Depending on the property, an inspection may examine:
- Structure
- Roof
- Electrical systems
- Plumbing
- Heating and cooling
- Moisture
- Windows and doors
- Drainage
- Safety systems
HUD includes home inspection as a major stage in its home-buying guidance. CFPB also recommends considering inspection contingencies so that serious problems can be addressed before the buyer becomes unconditionally committed, where local law and contract terms permit.
17. Review Legal and Ownership Documents
Do not buy a property based only on a brochure, listing, or verbal promise.
Have qualified local professionals review the relevant documents.
Depending on your jurisdiction, this may include:
- Title or ownership documents
- Previous sale records
- Property tax records
- Building approvals
- Occupancy certificates
- Planning or zoning documents
- Association documents
- Outstanding dues
- Liens or encumbrances
- Lease agreements
- Development approvals
Requirements vary widely by country and state, so local legal advice is important.
18. Understand Property Taxes and Other Local Charges
Property taxes or equivalent local charges can have a major effect on affordability.
Before buying, find out:
- Current annual amount
- How the amount is calculated
- Whether rates can increase
- Outstanding amounts
- Association or community fees
- Special assessments
Do not calculate affordability using the mortgage payment alone.
19. Check Insurance and Property Risk
Insurance protects against certain risks, but coverage differs by policy and location.
Check the cost and availability of appropriate insurance before completing the purchase.
Also investigate:
- Flood risk
- Storm risk
- Fire risk
- Earthquake risk
- Crime risk
- Past property damage
CFPB guidance notes that disaster risk can affect insurance costs and may require additional coverage in some areas.
20. Understand the Offer Process
An offer is more than a number.
Depending on local practice, an offer may address:
- Purchase price
- Deposit or earnest money
- Financing conditions
- Inspection conditions
- Closing date
- Included appliances
- Repairs
- Other conditions
Never sign a document you do not understand.
Use a qualified local professional when necessary.
21. Do Not Let Competition Force You Beyond Your Budget
Multiple offers can create emotional pressure.
It is easy to think:
⚠ Watch Out
“If I do not buy this house today, I will never find another one.”
That mindset can cause buyers to overpay.
Set your maximum offer before negotiations become emotional.
If the price exceeds your budget or the property's defensible value, be prepared to walk away.
22. Understand Closing Costs
Closing is the stage where ownership and financing are formally completed.
Depending on the jurisdiction, closing costs can include:
- Registration or transfer taxes
- Legal fees
- Loan charges
- Valuation fees
- Inspection fees
- Title-related costs
- Insurance
- Government charges
- Prepaid expenses
- Association adjustments
Official U.S. mortgage guidance lists lender charges, points, third-party services, government fees, prepaid expenses, and other home-buying expenses among possible transaction costs.
Your local cost structure may be very different. Obtain a written estimate before committing.
23. Read Every Document Before Signing
Closing documents can contain important financial and legal obligations.
Before signing, check:
- Purchase price
- Loan amount
- Interest rate
- Payment schedule
- Fees
- Property description
- Ownership details
- Conditions
- Insurance requirements
- Penalties
If something looks different from what you were told, stop and ask questions.
24. Plan for the First 90 Days After Buying
The purchase does not end when you receive the keys.
Your first 90 days should focus on safety, maintenance, organization, and financial stability.
First Week
- Change or verify locks and security systems.
- Locate electrical and water shutoffs.
- Check smoke and safety devices.
- Record meter readings.
- Confirm insurance.
- Organize important property documents.
First Month
- Complete urgent repairs.
- Set up maintenance reminders.
- Review utility usage.
- Check plumbing and drainage.
- Build a household maintenance file.
First Three Months
- Review your actual monthly ownership costs.
- Create a maintenance budget.
- Plan non-urgent improvements.
- Review your emergency fund.
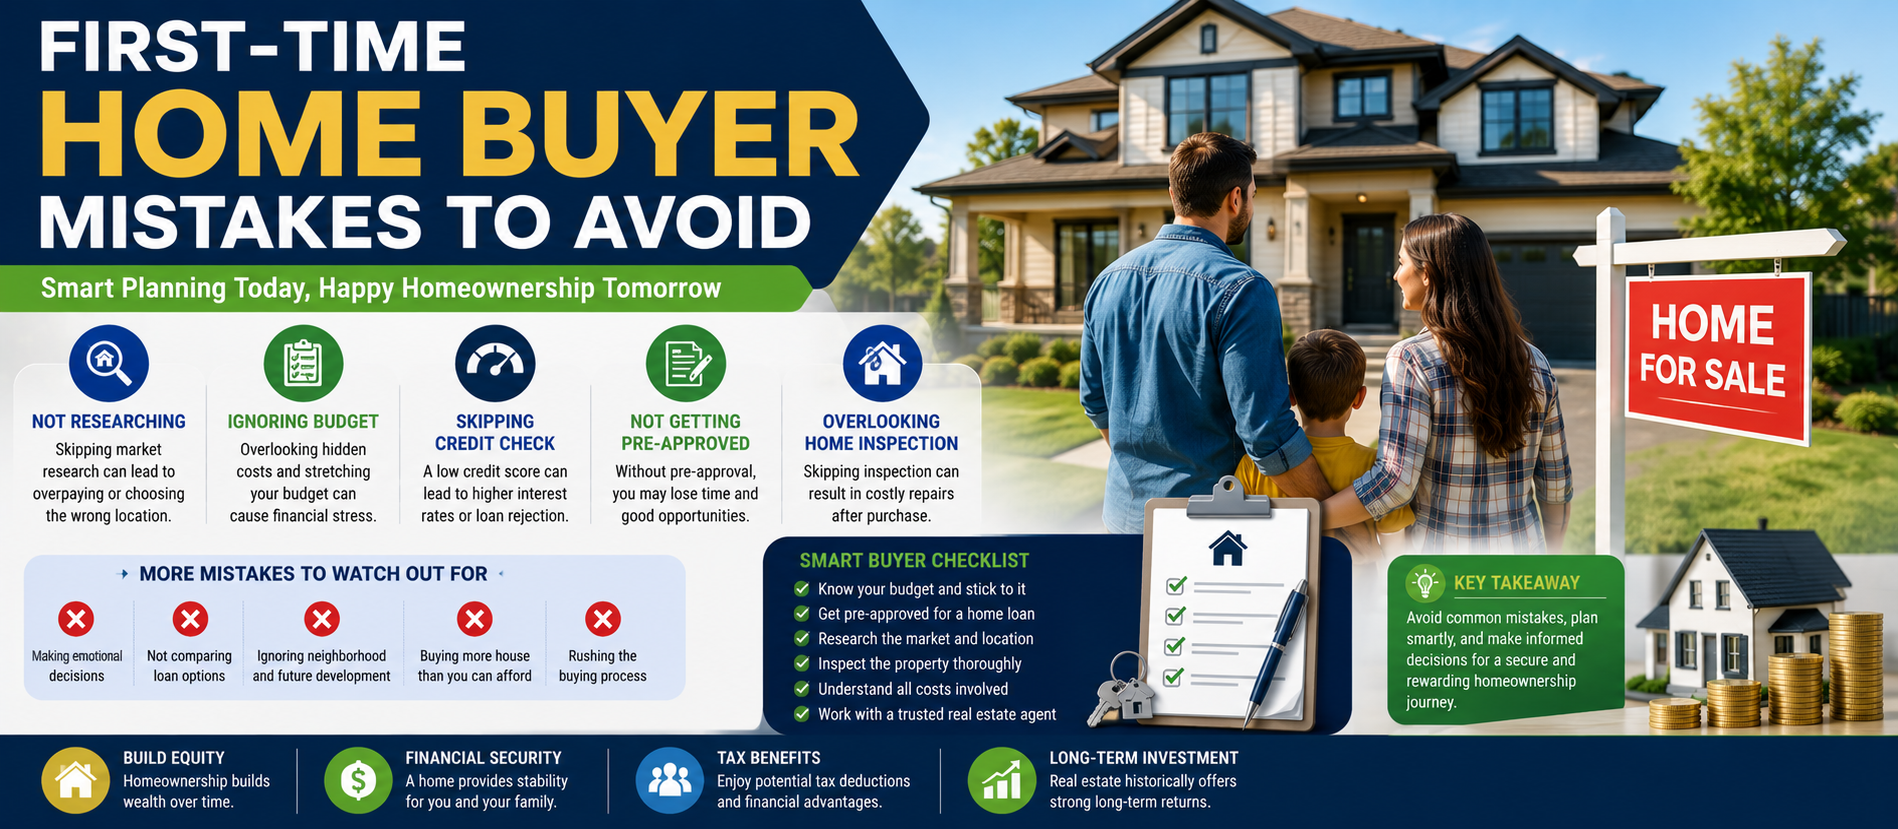
25. Common First-Time Home Buyer Mistakes
Buying at the Maximum Loan Amount
A lender's maximum is not necessarily your comfortable budget.
Using All Your Savings for the Down Payment
Keep an emergency reserve and budget for moving and repairs.
Ignoring Closing Costs
Purchase price is only one part of the transaction.
Skipping the Inspection
A professional inspection can identify expensive problems before you become fully committed.
Choosing a Home Before Choosing a Financing Strategy
Understand your financing capacity first.
Focusing Only on Monthly EMI or Mortgage Payment
Include taxes, insurance, maintenance, utilities, and other recurring costs.
Ignoring the Neighborhood
You are buying the location as well as the building.
Making an Emotional Offer
Decide your maximum price before negotiations become emotional.
Not Thinking About Resale
Your circumstances may change. Consider future demand even if you plan to stay for many years.
26. How to Save Money as a First-Time Buyer
You do not always need to spend more to buy better.
Use these strategies:
- Compare multiple lenders.
- Negotiate lender fees where possible.
- Compare several properties.
- Research recent sales.
- Consider homes that need manageable cosmetic improvements.
- Choose a location with strong fundamentals rather than simply prestige.
- Review association and maintenance costs.
- Do not over-improve beyond neighborhood standards.
- Investigate first-time buyer programs available in your area.
Many locations offer special assistance programs for eligible first-time buyers. Official housing guidance recommends checking government and nonprofit programs before assuming you must fund every cost yourself.
27. Should You Buy a Fixer-Upper?
A property needing work can sometimes offer value. But a renovation project can quickly become expensive.
Before buying, estimate:
- Structural repairs
- Electrical work
- Plumbing
- Roofing
- Kitchen renovation
- Bathrooms
- Flooring
- Painting
- Permits
- Professional fees
- Temporary accommodation if needed
Add a contingency for unexpected problems.
Do not buy a fixer-upper simply because the purchase price looks low.
28. First-Time Buyer Home Inspection Checklist
| Area What to Check | |
| Structure | Cracks, movement, settlement, visible structural concerns |
| Roof | Age, leaks, damage, drainage |
| Plumbing | Leaks, water pressure, drainage, pipe condition |
| Electrical | Panels, wiring, outlets, safety devices |
| Walls & Ceilings | Dampness, stains, cracks, mold |
| Windows | Operation, sealing, damage, condensation |
| HVAC | Age, condition, service history, efficiency |
| Exterior | Drainage, landscaping, walls, paving |
| Safety | Smoke alarms, access, locks, emergency systems |
29. First-Time Buyer Home Buying Timeline
- Months 1–2: Review finances and savings.
- Months 1–2: Check credit and reduce unnecessary debt.
- Months 2–3: Compare home-loan options.
- Months 2–3: Obtain pre-qualification or pre-approval if appropriate.
- Months 3–4: Research neighborhoods.
- Months 3–5: Visit and compare properties.
- After choosing a property: Make an informed offer.
- After acceptance: Complete financing and due diligence.
- Before closing: Review documents and final costs.
- Closing: Complete legal and financial transfer.
- After closing: Move in, secure the property, and establish a maintenance plan.
The timeline can be much shorter or longer depending on your location, financing, property type, and market conditions.
30. First-Time Home Buyer Questions to Ask Your Lender
- What is the interest rate?
- Is the rate fixed or variable?
- What is the total loan cost?
- What fees do I pay upfront?
- Can I make additional payments?
- Are there prepayment penalties?
- What happens if interest rates change?
- What insurance is required?
- How long does approval usually take?
- What documents do you need from me?
- Can you provide a written loan estimate?
31. First-Time Home Buyer Questions to Ask the Seller
- How long has the property been on the market?
- Why are you selling?
- How old are the major systems?
- Have there been major repairs?
- Are there outstanding disputes or dues?
- What fixtures and appliances are included?
- Has the property experienced water damage?
- What are the average utility costs?
- Are there upcoming association or community charges?
- Are there known neighborhood development plans?
32. First-Time Home Buyer Questions to Ask Yourself
- Can I comfortably afford this property?
- Will I still have savings after closing?
- Can I handle a major repair?
- Do I like the location?
- Can I manage the commute?
- Does the property fit my future needs?
- Is the price supported by comparable properties?
- Would I still buy it if the market stopped rising?
- Could I sell it later if my circumstances change?
33. A Simple First-Time Home Buyer Formula
A useful decision framework is:
Affordable Home = Comfortable Monthly Cost + Sustainable Upfront Cash + Emergency Reserve + Realistic Future Expenses
This is not a formal lending formula. It is a personal decision framework.
If buying a home leaves you with no savings, no repair capacity, and no flexibility, the property may be too expensive even if the lender approves the loan.
34. The Role of Technology in Home Buying
Technology can make the buying process easier.
First-time buyers can use digital tools to:
- Compare listings
- Estimate monthly payments
- Track properties
- Compare neighborhoods
- Review maps
- Organize documents
- Calculate renovation budgets
- Compare loan offers
- Schedule inspections
- Communicate with professionals
AI tools can also help summarize documents, create questions for advisers, compare property information, and organize research. But AI should not replace qualified legal, financial, inspection, or valuation professionals.
35. How AI Search Is Changing Home Buying
Home buyers increasingly ask direct questions such as:
- “What can I afford on my income?”
- “Which neighborhood is best for commuting?”
- “What should I inspect before buying?”
- “How much cash do I need to close?”
- “Is this property a good value?”
This means real estate businesses need clear, direct, answer-focused content. Property websites should explain neighborhoods, pricing, financing concepts, amenities, FAQs, and buying processes in language that both people and AI-powered search systems can understand.
36. First-Time Home Buyer Checklist
- Review income and expenses.
- Check credit information where applicable.
- Build an emergency fund.
- Set a realistic monthly housing budget.
- Save for the down payment.
- Estimate closing and transaction costs.
- Compare lenders.
- Get pre-qualified or pre-approved where appropriate.
- Choose a target location.
- Research property prices.
- Visit multiple properties.
- Compare properties objectively.
- Research recent comparable sales.
- Inspect the property.
- Review legal documents.
- Check taxes and recurring fees.
- Check insurance and property risks.
- Make an offer within your budget.
- Complete financing.
- Review closing documents.
- Complete the legal transfer.
- Keep savings available after purchase.
- Set up a maintenance plan.
Frequently Asked Questions
How much money should a first-time home buyer save?
There is no universal amount. You need enough for the down payment, transaction costs, moving expenses, initial repairs, and an emergency reserve. Official U.S. consumer guidance suggests considering three to six months of expenses as an emergency cushion, but your appropriate amount depends on your circumstances.
Should I use all my savings for the down payment?
No. Keeping an emergency reserve is important. A home can require unexpected repairs soon after purchase.
Is pre-approval necessary before buying a home?
Requirements vary. But getting financing organized early can help you understand your budget and demonstrate that you are a serious buyer.
What is the biggest first-time buyer mistake?
One of the biggest mistakes is buying more home than you can comfortably afford. Other common mistakes include ignoring closing costs, skipping inspection, and using all available savings at closing.
Should I get a home inspection?
In most cases, an independent inspection is a valuable part of due diligence. It can identify problems that may not be visible during a normal viewing.
Can I negotiate the home price?
Often, yes. The level of negotiation depends on the market, seller, property, and local practice. Use comparable sales, inspection findings, property condition, and your financing limits as evidence.
What are closing costs?
Closing costs are expenses associated with completing the property purchase and financing. They can include lender fees, legal or title costs, government charges, taxes, inspections, insurance, and prepaid expenses. The exact categories vary by location.
Should I buy a new home or a resale home?
Neither is automatically better. Compare purchase price, construction quality, maintenance, location, warranties, future repairs, amenities, and resale potential.
Are first-time buyer assistance programs available?
Many countries, states, cities, and nonprofit organizations offer programs for eligible buyers. Check official local sources because eligibility and benefits vary.
Should I buy now or wait?
There is no universal answer. The right time depends on your financial readiness, expected length of ownership, local property prices, financing conditions, and personal circumstances. A home should not be purchased only because you expect prices to rise.
How Digiifrog Supports Real Estate Businesses
Digiifrog helps real estate companies, developers, brokers, property managers, and housing brands improve their digital presence through SEO, AEO, GEO, AI Search Optimization, content marketing, website development, digital advertising, social media marketing, and automation.
First-time buyers have many questions before making a purchase. Real estate businesses that answer those questions clearly can build trust and attract better-qualified leads.
Digiifrog can help create search-friendly property pages, neighborhood guides, home-buying resources, FAQs, educational articles, social media campaigns, lead-generation systems, and AI-assisted marketing workflows.
Learn more at www.digiifrog.com.
Conclusion: Buy With Confidence, Not Pressure
Buying your first home is a major milestone. You do not need to know everything on day one.
You need a good process.
Start with your finances. Set a comfortable budget. Build an emergency reserve. Understand your loan. Compare lenders. Research locations. Visit several properties. Inspect the home. Check the legal documents. Understand all costs. Negotiate carefully. Read everything before signing.
💡 Key Insight
Most importantly, do not let excitement replace financial discipline.
The right first home is not necessarily the largest home, the newest home, or the most expensive home. It is a home that fits your life, your location needs, your financial capacity, and your long-term plans.
Buy the home you can comfortably own—not simply the home you can technically finance.
That principle can help turn your first home purchase from a stressful transaction into a strong foundation for the future.
Disclaimer: This article is for general educational and informational purposes only. Mortgage rules, taxes, property laws, closing costs, buyer protections, government programs, and financing requirements vary by country, state, and locality. Always consult qualified local legal, financial, mortgage, tax, real estate, and inspection professionals before making a property purchase.
Research Sources
- Consumer Financial Protection Bureau — Home Buying and Mortgage Guidance
- U.S. Department of Housing and Urban Development — Buying a Home
- Consumer Financial Protection Bureau — Mortgage Shopping and Loan Costs
- Consumer Financial Protection Bureau — Down Payment and Affordability Guidance
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.
Comments (0)
Log in to leave a comment.