📋 Quick Summary
In this article:
Why Home Insurance Is Important
Understand What a Standard Policy Covers
Replacement Cost vs. Market Value
Climate Risks and Home Insurance
Common Mistakes First-Time Buyers Make
SEO, AEO, GEO & AI Search
Introduction
💡 Key Insight
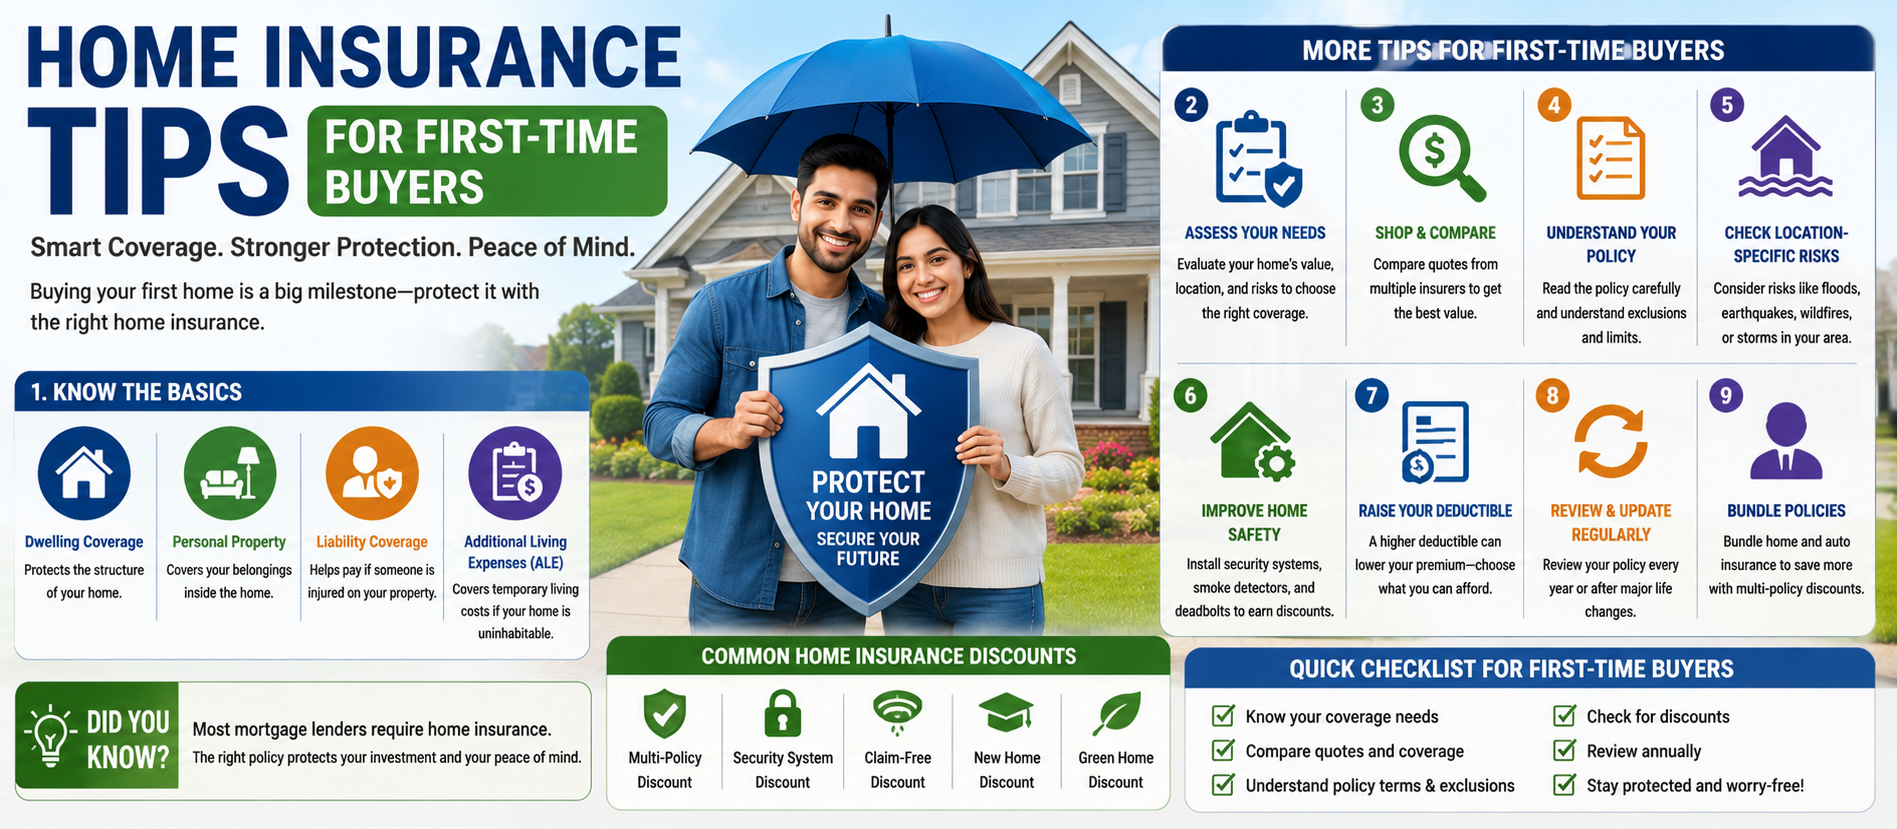
Buying your first home is an exciting milestone, but protecting that investment is equally important. Home insurance safeguards your property, belongings, and finances against unexpected events such as fire, storms, theft, vandalism, liability claims, and certain natural disasters. Many first-time homeowners focus only on premium costs, overlooking critical details such as coverage limits, exclusions, deductibles, replacement cost, and optional endorsements.
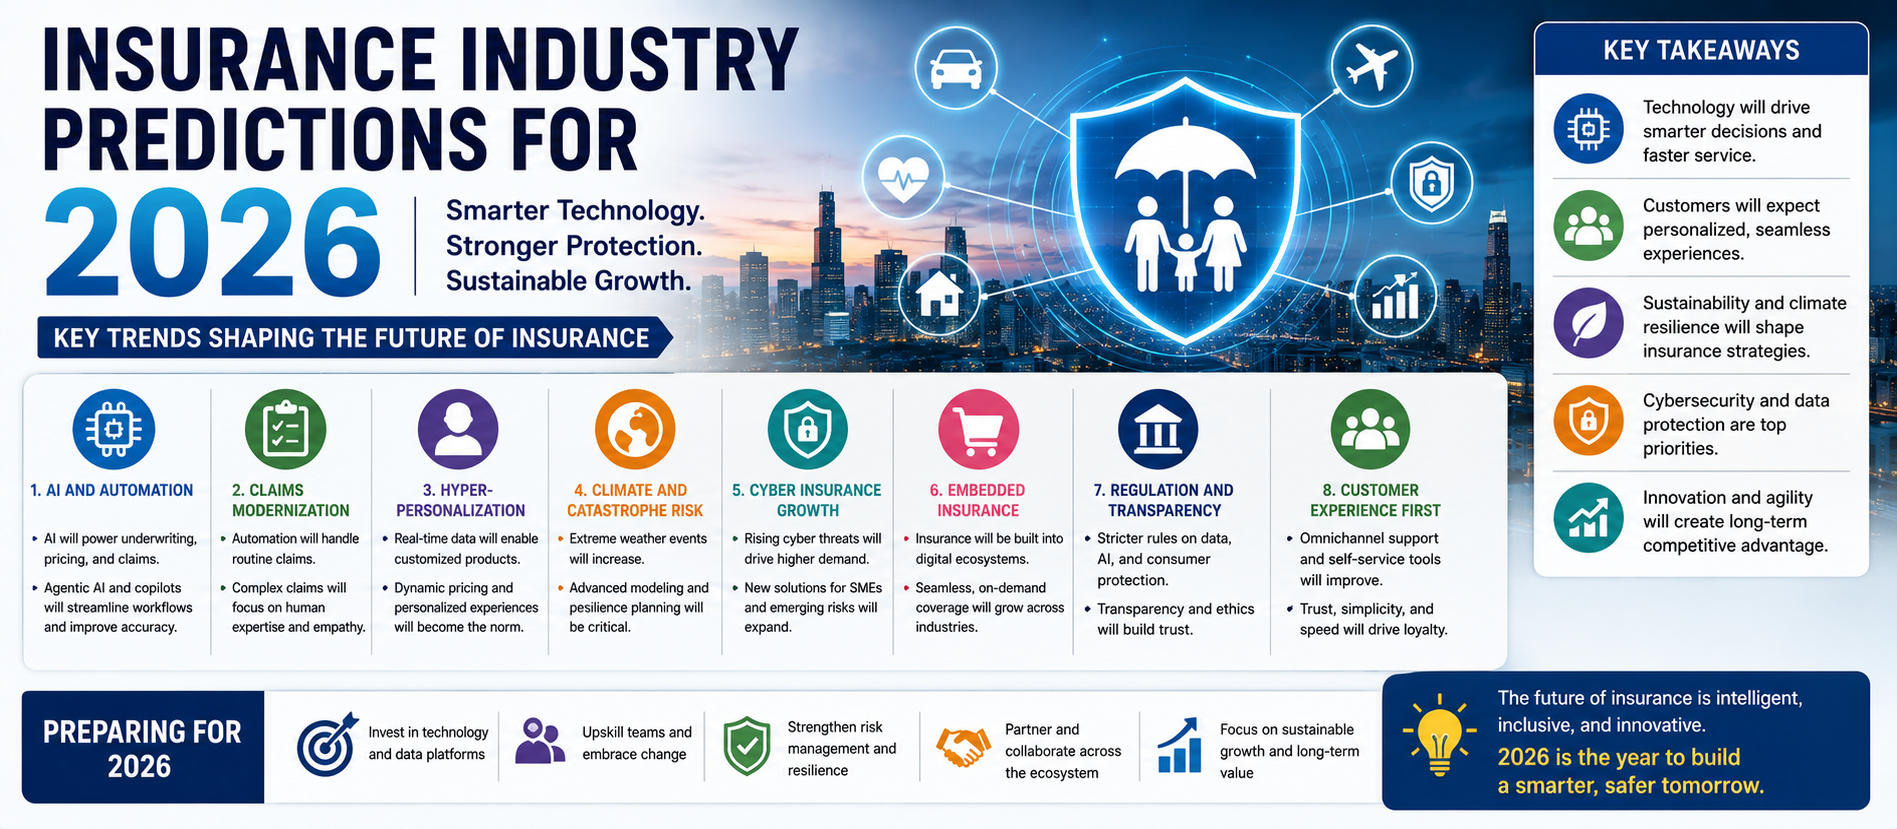
In 2026, rising construction costs, climate-related risks, inflation, and evolving digital threats make choosing the right home insurance policy more important than ever. Understanding how policies work helps homeowners avoid expensive surprises while ensuring long-term financial protection.
This comprehensive WordPress-ready guide from Digiifrog explains everything first-time buyers need to know before purchasing home insurance. It covers coverage options, replacement cost calculations, policy exclusions, premium-saving strategies, AI-powered insurance innovations, claim tips, and practical recommendations. The content is optimized for SEO, AEO, GEO, and AI Search.
Website: www.digiifrog.com
Why Home Insurance Is Important
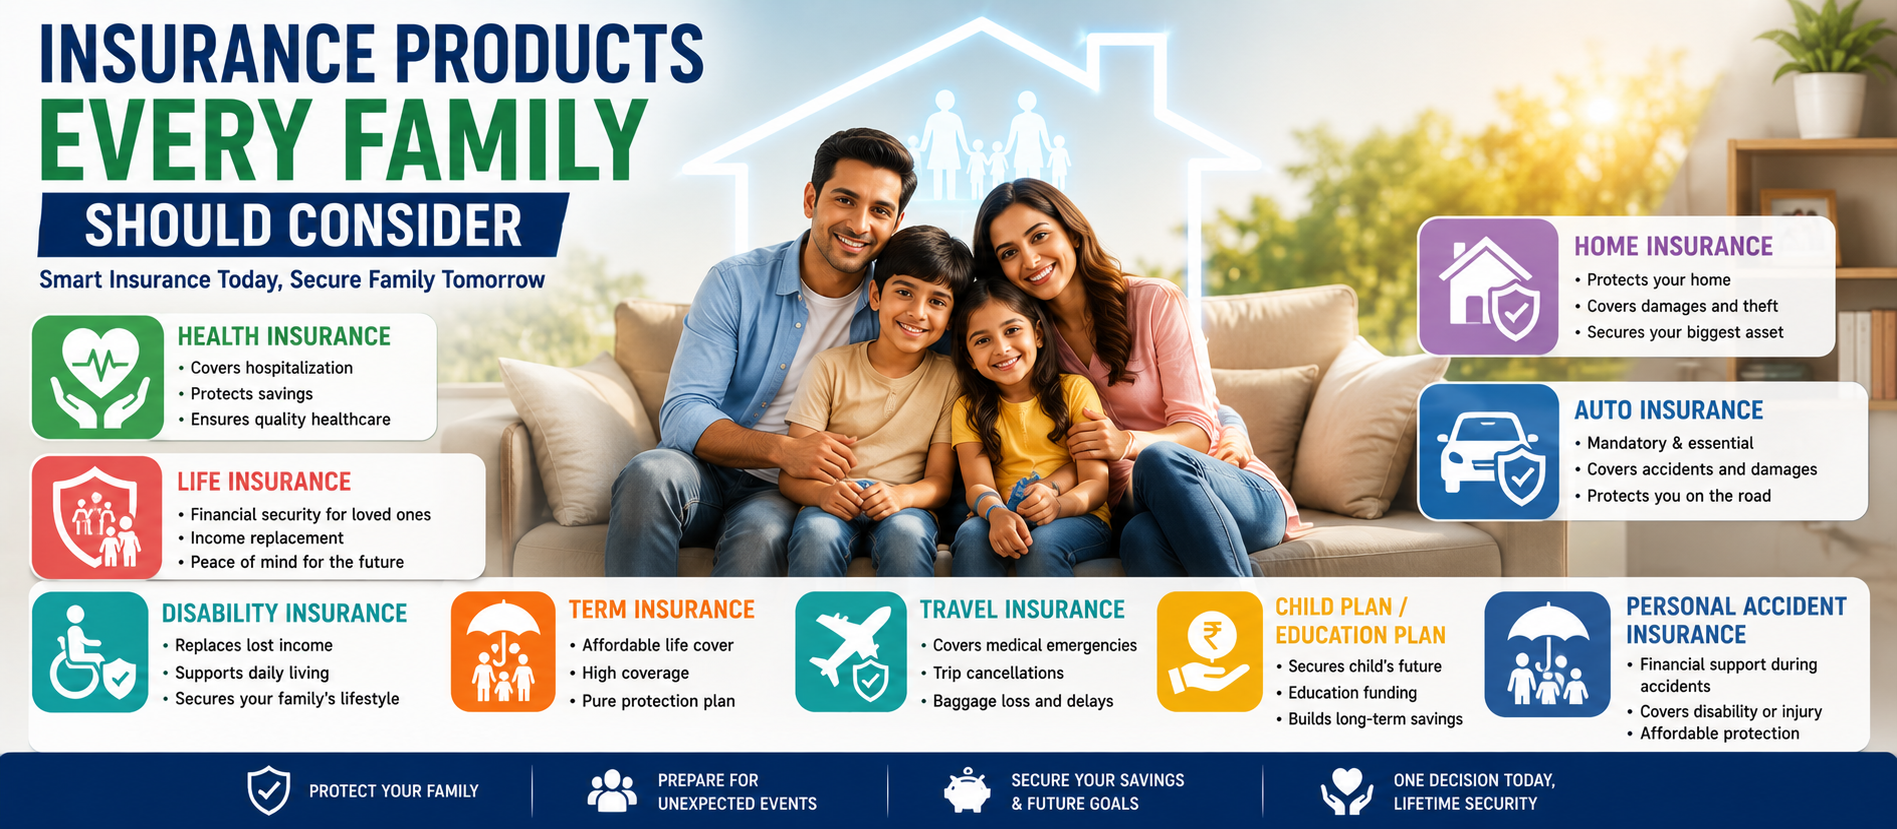
Your home is often your largest financial asset. A quality insurance policy helps protect the structure, personal belongings, legal liability, and temporary living expenses if a covered event makes the property uninhabitable.
- Financial protection against major losses
- Peace of mind
- Mortgage lender requirements
- Liability protection
- Support after natural disasters where covered
Understand What a Standard Policy Covers
- Dwelling coverage
- Other structures such as garages and sheds
- Personal property
- Personal liability
- Medical payments to guests
- Additional living expenses
Replacement Cost vs. Market Value
Insure your home based on replacement cost rather than market value. Replacement cost reflects what it would cost to rebuild your home using current labor and material prices, while market value also includes land value and local real estate demand.
Create a Home Inventory
Document furniture, electronics, appliances, jewelry, artwork, clothing, and valuable possessions. Store photographs, receipts, serial numbers, and digital backups to simplify future claims.
Know the Exclusions
Every policy contains exclusions. Depending on the insurer, flood damage, earthquakes, wear and tear, pest damage, mold, and intentional acts may require separate coverage or may not be covered.
Choose the Right Deductible
A higher deductible can reduce your annual premium, but ensure you can comfortably pay that amount if a claim occurs.
Ways to Lower Premiums
- Bundle home and auto insurance
- Install smoke detectors and monitored security systems
- Upgrade electrical, plumbing, and roofing systems
- Improve storm protection
- Maintain a claims-free history
- Review your policy every year
Climate Risks and Home Insurance
Climate change has increased the frequency of floods, wildfires, severe storms, and extreme weather. Evaluate location-specific risks and consider additional protection if necessary.
AI and Modern Home Insurance
Artificial intelligence, satellite imagery, predictive analytics, drones, digital inspections, and automated underwriting help insurers evaluate properties more accurately, detect fraud, speed up claims, and personalize pricing.
Claim Tips
- Report damage immediately.
- Take clear photographs.
- Prevent additional damage where safe.
- Keep receipts for emergency repairs.
- Maintain copies of all communications.
Common Mistakes First-Time Buyers Make
- Buying the cheapest policy only
- Ignoring exclusions
- Underinsuring the home
- Forgetting valuable personal belongings
- Not updating coverage after renovations
SEO, AEO, GEO & AI Search
Insurance providers increasingly publish educational resources optimized for SEO, AEO, GEO, and AI Search Optimization, helping homeowners compare policies and understand coverage before purchasing.
Frequently Asked Questions
Do I need home insurance if my mortgage lender requires it?
Yes. Most lenders require homeowners insurance to protect the property securing the loan.
Should I buy flood insurance separately?
Standard home insurance often excludes flood damage, so additional coverage may be appropriate depending on location.
How often should I review my policy?
Review your coverage annually and after renovations, major purchases, or significant life changes.
Final Thoughts
Choosing the right home insurance policy is about more than finding the lowest premium. Compare coverage, exclusions, claim service, financial strength, and replacement cost protection. By understanding your risks and reviewing your policy regularly, you can protect your home, your belongings, and your long-term financial future.
Digiifrog
Website: www.digiifrog.com
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.
Comments (0)
Log in to leave a comment.