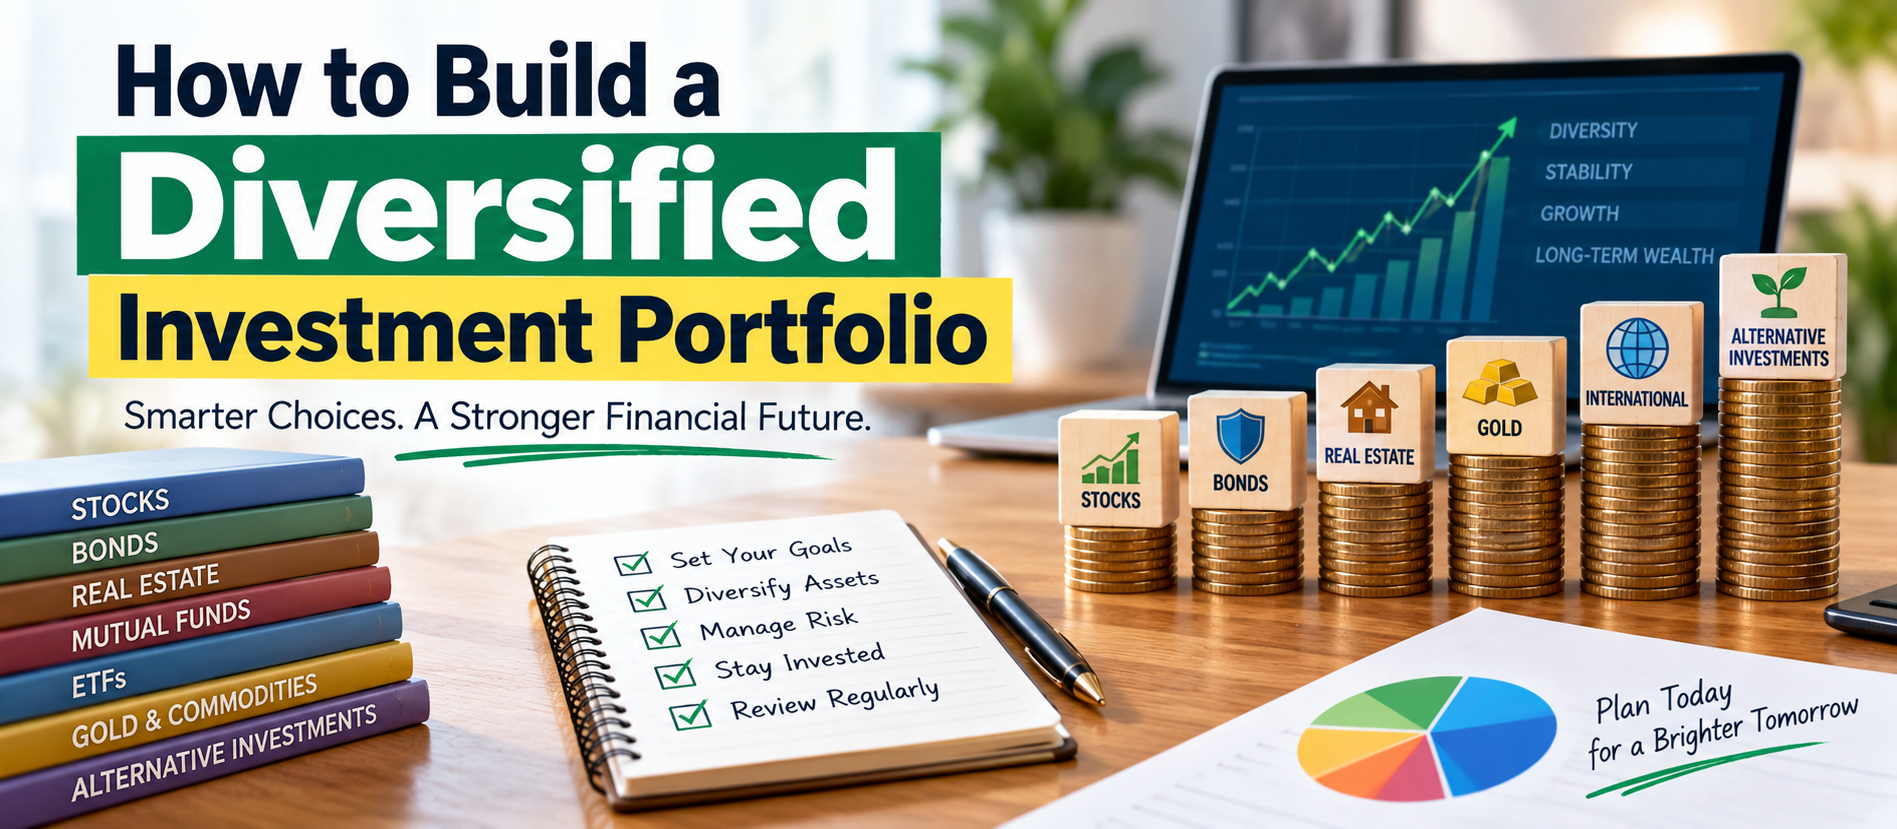
📋 Quick Summary
In this article:
What Is a Diversified Investment Portfolio?
Step 1: Define Your Financial Goals
Step 2: Understand Your Time Horizon
Step 3: Know Your Risk Tolerance
Step 4: Learn Asset Allocation
Step 5: Diversify Within Stocks
Step 6: Consider Geographic Diversification
Step 7: Use Funds Carefully
Step 8: Add Bonds or Other Fixed-Income Investments When Appropriate
Step 9: Keep Emergency Money Separate
Step 10: Watch Investment Costs
⚠ Watch Out
Building a diversified investment portfolio is one of the basic principles of long-term investing. The goal is simple: avoid depending too heavily on one investment, one company, one industry, or one type of asset.
A diversified portfolio does not remove investment risk. Markets can fall, individual investments can lose value, and different asset classes can decline at the same time. Diversification is designed to spread risk so that one weak investment has less power to damage the entire portfolio. Investor.gov explains diversification as spreading money among different investments and notes that it cannot guarantee that a portfolio will avoid losses. Source: U.S. Securities and Exchange Commission, Investor.gov.
This guide explains how to build a diversified investment portfolio in a clear and practical way. It covers financial goals, time horizon, risk tolerance, asset allocation, stocks, bonds, cash, funds, geographic diversification, sector exposure, fees, rebalancing, common mistakes, and portfolio maintenance.
What Is a Diversified Investment Portfolio?
A diversified investment portfolio contains different investments that do not all depend on the same source of risk.
For example, an investor who owns only one company is highly exposed to that company. If the company performs badly, the portfolio can suffer heavily. An investor who spreads money across many companies, industries, asset classes, and regions may reduce the effect of a problem in one area.
Diversification can happen at more than one level. You can diversify between asset classes, such as stocks, bonds, and cash. You can also diversify within an asset class by holding investments across different companies, industries, market segments, or geographic regions. Investor.gov specifically notes that a diversified portfolio should be diversified both between and within asset categories. Source: Investor.gov.
Why Diversification Matters
Different investments can react differently to economic and market conditions. A factor that hurts one investment may have less impact on another.
For example, a technology company may face a business-specific problem while companies in other industries continue to operate normally. A stock market decline may also affect equities differently from cash or some fixed-income investments. These relationships are not guaranteed, but spreading exposure can reduce concentration risk.
The main benefit of diversification is therefore risk management. It is not a promise of higher returns.
A diversified portfolio may also make it easier to stay invested during difficult periods. If every dollar is tied to one volatile investment, a sharp price decline can create strong pressure to sell. A broader portfolio can distribute that exposure across several areas.
Step 1: Define Your Financial Goals
Start with the purpose of the money.
Your portfolio should support a financial goal. That goal might be retirement, a home purchase, education, long-term wealth building, or another future need.
Different goals can require different investment approaches. Money needed soon may need greater stability and liquidity. Money intended for a goal many years away may have more time to experience market ups and downs.
Write down each major goal and answer four questions:
- What is the goal?
- How much money may be needed?
- When will the money be needed?
- How much loss could you financially and emotionally tolerate?
Investor.gov notes that asset allocation depends heavily on an investor's time horizon and risk tolerance. Source: Investor.gov.
Step 2: Understand Your Time Horizon
Your time horizon is the period before you expect to need the money.
A short-term goal and a long-term goal should not automatically use the same portfolio. If money will be needed soon, a large exposure to volatile assets can create a problem if the market falls just before the money is required.
Long-term investors generally have more time to recover from temporary market declines. However, a long time horizon does not make risk disappear.
Consider creating separate buckets for separate goals. For example:
- Short-term bucket: money needed in the near future.
- Medium-term bucket: money for goals several years away.
- Long-term bucket: retirement or other goals that may be decades away.
This approach can help you avoid treating every dollar as if it has the same purpose.
Step 3: Know Your Risk Tolerance
Risk tolerance has two parts: your ability to take risk and your willingness to take risk.
Your financial ability depends on factors such as income stability, savings, debt, emergency reserves, and the timing of your goals. Your willingness is about how you react when investments lose value.
Suppose a portfolio falls sharply. Would you be able to continue following your plan, or would the decline cause you to sell everything? That question matters.
A portfolio that looks acceptable on paper may be difficult to maintain if its losses are larger than you can tolerate.
Do not choose an asset mix only because someone else uses it. Your financial situation and goals are different.
Step 4: Learn Asset Allocation
Asset allocation means dividing a portfolio among different asset categories. Common categories include stocks, bonds, and cash or cash equivalents.
Stocks can provide long-term growth potential but can experience significant price changes. Bonds can provide income and diversification but still carry risks, including interest-rate and credit risk. Cash and cash equivalents can provide liquidity and stability but may have lower long-term growth potential.
The right mix depends on the goal, time horizon, risk tolerance, and other financial circumstances. There is no single asset allocation that is suitable for every investor or every goal. Investor.gov makes the same point in its guidance on asset allocation. Source: Investor.gov.
Step 5: Diversify Within Stocks
If stocks are part of your portfolio, diversification should continue inside the stock allocation.
Do not think that owning several stocks automatically means you are broadly diversified. Ten companies from the same industry may still create a concentrated portfolio.
Consider exposure across different:
- Industries
- Company sizes
- Business models
- Geographic markets
- Economic sectors
For example, a portfolio that contains companies from technology, healthcare, financial services, consumer businesses, industrial companies, and other sectors may have less sector concentration than a portfolio focused on one industry.
Investor.gov also recommends checking the holdings of funds because multiple funds can overlap in their largest positions. Owning several funds does not automatically mean you are diversified. Source: Investor.gov.
Step 6: Consider Geographic Diversification
Geographic diversification means spreading investments across more than one country or region.
Different economies can grow at different rates. They can also respond differently to interest rates, currencies, commodity prices, political events, and economic cycles.
International investments can therefore add another source of diversification. They also introduce additional risks, such as currency movements, different regulations, political conditions, and market structures.
The purpose is not to own every country. The purpose is to avoid making your entire portfolio dependent on one national market.
Step 7: Use Funds Carefully
Mutual funds and exchange-traded funds, or ETFs, can make diversification easier because one fund may hold many securities.
For example, a broad-market fund may provide exposure to a large number of companies through a single investment. This can be simpler than buying many individual stocks.
But fund ownership does not automatically equal diversification.
A fund that focuses on one sector, one theme, or a small group of securities can still be concentrated. Two different funds can also own many of the same companies.
Before adding a fund, check:
- What does the fund hold?
- How many securities does it hold?
- Which holdings are the largest?
- Which sectors dominate?
- Which countries or regions are represented?
- What fees and expenses apply?
- Does it overlap with investments you already own?
Investor.gov notes that mutual funds and ETFs can help investors diversify, while also warning that narrowly focused funds may not provide sufficient diversification. Source: Investor.gov.
Step 8: Add Bonds or Other Fixed-Income Investments When Appropriate
Bonds can play an important role in many diversified portfolios, but they are not risk-free.
Bond prices can change when interest rates move. Corporate bonds also carry credit risk. Longer-maturity bonds can be more sensitive to interest-rate changes than shorter-maturity bonds.
If bonds are appropriate for your goal, consider diversification across issuers, maturities, and bond types rather than depending on one issuer.
Bond funds can provide broad exposure to many bonds. As with stock funds, you should review the fund's holdings, duration, credit quality, fees, and investment objective.
Step 9: Keep Emergency Money Separate
Your investment portfolio should not be your only financial safety net.
An emergency reserve can help cover unexpected costs without forcing you to sell long-term investments at an inconvenient time.
Investor.gov advises investors to prepare for unexpected expenses and highlights the role of savings in financial resilience. Source: Investor.gov.
The exact emergency reserve depends on your household situation. Consider income stability, essential expenses, dependents, debt, insurance, and access to other resources.
Step 10: Watch Investment Costs
Fees can reduce investment returns over time.
Costs can include fund expense ratios, trading costs, account fees, advisory fees, and other charges. Small annual differences can matter over a long investing period because money spent on fees is money that is no longer invested.
Investor.gov includes understanding investment fees and their impact on returns as part of its investor preparedness checklist. Source: Investor.gov.
Do not select an investment only because its fee is low. Review the total cost and understand what you are receiving for that cost.
Step 11: Avoid Accidental Concentration
Concentration can appear in ways that are not obvious.
You may own several funds but discover that many of them hold the same large companies. You may own employer stock while also depending on the same employer for your salary. You may have most of your wealth tied to one property while also carrying debt connected to that property.
Review your complete financial picture instead of looking at one investment account in isolation.
Ask yourself:
- How much of my total wealth depends on one company?
- How much depends on one industry?
- How much depends on one country?
- How much is invested in one asset class?
- Do my funds overlap?
Step 12: Create a Simple Investment Policy
A written investment plan can help you stay consistent.
Your plan can include:
- Your financial goals
- Your time horizons
- Your target asset allocation
- Your diversification approach
- Your contribution schedule
- Your rebalancing method
- Your rules for buying or selling
- Your limits on speculative investments
The plan does not need to be complicated. A one-page document can be enough.
The purpose is to create a process before emotions take over.
Step 13: Rebalance the Portfolio
Over time, investment performance can change your portfolio's allocation.
Imagine that your original plan uses several asset categories. If one category grows much faster than the others, it may eventually represent a larger percentage of the portfolio than you intended.
Rebalancing means bringing the portfolio back toward its intended allocation.
Investor.gov describes several ways to rebalance. An investor can sell part of an overweight investment, add money to an underweight area, or direct new contributions toward underweight categories. Rebalancing can also create transaction costs or tax consequences, so those factors should be considered. Source: Investor.gov.
How Often Should You Review Your Portfolio?
Reviewing your portfolio does not mean checking it every day.
Frequent checking can encourage emotional reactions to short-term price movements. A more useful approach is to review your portfolio at planned intervals and when major personal circumstances change.
Possible review triggers include:
- A major change in income
- A new financial goal
- A major change in your time horizon
- A significant change in your risk tolerance
- A large change in portfolio allocation
- A major life event
The goal is to keep the portfolio connected to your financial plan, not to predict every market move.
Common Diversification Mistakes
1. Owning Too Few Investments
A portfolio built around one or two securities can have significant company-specific risk.
2. Owning Too Many Similar Investments
Twenty investments can still be concentrated if they all depend on the same sector or economic theme.
3. Assuming More Funds Always Means More Diversification
Several funds can have substantial overlap. Review their holdings before adding another fund.
4. Ignoring Fees
Costs can compound over time. Review fees before investing.
5. Chasing Recent Winners
Past performance does not guarantee future results. Buying an asset only because it recently performed well can change the risk profile of your portfolio.
6. Selling Everything During a Market Decline
Market declines can be uncomfortable. A written plan can help you separate short-term market movement from long-term financial goals.
7. Taking More Risk Than the Goal Requires
Higher potential returns usually come with higher risk. The objective is not to maximize risk. The objective is to use an appropriate level of risk for the goal.
8. Forgetting Taxes and Account Rules
Taxes and account rules vary by country and account type. Consider the tax treatment before changing investments, especially when selling appreciated assets.
A Simple Diversified Portfolio Framework
There is no universal portfolio that fits every investor. Instead, use a framework.
Goal: Define what the money is for.
Time horizon: Estimate when you need the money.
Risk tolerance: Understand your ability and willingness to accept losses.
Asset allocation: Decide how the portfolio should be divided among appropriate asset categories.
Within-asset diversification: Spread exposure across companies, sectors, markets, or issuers as appropriate.
Costs: Review fees and expenses.
Rebalancing: Decide how and when you will bring the portfolio back toward its target.
Review: Reassess when your financial circumstances or goals change.
Example of the Process
Consider an investor who is building a portfolio for a long-term goal.
First, the investor identifies the goal and time horizon. Next, the investor reviews income, savings, debt, emergency reserves, and risk tolerance.
The investor then chooses an asset allocation that fits the goal. Within the stock allocation, the investor looks for broad exposure instead of concentrating the portfolio in one company or industry. The investor also reviews the bond and cash portions for diversification and liquidity.
Before buying funds, the investor checks the holdings and compares them with existing investments. This helps identify overlap.
The investor then creates a contribution schedule and a rebalancing rule. Instead of reacting to daily market news, the investor follows the written plan and reviews it periodically.
This example is a process, not a recommendation of a particular portfolio or investment product.
How Technology Can Help
Digital investing tools can make portfolio management easier.
Many platforms can show asset allocation, investment performance, fees, and holdings. Some tools can identify concentration or fund overlap.
Automation can also help investors make regular contributions. However, automation does not replace research. You should understand what you own and why it belongs in your portfolio.
Artificial intelligence can help organize financial information, explain investment terminology, compare fund characteristics, and generate questions for a financial professional. It should not be treated as a substitute for independent verification or personalized professional advice.
How to Build a Diversified Portfolio Step by Step
- Define your financial goal.
- Set the time horizon.
- Review your financial position.
- Understand your risk tolerance.
- Choose an appropriate asset allocation.
- Diversify within each major asset category.
- Check geographic and sector exposure.
- Review fund holdings and overlap.
- Compare investment costs.
- Set a contribution plan.
- Create a rebalancing rule.
- Review the portfolio when your circumstances change.
Frequently Asked Questions
What is the main purpose of a diversified investment portfolio?
The main purpose is to spread investment exposure so that the portfolio does not depend too heavily on one investment, asset class, company, sector, or market.
Does diversification guarantee that I will not lose money?
No. Diversification cannot guarantee against losses. A broad market decline can affect many investments at the same time. Diversification is a risk-management strategy, not a guarantee. Source: Investor.gov.
How many investments should a diversified portfolio have?
There is no universal number. What matters is the actual exposure. A portfolio can hold many investments and still be concentrated if those investments have similar holdings, sectors, or risks.
Are mutual funds and ETFs automatically diversified?
No. Many funds provide broad diversification, but narrowly focused funds may not. Review the fund's holdings, objective, sectors, regions, and overlap with your other investments. Source: Investor.gov.
Should beginners diversify?
Diversification is a basic risk-management concept that can be considered by investors at different experience levels. The appropriate mix depends on the investor's goals, time horizon, risk tolerance, and circumstances.
What is asset allocation?
Asset allocation is the process of dividing investments among categories such as stocks, bonds, and cash. The appropriate mix depends on the financial goal and the investor's circumstances. Source: Investor.gov.
What is portfolio rebalancing?
Rebalancing means adjusting a portfolio so its allocation moves back toward the intended mix after market movements or contributions change the percentages.
Should I review my portfolio every day?
Daily review is usually not necessary for a long-term investment plan. A scheduled review process can help you focus on allocation, diversification, costs, and changes in your financial goals.
Can diversification reduce investment risk?
Yes, diversification can reduce concentration and company-specific risk. It cannot eliminate market risk or guarantee positive returns. Source: Investor.gov.
Should I diversify across countries?
Geographic diversification can reduce dependence on one national market, but international investments also add risks such as currency, regulatory, political, and market-structure risks.
Final Thoughts
A diversified investment portfolio is built around a process, not a collection of random investments.
Start with your goals. Understand your time horizon. Assess your risk tolerance. Choose an asset allocation that fits the goal. Then diversify within the major asset categories.
Pay attention to overlapping holdings and investment costs. Keep emergency money separate from long-term investments when appropriate. Rebalance according to a defined process rather than reacting to every market headline.
💡 Key Insight
Most importantly, remember that diversification is about managing concentration and spreading risk. It does not guarantee profits or prevent losses.
For more practical guides on finance, technology, business, and digital growth, visit www.digiifrog.com.
Disclaimer: This article is for educational and informational purposes only. It is not investment, tax, legal, or financial advice. Investment values can rise and fall, and you may lose money. Consider your own circumstances and consult a qualified financial professional when appropriate. Investment rules, taxes, and regulations vary by country and can change over time.
Sources for Further Reading
- U.S. Securities and Exchange Commission / Investor.gov: Diversify Your Investments
- U.S. Securities and Exchange Commission / Investor.gov: Asset Allocation and Diversification
- U.S. Securities and Exchange Commission / Investor.gov: Beginners' Guide to Asset Allocation, Diversification, and Rebalancing
- U.S. Securities and Exchange Commission / Investor.gov: Investor Preparedness Checklist
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.

Comments (0)
Log in to leave a comment.