📋 Quick Summary
In this article:
Quick Answer: What Is Renters Insurance?
How Does Renters Insurance Work?
What Does Renters Insurance Usually Cover?
1. Personal belongings
2. Personal liability
3. Additional living expenses
4. Medical payments to others
5. Optional protection
Key Benefits of Renters Insurance
It can help protect your belongings
It may help with liability costs
Quick Answer: What Is Renters Insurance?
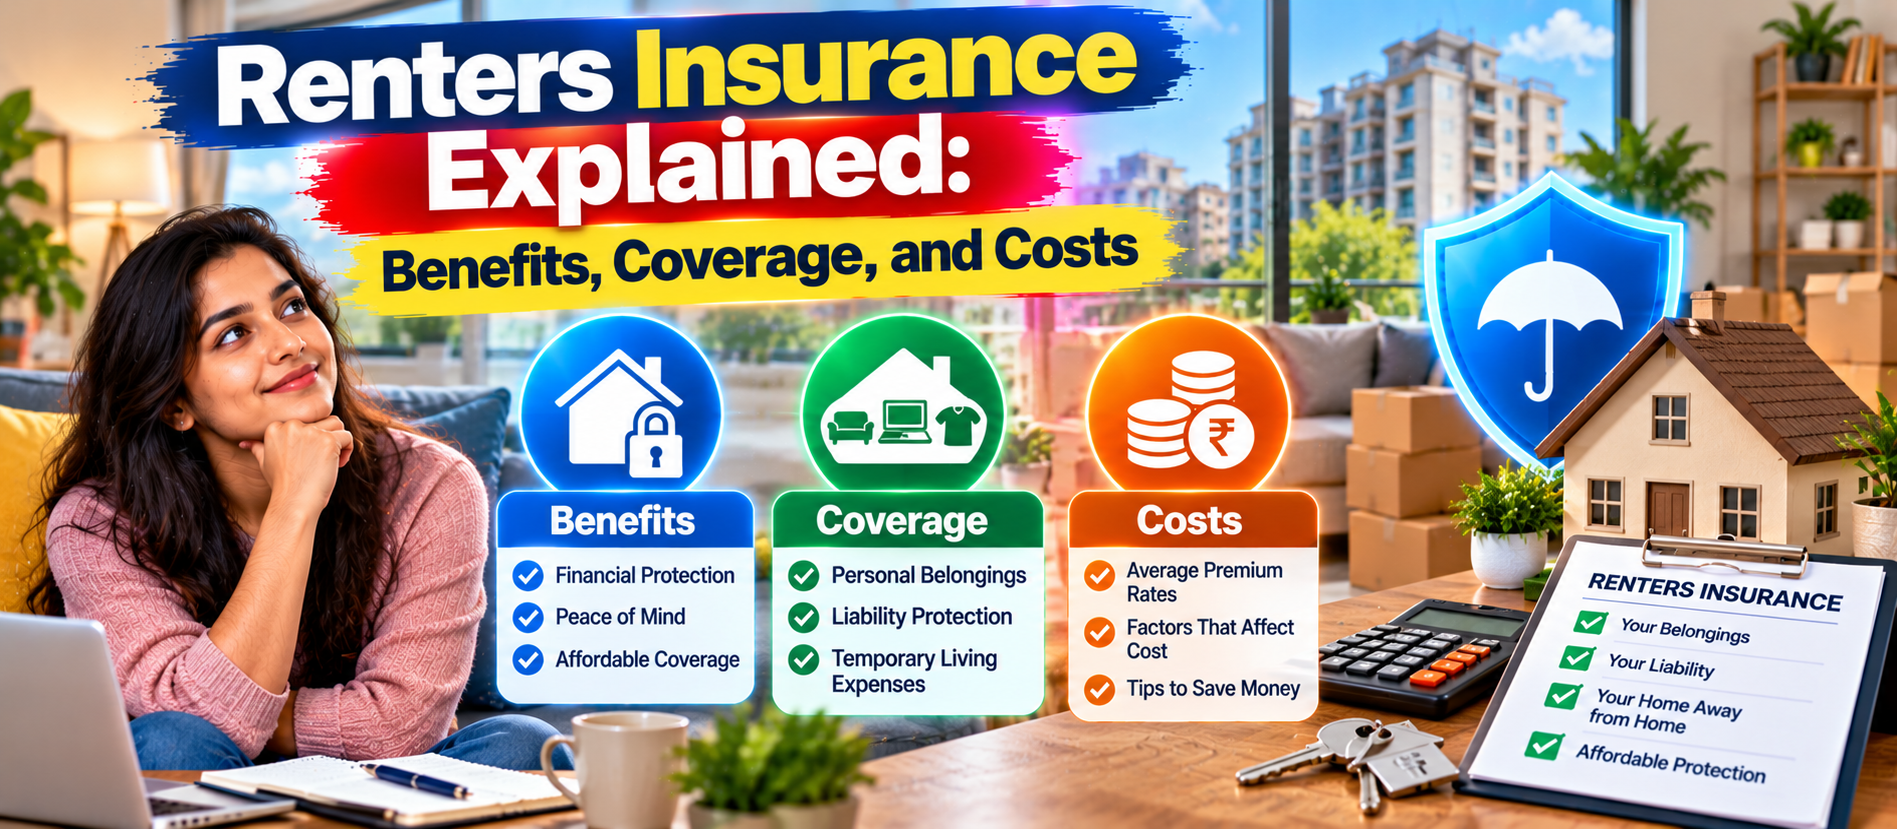
Renters insurance is designed for people who rent a home, apartment, or similar living space. Depending on the policy, it can protect personal belongings, provide personal liability cover, and help pay certain extra living costs after a covered event. It usually does not insure the building itself. The property owner generally arranges building insurance, while a renter may need separate protection for their possessions and liability.
Costs depend on location, cover limits, deductible, property type, claims history, and optional benefits. Before buying, make an inventory of your belongings, compare policy wording, and confirm which events are covered. The term “renters insurance” is common in markets such as the United States. Products and terminology may differ in India and other countries.
Introduction
Renting a home can offer flexibility. You may be living in your first apartment, sharing a flat, studying away from home, or renting while you save for a property. But even a rented home contains items that can be expensive to replace. Furniture, clothing, a laptop, a phone, kitchen equipment, and other everyday possessions can add up to a large amount.
A fire, theft, burst pipe, or other unexpected event can damage those belongings. You may also face a liability claim if you accidentally injure someone or damage another person's property. In some situations, covered damage may make your home temporarily unfit to live in, creating extra costs for accommodation or meals.
Renters insurance is designed to help with certain financial risks. It does not cover every event and does not replace careful planning. This guide explains common benefits, coverage limits, exclusions, costs, and practical steps for comparing policies. Insurance rules and products vary by country. If you rent in India, ask about home contents insurance, tenant liability cover, or other locally available options.
How Does Renters Insurance Work?
You choose a policy with specific cover limits and pay the required premium. If a covered event causes a loss, you contact the insurer and file a claim. The insurer reviews the facts, documents, policy terms, deductible, and applicable limits before deciding whether to pay and how much is payable.
For example, a covered fire might damage your furniture and clothing. You may submit photographs, an inventory, purchase records if available, and other requested documents. The insurer assesses the loss under the policy. You may need to pay a deductible, which is the amount you bear before the insurer pays eligible costs.
Renters insurance is not a maintenance plan. It generally does not pay for normal wear and tear, gradual damage, or every problem that happens in a rented property. It also does not automatically cover a landlord's property or a roommate's belongings. Read the contract to understand what is and is not protected.
What Does Renters Insurance Usually Cover?
Many renters policies combine several types of protection. Details differ by insurer and country, so the categories below are common examples rather than a promise that every policy includes them.
1. Personal belongings
Personal property cover can help pay to repair or replace belongings after a covered event. Items may include clothing, furniture, electronics, books, kitchen equipment, and hobby equipment. The policy may cover belongings inside your rented home and, in some cases, certain items away from home. Limits and conditions apply.
Make an inventory before choosing a limit. Walk through each room and estimate the cost of replacing the items you own. Remember small items such as shoes, bags, utensils, bedding, and accessories. Their combined value can be higher than expected. High-value items such as jewellery, watches, cameras, musical instruments, or collectibles may have special limits. You may need to list them separately or buy extra cover.
2. Personal liability
Personal liability cover may help if you are legally responsible for certain accidental injuries to another person or damage to someone else's property. A guest might be injured in an incident for which you are legally liable, or you might accidentally cause damage to a neighbour's property. Coverage depends on the policy wording and the facts. Check the limit and the types of claims excluded.
3. Additional living expenses
Some policies help pay certain extra living costs if a covered event makes your rented home unfit to live in. This may include temporary accommodation or other necessary additional expenses. It usually does not pay every cost you choose to incur, and limits or time restrictions may apply. Ask what counts as an eligible expense and keep receipts.
4. Medical payments to others
Some policies include a limited benefit for certain medical expenses if a guest is injured, even where legal liability has not been established. Availability and conditions depend on the product and jurisdiction. This benefit is not the same as comprehensive health insurance.
5. Optional protection
Some insurers offer extra cover for selected valuable items, water-related damage, identity-related expenses, or other specified risks. Names and availability vary. An add-on only provides the protection stated in its contract and may have separate limits, deductibles, conditions, or exclusions.
Key Benefits of Renters Insurance
It can help protect your belongings
Replacing all your belongings after a major loss may be difficult. Personal property cover can reduce the financial pressure when the cause of loss is covered. The policy may pay based on replacement cost or actual cash value, depending on the contract. These methods can produce different settlement amounts.
It may help with liability costs
An accident can lead to a claim from another person. Liability cover may help with eligible costs if the event is covered and you are legally responsible. Without suitable protection, you may have to manage the expense yourself.
It can help during temporary displacement
If a covered event makes your home unliveable, temporary accommodation can be expensive. An eligible additional living expense benefit may help with some of the extra cost. Check the maximum amount and time period in the policy.
It clarifies landlord and tenant protection
A landlord's policy may cover the building and the owner's property. It should not be assumed to cover the renter's belongings or personal liability. Ask the landlord what their policy covers, then arrange separate protection if needed.
What Does Renters Insurance Usually Not Cover?
Exclusions explain where a policy will not respond. Common limitations may include the following, but the exact list depends on the insurer and product:
- Flood damage: Standard policies in some markets exclude flood losses or require separate protection.
- Earthquake damage: This may be excluded or require a separate option.
- Wear and tear: Age, deterioration, long-term moisture problems, and lack of maintenance are often treated differently from sudden accidental damage.
- Intentional damage: Damage caused deliberately by the insured person is generally not covered.
- Business property: Items used for business and business-related liability may have limits or exclusions.
- Roommate belongings: A policy for one renter may not cover another person's possessions.
- High-value items: Jewellery, art, or specialised equipment may need extra cover.
- The building itself: A renter's policy is generally not designed to insure the landlord's building.
Do not rely on this list alone. Read the policy wording and ask about risks that matter to you, especially if you live in an area prone to flooding, storms, earthquakes, or water leaks.
How Much Does Renters Insurance Cost?
There is no single price. Premiums depend on the country, city, risk level, cover amount, deductible, building features, claims history, and optional benefits. The same cover can cost different amounts from different insurers.
- Coverage limit: Higher personal property or liability limits can increase the premium.
- Deductible: A higher deductible may lower the premium, but you pay more when making an eligible claim.
- Location: Local theft, weather, and other risks may affect pricing.
- Building features: Security systems, fire safety, and the type of building may influence a quote.
- Claims history: Previous claims may affect eligibility or price.
- Optional cover: Add-ons and extra limits may increase the cost.
When comparing quotes, check that policies offer similar limits and cover. A lower price may reflect a higher deductible, a lower personal property limit, or more exclusions. Ask for a written quote showing the premium, deductible, limits, special limits, and optional benefits.
Replacement Cost vs Actual Cash Value
One important detail in personal property cover is how the insurer values damaged or stolen belongings.
Replacement cost
A replacement-cost approach may pay the eligible cost to replace an item with a similar new item, subject to policy conditions and limits. Some policies first pay an actual cash value amount and release the remaining eligible amount after you replace the item and provide proof. Check the exact process.
Actual cash value
An actual-cash-value approach generally considers depreciation or the item's age and condition. The payment for an older item may be lower than the price of buying a new one. A laptop bought several years ago, for example, may cost much more to replace today than its depreciated value. Compare the premium and policy details, and ask the insurer for a practical example.
How Much Renters Insurance Do You Need?
Start by estimating the cost of replacing your belongings. Walk through each room and list furniture, electronics, clothing, kitchen items, bedding, tools, books, and personal equipment. Use realistic replacement prices rather than the amount you might receive by selling used items.
Next, consider liability protection. Think about the possible cost of a serious claim and compare available limits. Then check whether you need special cover for valuable items. Keep receipts, photographs, serial numbers, appraisals, or other records where available. Store a copy of your inventory somewhere other than the rented home, such as a secure digital location.
Finally, consider temporary accommodation. Review the policy's additional living expense limit and decide whether it would be enough for your area and household size. The right amount should reflect your risks and budget, not simply the smallest amount available.
How to Choose the Right Renters Insurance Policy
- List your belongings. Estimate the cost to replace the items you own.
- Choose a personal property limit. Match it to your inventory and check special item limits.
- Review liability protection. Compare available limits and understand covered incidents.
- Check temporary living expense cover. Confirm eligible expenses and limits.
- Compare deductibles. Choose an amount you could afford after a loss.
- Read exclusions. Pay attention to flood, earthquake, water damage, business property, and high-value items.
- Compare quotes fairly. Check the same limits, deductible, valuation method, and add-ons.
- Check the claims process. Find out how to report a loss and what evidence is needed.
- Review the policy each year. Update cover when you buy expensive items, move, or change household circumstances.
- Keep records safe. Store the policy, receipts, inventory, and insurer contact details where you can find them.
Does a Landlord's Insurance Cover the Renter?
Usually, a landlord's property insurance is intended to protect the building or the landlord's own property, subject to its terms. It should not be assumed to insure the tenant's personal belongings or personal liability.
If a covered fire damages the building and your clothes, laptop, and furniture, the landlord's policy may address the building owner's insured loss. Your possessions may need separate cover. The actual result depends on each policy and the facts of the event. If your lease requires insurance, confirm the required type and limits before signing or renewing.
What If You Share a Home With Roommates?
Do not assume one renter's policy automatically covers every person who lives in the property. Coverage for roommates depends on the policy wording and local rules. Some insurers may allow certain household members to be included, while others may require separate policies.
Discuss who owns shared items and how they would be replaced after a loss. Tell the insurer that you share the home and ask for written confirmation of who is insured. This can help avoid confusion at claim time.
How to Make a Renters Insurance Claim
If an event damages your belongings, protect people first and contact emergency services if needed. Take reasonable steps to prevent further damage, but do not put yourself at risk. Notify your insurer promptly and follow its instructions.
- Report the event. Use the insurer's official phone number, website, or app.
- Document the loss. Take photos or videos when safe and list damaged or missing items.
- Keep evidence. Save receipts, invoices, police reports where applicable, and relevant messages.
- Complete the claim form. Give accurate information and keep a copy.
- Ask about inspection. The insurer may need to inspect damage or request more documents.
- Review the settlement. Check the deductible, item limits, valuation method, and deductions.
Do not discard damaged items before the insurer confirms whether it needs to inspect them, unless disposal is necessary for safety or sanitation. If a claim is declined or the payment seems incorrect, ask for the reason in writing, review the policy wording, and use the insurer's official complaint process if needed.
Common Renters Insurance Mistakes to Avoid
- Guessing the coverage limit: Make an inventory and estimate replacement costs.
- Assuming every disaster is covered: Check flood, earthquake, and water-damage exclusions.
- Forgetting expensive items: Ask about special limits for jewellery, cameras, musical instruments, and collections.
- Choosing a deductible that is too high: Select an amount that fits your accessible savings.
- Relying on the landlord's policy: Confirm whether you need your own contents or liability cover.
- Not updating the policy: Review it after moving or buying expensive equipment.
- Not keeping evidence: Store receipts, photos, serial numbers, and an inventory safely.
Renters Insurance and Tenant Protection in India
The phrase “renters insurance” is widely used in some countries, especially the United States. In India, available products, terminology, and policy structures may differ. A tenant may need to look for home contents insurance, tenant liability cover, personal accident cover, or another suitable product depending on the risk they want to protect against.
Do not assume that a policy marketed as home insurance automatically covers a tenant's belongings or liability. Read the product wording and confirm who is insured, what property is covered, which events are included, and whether the policy can be purchased by a tenant rather than only a property owner.
Before buying in India, check the insurer's official policy documents and current regulatory information from the Insurance Regulatory and Development Authority of India (IRDAI). Ask the insurer to confirm the policy's suitability for a rented home. Product availability and rules may change, so compare current options rather than relying only on information from another country.
Frequently Asked Questions (FAQs)
1. What is renters insurance?
It is designed for people who rent a home. Depending on the policy, it can cover personal belongings, certain liability claims, and some additional living expenses after a covered event.
2. Does renters insurance cover the building?
Usually, it focuses on the renter's belongings and certain liabilities, not the building itself. The property owner generally arranges building insurance.
3. Does renters insurance cover theft?
Belongings stolen in a covered event may be insured, subject to policy conditions, limits, deductible, and exclusions. Report theft to the police when required and contact the insurer promptly.
4. Does renters insurance cover flood damage?
Flood damage may be excluded from standard cover in some markets or require separate protection. Check the exact wording in your policy.
5. How much renters insurance do I need?
Estimate the cost of replacing your belongings, consider suitable liability limits, and review any temporary living expense benefit. Consider extra cover for valuable items if needed.
6. Is renters insurance expensive?
The cost varies by location, cover limits, deductible, property features, claims history, and optional benefits. Compare quotes with similar coverage before deciding.
7. What is a deductible in renters insurance?
A deductible is the amount you pay toward an eligible claim before the insurer pays the remaining covered amount, subject to policy terms. A higher deductible may lower the premium but increases your share of a claim.
8. Are roommates covered under one policy?
Not automatically. Coverage depends on the policy and local rules. Ask the insurer to confirm who is insured and whether separate policies are needed.
9. Does renters insurance cover items used for work?
Business property and work-related risks may have special limits or exclusions. If you work from home or own costly equipment, ask the insurer what protection is available.
10. How do I file a renters insurance claim?
Notify the insurer, document the loss, keep receipts and evidence, complete the claim form, and follow inspection instructions. Review the settlement and ask for a written explanation if you disagree.
11. Does renters insurance cover a hotel after a fire?
Some policies include additional living expense cover when a covered event makes the home unfit to live in. Eligible costs, limits, and time restrictions vary.
12. Is renters insurance available in India?
Products and terminology vary. Ask insurers about home contents or tenant-focused cover and confirm that the policy is available to renters and protects the risks you need covered.
Conclusion: Is Renters Insurance Worth Considering?
Renters insurance can help protect the things you own and may provide liability or temporary living expense benefits after certain covered events. It is most useful when the coverage matches your real risks and the limits are high enough to matter.
Before you buy, list your belongings, check special limits, understand the deductible, compare exclusions, and confirm whether the policy covers your situation as a tenant. Do not choose only by premium. A low-cost policy may offer less protection than you need.
Because insurance products vary by country and insurer, review the full policy wording and ask questions before paying. For more practical digital resources and helpful guides, visit Digiifrog.
Disclaimer
This article is for general educational purposes only. It is not personal insurance, legal, or financial advice and does not recommend a specific insurer or policy. Coverage, prices, policy terms, and regulations vary by country and may change. Read current policy documents and speak with a qualified professional about your circumstances.
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.
Comments (0)
Log in to leave a comment.