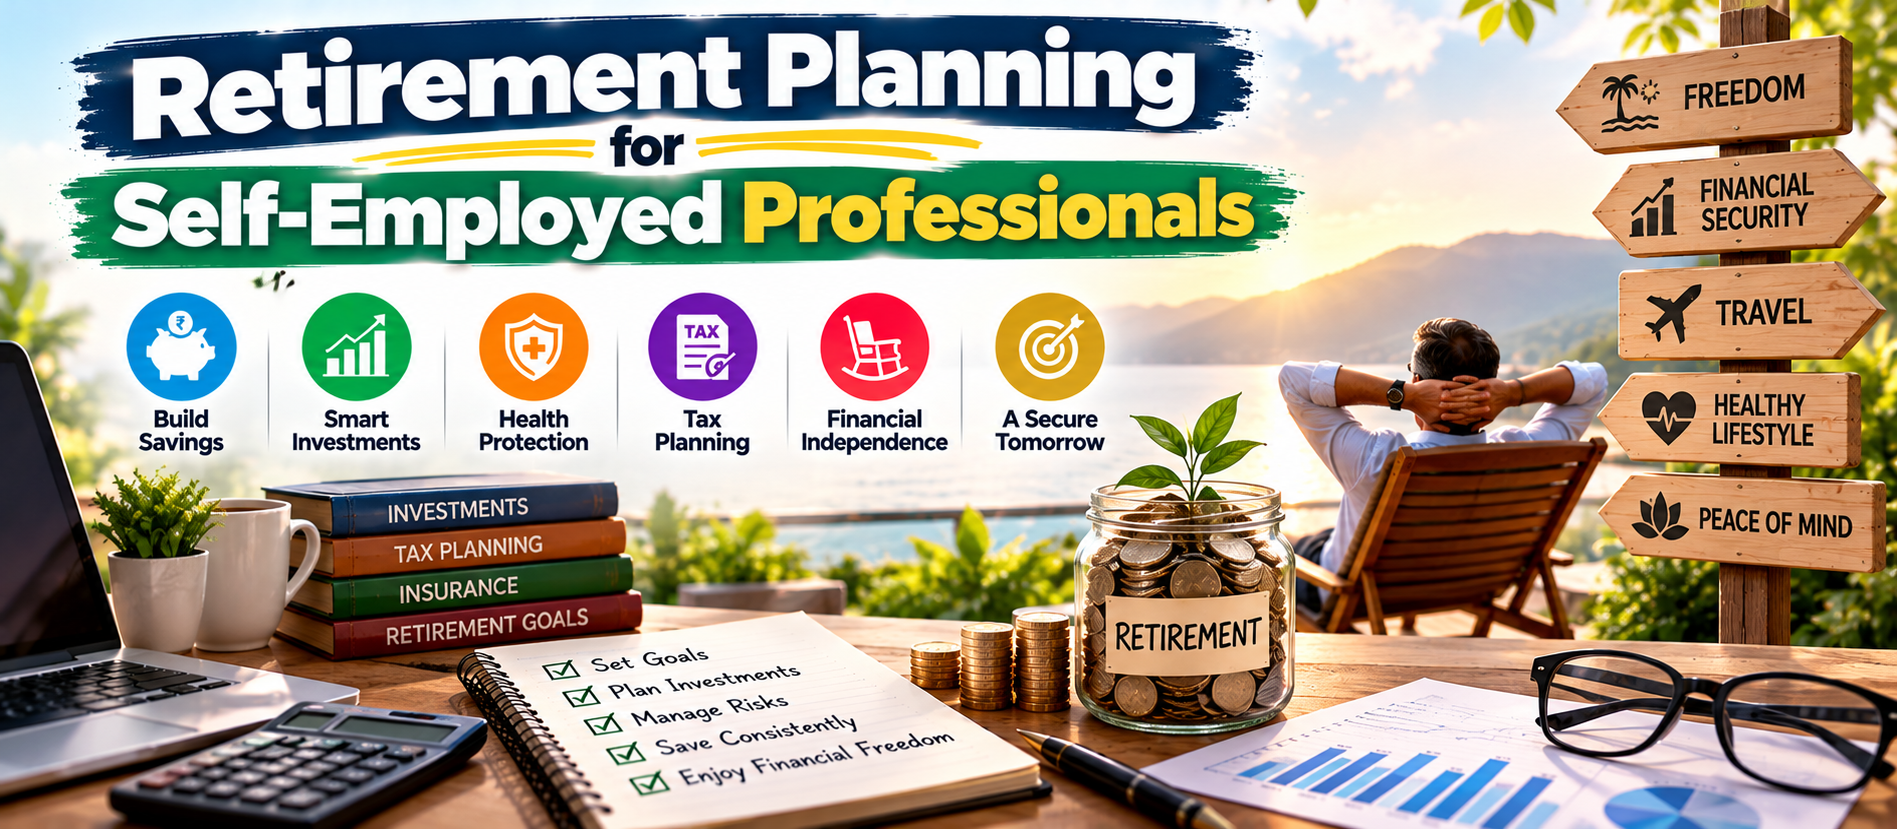
📋 Quick Summary
In this article:
Introduction: Your Business May Be Your Career, but It Should Not Be Your Only Retirement Plan
1. Understand Why Self-Employed Retirement Planning Is Different
2. Define What Retirement Means to You
3. Estimate How Much Money You May Need
4. Build a Financial Foundation Before Investing for Retirement
5. Create a Saving Rule for Irregular Income
Use a base contribution and a bonus contribution
6. Choose Retirement Investments That Match Your Time Horizon
Introduction: Your Business May Be Your Career, but It Should Not Be Your Only Retirement Plan
Self-employment offers freedom. You can choose clients, build a business, set your schedule and grow income through your own effort. But it also comes with a challenge: retirement benefits may not arrive automatically.
A salaried employee may receive provident fund contributions, employer-sponsored retirement benefits or a regular pension arrangement. A freelancer, consultant, doctor, lawyer, designer, shop owner or small-business professional often has to create a retirement plan independently. Income may rise in one month and fall in the next. Money may also be needed for staff, equipment, rent, taxes or an unexpected business expense.
These pressures can make retirement saving feel optional. It is easy to say, “I will invest more when business improves.” But delaying for years can make the goal harder. Retirement planning works best when it becomes part of your financial system, just like paying taxes or maintaining an emergency fund.
This guide explains how self-employed professionals in India can plan for retirement. It covers retirement goals, income fluctuations, investment choices, the National Pension System (NPS), insurance, tax considerations and the shift from earning income to using savings in later life.
1. Understand Why Self-Employed Retirement Planning Is Different
Self-employed professionals face many of the same retirement questions as other investors, but their starting point can be different.
- No automatic employer contribution: You may not have an employer adding money to a retirement account each month.
- Irregular income: Client payments, seasonal demand and business cycles can make monthly cash flow unpredictable.
- Business and personal money can overlap: Using the same account for household and business expenses makes it harder to know how much you can safely invest.
- Business assets may feel like retirement savings: A shop, clinic, agency or consultancy may have value, but it may not produce enough cash when you retire or may be difficult to sell.
- Protection may be limited: You may need to arrange your own health insurance, disability protection and life cover for dependants.
- Retirement date may be uncertain: Some professionals want to stop working at a specific age. Others plan to reduce their workload gradually.
The solution is not necessarily to save the same amount every month. It is to build a system that works in both strong and weak business periods. Your plan should protect day-to-day stability while keeping long-term retirement saving on track.
2. Define What Retirement Means to You
Retirement does not have to mean stopping all work on one birthday. You may want to stop full-time work, accept only selected clients, teach, consult occasionally or spend more time with family. Your goal determines how much money you need.
Start by answering four questions:
- At what age would you like to reduce or stop paid work?
- Will you live in the same city, move to a smaller town or divide time between places?
- What lifestyle costs do you expect, including housing, food, transport, travel and hobbies?
- Will anyone depend on you financially, and do you expect to support children, a partner or older relatives?
Also consider health care, home maintenance, inflation and the possibility of living longer than expected. A retirement plan should not assume that expenses will stop simply because you stop working.
Write a short retirement vision. For example: “I want to reduce client work at 60, keep my home, travel locally and have enough income to cover household costs without depending on my business.” A clear goal makes the numbers more useful.
3. Estimate How Much Money You May Need
Begin with your current household spending, not your current business revenue. Business turnover is not the same as personal income. Your retirement estimate should focus on the cost of the life you want to maintain.
List monthly expenses under practical headings:
- Housing, maintenance and utilities
- Food, clothing and household supplies
- Health insurance, medical care and medicines
- Transport and vehicle costs
- Family support and education commitments
- Travel, hobbies and social activities
- Taxes, professional fees and other recurring costs
- A reserve for repairs and unexpected expenses
Then remove expenses that may end before retirement, such as business costs or a child’s education fees, and add expenses that may rise, such as health care or leisure spending. Do not assume your home will be entirely cost-free just because a mortgage is paid off.
Account for inflation
Inflation reduces the purchasing power of money. A monthly budget that feels comfortable today may be much more expensive in 15 or 25 years. For planning, test several inflation assumptions rather than relying on one forecast.
For example, if a household spends ₹50,000 per month today, that is ₹6 lakh per year. If prices rise by an illustrative 6% each year, the same basket of goods and services would cost about ₹1.20 lakh per month after 15 years. This is a planning illustration, not a prediction of future inflation.
Use a retirement calculator or spreadsheet to estimate future spending, expected investment growth and the number of years your savings may need to support you. Test lower-return and higher-expense scenarios too. A plan that works only under optimistic assumptions is fragile.
4. Build a Financial Foundation Before Investing for Retirement
Retirement saving is important, but it should not make your current finances unstable. Self-employed professionals often need a larger cash buffer because business income can be uneven.
Create two emergency reserves
Keep personal and business reserves separate. A personal emergency fund can help cover household costs during illness, a client loss or a temporary income drop. A business reserve can cover rent, payroll, equipment repairs, taxes and other operating needs.
The right amount depends on how predictable your income is, how many dependants you support and how quickly you could replace lost work. Some professionals may need several months of essential expenses, while those with highly variable income may choose a larger buffer. Keep emergency money in accessible, lower-risk places rather than relying on shares or long-term retirement products.
Manage expensive debt
High-interest debt can undermine retirement saving. List your loans, interest rates and required payments. Make a plan to reduce costly debt while continuing a realistic level of long-term saving where possible. Avoid investing money that you may soon need to repay a high-interest loan.
Protect your ability to earn
Your future income depends partly on your health and ability to work. Review health insurance, personal accident or disability protection where available, and life insurance if others rely on your income. Read policy exclusions, waiting periods and limits. Insurance is designed to manage risk; it should not be confused with a complete retirement investment plan.
5. Create a Saving Rule for Irregular Income
A fixed monthly contribution can be difficult when payments arrive at different times. Instead of giving up on consistency, design a rule that adapts to your cash flow.
One approach is to set a target percentage of personal income after business expenses and tax provisions. When a client pays you, first set aside money for taxes and near-term business commitments. Then fund your emergency reserves if they are below target. Transfer the planned retirement contribution to a separate investment account.
For example, you might decide that a chosen share of your personal take-home income will go toward long-term investing. In a strong month, you may contribute more. In a weak month, you may make a smaller contribution while protecting essential expenses. The percentage should reflect your circumstances rather than a universal rule.
Use a base contribution and a bonus contribution
Set a minimum contribution you can maintain in ordinary months. Then decide in advance what to do with unusually strong months. You could direct part of the extra income to retirement, debt repayment or your emergency reserve. This prevents a good business month from turning into unplanned spending.
Review the plan every quarter. If your income rises and your expenses remain stable, increase the contribution. If income falls, adjust temporarily rather than abandoning the plan altogether. The aim is to create a repeatable habit that survives changing business conditions.
6. Choose Retirement Investments That Match Your Time Horizon
Retirement planning usually involves more than one asset class. Different investments serve different roles. The right mix depends on your age, goals, financial responsibilities, ability to tolerate losses and the time until you need the money.
Equity investments
Equities can provide long-term growth, but their prices can fall sharply and may remain weak for extended periods. Diversified equity mutual funds or index funds may be considered by investors who understand market risk and can remain invested through volatility. Do not invest retirement money in a concentrated set of stocks simply because a business is doing well.
Debt and fixed-income investments
Debt funds, deposits and government-backed savings products can play a role in stability or planned spending, depending on their features and risks. They are not all equivalent. Check credit risk, interest-rate risk, liquidity, maturity and tax treatment. A product that offers a higher rate may also involve higher risk or a lock-in period.
National Pension System (NPS)
The National Pension System is a regulated retirement savings framework in India. Eligible individuals, including self-employed professionals, can participate under the applicable NPS model. Contributions are invested through pension funds in permitted asset classes, and the value can rise or fall with investment performance. NPS has specific account, withdrawal and exit rules, so read the current official guidance before joining.
Official information is available from the PFRDA NPS All Citizen Model page. Review eligibility, investment choices, charges, tax treatment and exit conditions. Do not choose NPS only because of a possible tax benefit; also consider liquidity and whether the account fits your retirement needs.
Public Provident Fund and other long-term options
Some self-employed investors may consider the Public Provident Fund (PPF) or other eligible long-term savings products as part of a broader plan. Each option has its own contribution limits, lock-in rules, interest or return structure and tax treatment. Verify the current terms before investing.
Do not depend on your business alone
Your business may be a valuable asset, but its future sale price and income are uncertain. Customer relationships, technology, competition, health and market conditions can change its value. Retirement security is stronger when personal investments are not entirely tied to the same business that provides your current income.
7. Diversify and Review Your Asset Allocation
Asset allocation is the mix of assets in your portfolio, such as equity, debt and cash. Diversification spreads money across investments so that your future does not depend on one company, industry or asset class.
A younger professional with many years before retirement may be able to accept more short-term volatility in pursuit of long-term growth. Someone close to retirement may need a larger share of stable, accessible assets to cover near-term expenses. These are general principles, not fixed rules. Your actual mix should reflect your situation and risk capacity.
Review your allocation at least periodically and after major life changes. If equity markets rise sharply, equities may become a larger share of your portfolio than planned. Rebalancing can bring the portfolio back toward its intended risk level. Consider taxes, transaction costs and the features of each investment before making changes.
Do not confuse diversification with owning many products. Ten funds that hold nearly the same companies may provide less diversification than you expect. Look at the underlying investments and understand what each holding contributes to the plan.
8. Understand NPS and Tax Rules Before You Contribute
Tax rules can affect the value of retirement contributions, but the rules depend on the tax regime, the type of contribution, eligibility and the law in force for the relevant year. Avoid making a decision based on an old blog post or a tax deduction alone.
Under the Indian tax provisions currently described by the Income Tax Department, eligible self-employed individuals may claim a deduction for qualifying NPS contributions under Section 80CCD(1), subject to applicable limits. An additional deduction of up to ₹50,000 under Section 80CCD(1B) may be available for qualifying contributions, subject to the rules. The availability of deductions can differ under the old and new tax regimes, and other conditions apply.
Read the current official guidance on the Income Tax Department website and the relevant deductions information page. Confirm the rules for your specific assessment year and regime with a qualified tax professional. Do not assume every deduction is available to every taxpayer.
Keep contribution receipts, account statements, business records and tax filings organised. Good records make annual planning easier and help you understand the real after-tax cost of saving.
9. Plan for Health Care and Family Responsibilities
Health costs can be a major retirement expense. As you get older, you may need more regular check-ups, medicines or specialist care. Health insurance can help with covered expenses, but it may not pay for every treatment or every type of care.
Review policy limits, exclusions, waiting periods, co-payments, room restrictions and renewal terms. If you have dependants, consider how their needs may change as you approach retirement. Avoid assuming that your family will always be able to provide financial support or caregiving.
💡 Key Insight
Life insurance may be important while others depend on your income or when you have significant liabilities. As your financial responsibilities decline, review whether your existing cover still matches your needs. Do not cancel or replace a policy without understanding the consequences.
Also consider legal and practical matters. Keep nominee details current, maintain a record of accounts and policies, and make sure a trusted family member knows where important documents are stored. Estate planning and a valid will can help reduce confusion later.
10. Turn Your Retirement Savings Into Income
Saving is only half the plan. You also need to decide how to use your money after you reduce or stop work. Retirement may last for decades, so withdrawing too much in the early years can leave you short later.
Start by estimating essential monthly expenses and separating them from discretionary spending. Essential costs may include food, housing, utilities, insurance and health care. Discretionary costs may include travel, hobbies and large purchases. This distinction can help you adjust spending if markets perform poorly.
⚠ Watch Out
Keep an appropriate reserve for near-term spending so you are not forced to sell volatile investments after a market fall. The amount depends on your overall plan, guaranteed income sources, health needs and comfort with risk. Avoid placing all retirement money in cash for decades, because inflation can erode its purchasing power.
Review how each investment can be accessed. NPS and other retirement products may have specific exit rules, withdrawal limits or annuity requirements. Deposits may have maturity dates or early withdrawal penalties. Understand these details before retirement, not when you urgently need the money.
Once retired, review spending and portfolio withdrawals at least annually. If markets fall or expenses rise, you may need to reduce discretionary spending or adjust withdrawals. A flexible plan can be more resilient than one that assumes the same spending and returns every year.
11. Example: A Self-Employed Consultant Builds a Retirement System
Consider a fictional consultant whose monthly income changes with client projects. Some months bring ₹1.5 lakh, while others bring much less. The consultant wants to retire from full-time work in about 20 years.
Instead of setting an unrealistic fixed amount, the consultant creates a simple system:
- Business payments first cover business expenses and a provision for tax.
- A separate personal account receives a planned amount for household spending.
- Personal and business emergency reserves are built and reviewed separately.
- A minimum retirement contribution is made in ordinary months when cash flow permits.
- Extra contributions are made after unusually strong months, once near-term obligations are covered.
- The retirement portfolio is diversified according to the consultant’s time horizon and risk tolerance.
- The plan is reviewed quarterly and updated when income, family needs or goals change.
The key is not a particular contribution amount. It is the system. The consultant avoids treating every good month as spending money and avoids investing cash that is needed for taxes or essential business costs. Over time, consistent contributions and periodic reviews can improve the chance of meeting the goal, although investment returns are never guaranteed.
12. A 90-Day Retirement Planning Checklist
Days 1–30: Understand your position
- Calculate average personal income after business costs and tax provisions.
- List household expenses, debts, insurance and dependants.
- Estimate current retirement spending and future needs.
- Separate personal and business accounts where practical.
- Check emergency reserves and expensive debt.
Days 31–60: Build the system
- Choose a realistic minimum retirement contribution and a rule for strong-income months.
- Compare eligible retirement products, including NPS and other suitable investments.
- Review asset allocation, liquidity, costs and tax implications.
- Check health, life and disability protection needs.
- Organise account records, nominees and important documents.
Days 61–90: Put the plan into action
- Start the planned contributions or adjust existing investments.
- Set a quarterly review date.
- Update the retirement estimate using cautious and optimistic assumptions.
- Document your plan for weak-income months.
- Seek qualified financial or tax advice for complex questions.
13. Common Retirement Planning Mistakes to Avoid
- Waiting for income to become predictable: Build a flexible system now rather than waiting for a perfect month.
- Mixing business and personal money: Unclear accounts make it difficult to know what you can safely invest.
- Counting the business as the entire retirement plan: Its future value and saleability are uncertain.
- Ignoring inflation: Future living costs may be much higher than today’s costs.
- Taking too much investment risk: High expected returns often come with greater uncertainty. Match risk to your time horizon and ability to absorb losses.
- Choosing products only for tax benefits: Consider fees, lock-ins, risk, withdrawal rules and the role each product plays.
- Underestimating health costs: Review insurance and build a plan for out-of-pocket expenses.
- Failing to review the plan: Business income, family responsibilities and investment values change over time.
- Assuming retirement income will last automatically: Plan withdrawal rates and review spending throughout retirement.
Frequently Asked Questions (FAQs)
How can self-employed professionals plan for retirement in India?
Estimate future expenses, maintain separate personal and business reserves, save regularly when cash flow allows, invest across suitable asset classes and plan how to access the money later. Review the plan as income and family needs change.
Can self-employed people invest in NPS?
Eligible Indian citizens can generally join the NPS All Citizen Model, subject to current eligibility and KYC requirements. Check PFRDA’s official information for the latest rules, investment choices, charges and exit conditions.
How much should a self-employed person save for retirement?
There is no single percentage suitable for everyone. The amount depends on age, current savings, expected retirement spending, years remaining, income stability, other assets and risk tolerance. Use a retirement calculator and test different assumptions.
What if my income changes every month?
Use a flexible contribution system. Set aside taxes and business costs first, maintain emergency reserves, and contribute a realistic minimum in ordinary months. Add more during strong months when obligations are covered.
Should I rely on selling my business to fund retirement?
A business sale may help, but the sale price, timing and buyer demand are uncertain. Build personal retirement investments alongside your business where possible, and treat any future sale as one potential source rather than the only plan.
Is NPS the only retirement option for self-employed professionals?
No. NPS is one option. Depending on eligibility and goals, investors may also consider diversified mutual funds, deposits, PPF and other suitable products. Each has different risks, tax rules, liquidity and withdrawal conditions.
Are retirement contributions tax-deductible?
Some eligible contributions may qualify for deductions under applicable Indian tax rules. Availability depends on the product, taxpayer eligibility, assessment year and chosen tax regime. Confirm current rules with official sources or a qualified tax professional.
When should I start retirement planning?
Start as soon as you can build a sustainable contribution without neglecting essential expenses or high-priority financial obligations. Starting earlier gives savings more time to grow, but it is still useful to begin later with a realistic plan.
How often should I review my retirement plan?
Review it at least once a year and after major changes, such as a new family responsibility, a major business shift, a property purchase or a change in retirement timing. Quarterly cash-flow reviews can help self-employed professionals adjust contributions.
What is the biggest retirement planning risk for self-employed people?
One major risk is relying entirely on future business income or a future business sale. Other risks include irregular cash flow, insufficient savings, inflation, health costs and investment losses. A diversified plan can help reduce dependence on one source.
Conclusion: Build a Retirement Plan That Can Handle Real Life
Self-employed professionals do not have to follow the same retirement path as salaried employees. They do, however, need a clear system. Start by estimating the life you want, understanding your current finances and separating business cash from personal savings. Protect yourself against emergencies and major health risks.
Then choose suitable investments, contribute consistently when cash flow allows and review the plan regularly. Consider NPS and other options only after understanding their risks, costs, tax rules and withdrawal conditions. Do not assume your business will automatically fund your retirement.
The goal is not to predict every future expense or market movement. It is to build a flexible plan that can adapt when income changes, costs rise or life takes an unexpected turn.
At Digiifrog, we aim to make financial topics easier to understand and act on. Start with one practical step today, then improve your plan as your circumstances evolve.
Editorial disclaimer: This article is for general educational purposes only. It is not personalised investment, legal or tax advice. Investment values can fall, and returns are not guaranteed. Product rules and tax provisions may change; verify current information with official sources and qualified professionals.
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.
Comments (0)
Log in to leave a comment.