📋 Quick Summary
In this article:
Quick Answer: Should You Sell or Rent Your House?
Why This Decision Is More Complicated Than It Looks
Step 1: Calculate What Your House Is Worth Today
Step 2: Calculate Your Current Equity
Step 3: Estimate How Much Cash You Would Actually Receive From a Sale
Step 4: Estimate Realistic Monthly Rent
Step 5: Calculate Gross Rental Yield
Step 6: Calculate Net Rental Cash Flow
Maintenance Can Change the Answer
Step 7: Consider Your Mortgage
Cash Flow Is Not the Same as Total Return
💡 Key Insight
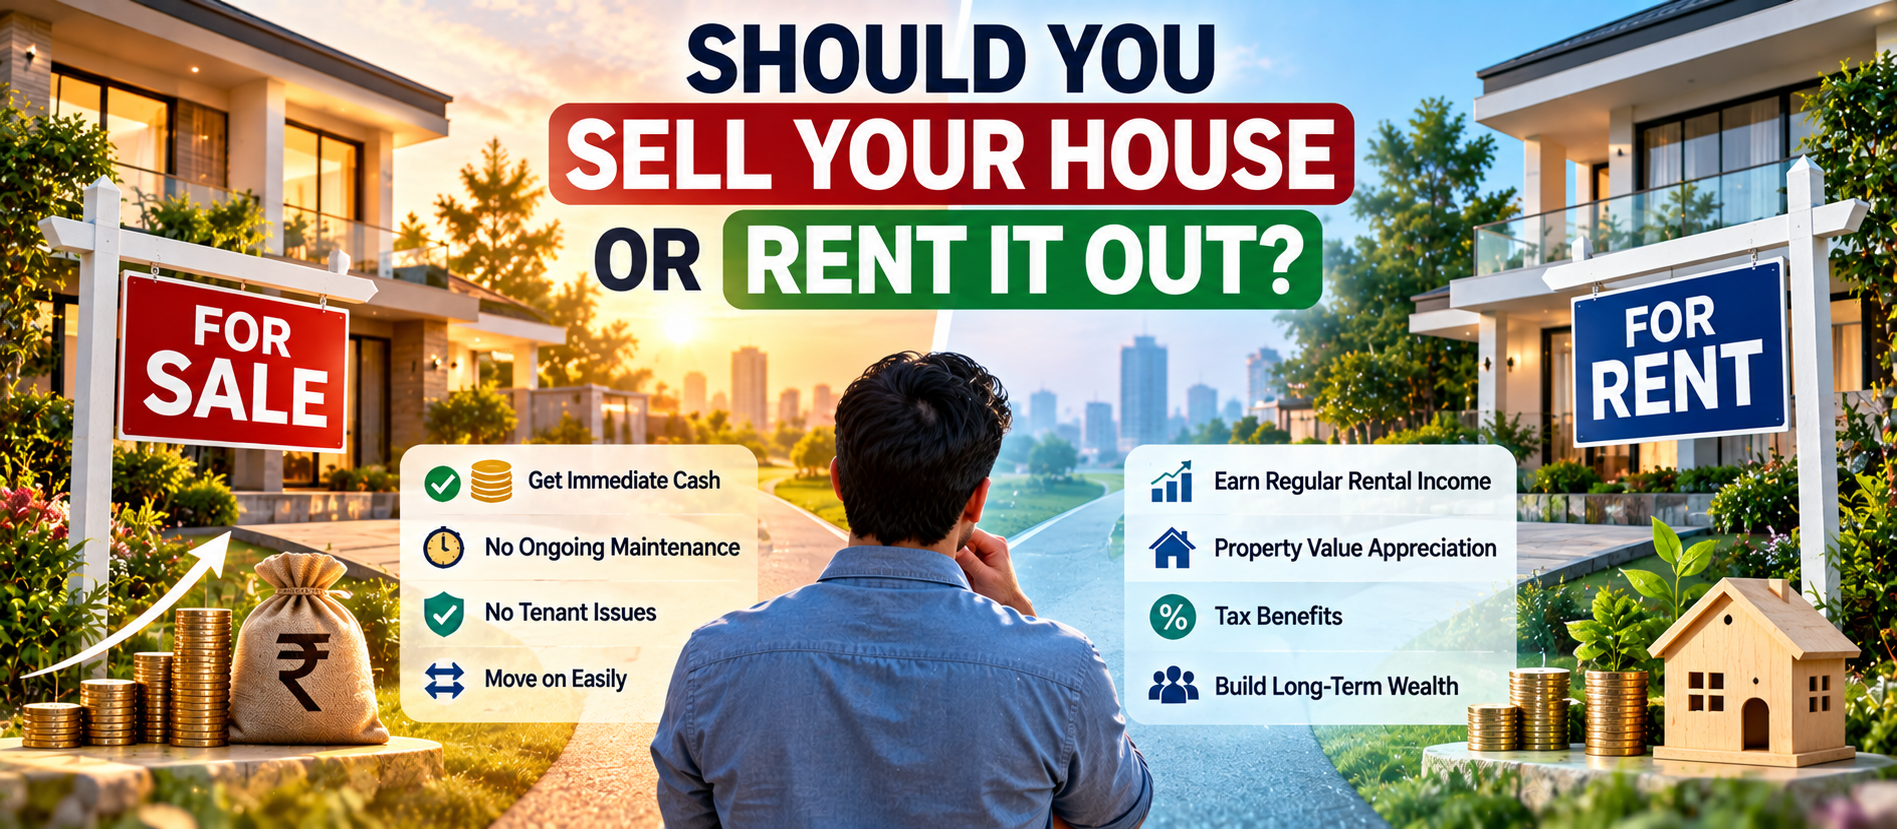
Should you sell your house or rent it out? This is one of the most important decisions a homeowner can make. Selling can unlock a large amount of cash and remove the work of owning the property. Renting can create recurring income and allow you to keep the property as a long-term investment.
There is no universal answer. The better choice depends on your property value, expected rent, mortgage balance, maintenance costs, local demand, taxes, future plans, and tolerance for landlord responsibilities.
The right decision is not simply about asking, “Will the house go up in value?” It is about comparing the total financial and practical outcome of both choices.
This guide explains how to make that comparison using simple numbers. It also covers cash flow, vacancy, property management, taxes, market conditions, risk, and the situations where selling or renting may make more sense.
Quick Answer: Should You Sell or Rent Your House?
Rent your house if it can generate healthy long-term cash flow after mortgage payments, maintenance, vacancy, insurance, taxes, management, and other costs, and if you are comfortable remaining a property owner.
Sell your house if the property produces weak or negative cash flow, you need a large amount of capital, you want to reduce financial risk, or you no longer want the responsibilities of being a landlord.
In many cases, the best answer becomes clear when you compare two numbers:
- The net cash and investment return from selling.
- The expected net annual return from keeping and renting.
Do not compare rent with the mortgage payment alone. A rental property has many costs that can reduce the income you actually keep.
Why This Decision Is More Complicated Than It Looks
A house is both an asset and a responsibility. When you sell, you convert part or all of its value into liquid capital. When you rent it, you keep ownership and potentially create an income-producing asset.
That creates two different financial paths.
| Decision Main Benefit Main Risk | ||
| Sell | Immediate access to capital | You give up future rental income and future appreciation |
| Rent | Recurring income plus potential appreciation | Vacancy, repairs, tenant issues, and ongoing ownership costs |
The decision should therefore consider both money today and wealth over time.
Step 1: Calculate What Your House Is Worth Today
Start with a realistic market value. Do not rely only on the price you paid for the property. Your purchase price may be irrelevant to what a buyer or tenant is willing to pay today.
Research recent comparable properties in the same neighborhood. Look at similar homes by location, size, age, condition, amenities, parking, access, and building quality.
A professional valuation or advice from a qualified local real estate professional can also help. A realistic value matters because it becomes the starting point for both the selling and rental calculations.
Step 2: Calculate Your Current Equity
Your equity is broadly the difference between the property's market value and the outstanding loan balance.
Estimated Equity = Current Property Value − Outstanding Mortgage or Loan
For example, suppose your house is worth $400,000 and your outstanding mortgage is $220,000. Your gross equity is approximately $180,000 before selling costs and taxes.
The same method can be applied using your local currency.
If you sell, some of that equity may become available as cash after commissions, closing costs, taxes, loan repayment, and other transaction expenses.
Step 3: Estimate How Much Cash You Would Actually Receive From a Sale
The sale price is not the same as your final cash proceeds.
Use this simple framework:
Net Sale Proceeds = Sale Price − Selling Costs − Loan Payoff − Applicable Taxes and Other Costs
Selling costs can include agent commissions, legal or professional fees, transfer-related charges, repairs made before listing, staging, advertising, and other transaction expenses. Tax treatment varies significantly by country and individual circumstances.
This is why you should calculate the amount you would actually have available after the transaction rather than focusing on the headline selling price.
Step 4: Estimate Realistic Monthly Rent
If you are considering renting, research comparable rental properties in your area.
Look at homes with similar:
- Location
- Floor area
- Number of bedrooms
- Parking
- Furnishing
- Building quality
- Security
- Transport access
- Schools and services nearby
Do not assume that the rent you want is the rent the market will support. A property that remains vacant for months because the asking rent is too high may produce less income than a property rented at a realistic price.
Step 5: Calculate Gross Rental Yield
A simple first calculation is gross rental yield.
Gross Rental Yield = Annual Rent ÷ Property Value × 100
For example, if a property is worth $300,000 and produces $18,000 in annual rent:
Gross Rental Yield = $18,000 ÷ $300,000 × 100 = 6%
This is useful for comparison, but it is not your true return. It ignores vacancy, repairs, insurance, taxes, management, financing, and other expenses.
Step 6: Calculate Net Rental Cash Flow
This is one of the most important calculations in the entire decision.
Net Rental Cash Flow = Rental Income − Operating Expenses − Debt Payments
Potential expenses include:
- Property taxes or local property charges
- Insurance
- Repairs and maintenance
- Property management
- Advertising and tenant acquisition
- Utilities paid by the owner
- Association or service charges
- Legal and accounting costs
- Licensing or compliance costs
- Vacancy losses
- Major replacement reserves
- Mortgage interest and principal payments
Rental-property guidance from the U.S. Internal Revenue Service illustrates how many categories of costs can arise from rental ownership, including maintenance, insurance, taxes, management fees, repairs, utilities, and interest. Exact deductions and tax treatment vary by jurisdiction, so local professional advice is important.
Why Vacancy Matters
A common mistake is to assume that rent will be collected every month of every year.
Real properties can remain vacant between tenants. A tenant may leave unexpectedly. You may need time to repair or repaint the property. Local demand can also change.
For planning purposes, include a vacancy reserve rather than assuming 100% occupancy.
For example, if your expected annual rent is $24,000, you should test the investment using a lower income figure as well. This makes your calculation more realistic and protects you against overly optimistic assumptions.
Maintenance Can Change the Answer
Rental income can look attractive until a major repair appears.
Roofs, plumbing systems, electrical equipment, appliances, air-conditioning systems, elevators, waterproofing, flooring, paint, and structural components can require expensive work.
You should create a maintenance reserve. Do not treat every month of positive cash flow as spendable income.
A good rental-property analysis separates:
- Routine maintenance: smaller repairs and regular upkeep.
- Capital replacements: expensive items that eventually need replacement.
- Emergency repairs: unexpected problems that cannot be postponed.
Homeownership guidance from the Consumer Financial Protection Bureau also emphasizes budgeting for inevitable maintenance and repairs because costs can range from relatively small amounts to major expenses.
Step 7: Consider Your Mortgage
Your mortgage can strongly influence the decision.
If you have a low-cost loan and the rent comfortably covers the property's costs, keeping the house may be attractive.
If the mortgage payment is high and rent does not cover your total ownership costs, renting may create negative cash flow.
However, negative monthly cash flow does not automatically mean renting is a bad decision. Part of a mortgage payment may reduce your loan balance and increase your equity. The key is to evaluate the complete return, not just the monthly cash movement.
Cash Flow Is Not the Same as Total Return
A rental property can create wealth through several channels:
- Rental cash flow
- Mortgage principal reduction
- Property appreciation
- Rental growth
- Tax benefits where legally available
- Value created through improvements
At the same time, it can lose value or generate losses through falling prices, high vacancies, major repairs, poor tenant selection, financing costs, and unexpected market changes.
Therefore, evaluate the property using a multi-year perspective.
When Selling May Be the Better Choice
1. You Need Capital for a Better Opportunity
If your house contains substantial equity but produces weak rental income, selling may allow you to redeploy the capital into another investment, business, debt reduction, or a different property.
Capital has an opportunity cost. Money locked inside a low-return property cannot be used elsewhere.
2. The Rental Cash Flow Is Weak
If realistic rent barely covers your expenses, the property may not justify the risk and effort.
Run the numbers using conservative assumptions. If the property remains unattractive after allowing for vacancy, repairs, management, taxes, and financing, selling deserves serious consideration.
3. You Do Not Want to Be a Landlord
Landlord work can include marketing the property, screening tenants, collecting rent, responding to problems, coordinating repairs, maintaining records, renewing agreements, and handling disputes.
You can hire a property manager, but management fees reduce your return.
Owning a rental property is an investment, but it is not always completely passive.
4. You Are Moving Far Away
Distance can make property management more difficult. A remote landlord may depend heavily on local contractors and property managers.
The Consumer Financial Protection Bureau has noted that long-distance landlord responsibilities can create challenges, particularly around finding tenants who will care for the property.
5. You Want Simplicity
Selling converts a physical asset into financial capital. That can simplify your finances and reduce exposure to property-specific risks.
This may be attractive if you are approaching retirement, changing careers, relocating, or simply want fewer responsibilities.
When Renting May Be the Better Choice
1. The Property Has Strong Rental Demand
A house near employment centers, universities, hospitals, transport hubs, schools, commercial areas, or major infrastructure may have a strong tenant pool.
Rental demand is usually driven by practical reasons. A beautiful property is not automatically a good rental investment if the local tenant base is small.
2. The Property Produces Healthy Net Cash Flow
If realistic rent covers operating costs and debt payments while leaving a reasonable margin, keeping the property can make sense.
3. You Expect Long-Term Appreciation
If the location has strong fundamentals, you may want to keep the property for future appreciation.
Do not rely on appreciation alone. Future price growth is uncertain. The investment should still make sense under conservative scenarios.
4. You Want Long-Term Rental Income
A well-managed rental property can create an income stream that may continue for many years.
Rental growth can also improve the economics over time if local demand and market conditions support higher rents.
CBRE's 2026 India residential outlook highlights continued structural demand and growing institutional interest in rental housing segments, while also noting that the rental market remains fragmented and compliance can affect investment.
5. You May Return to the Property
If you are relocating temporarily, renting may allow you to keep the home for future personal use.
This can be useful when you are uncertain about where you will live permanently.
Compare Selling and Renting With a Simple Decision Table
| Factor Selling Renting | ||
| Immediate cash | High | Low |
| Recurring income | None from the property | Potential rental income |
| Future appreciation | Property exposure ends | Retained |
| Tenant risk | None | Yes |
| Maintenance responsibility | Ends after sale | Continues |
| Liquidity | Higher | Lower |
| Management work | Low after closing | Ongoing unless outsourced |
| Market exposure | Reduced after sale | Continues |
Do Not Ignore Taxes
Taxes can change the result significantly.
When selling, you may face taxes or transaction charges depending on your jurisdiction, holding period, property type, ownership structure, and gain.
When renting, rental income may be taxable, but some jurisdictions allow specific deductions or allowances for qualifying expenses.
For example, U.S. tax rules provide for various rental-property expenses and depreciation rules, but these rules are specific to U.S. taxpayers. They should not be treated as universal tax advice.
If you are in India or another country, consult a qualified local tax professional before making a major decision. The tax outcome can differ substantially between selling a home and converting it into a rental property.
Think About Selling Costs Too
Another common mistake is to compare the property's full market value with rental income.
Suppose a property is worth $500,000. You cannot necessarily invest the full $500,000 if you sell. Transaction costs reduce the amount you receive.
Therefore, compare rental returns against the net sale proceeds, not just the property's headline value.
Calculate the Opportunity Cost of Keeping the House
Imagine selling the property would give you $250,000 after all major costs.
If you keep the property, that $250,000 remains invested in real estate.
Ask:
- What annual cash flow does the property generate?
- How much equity is being built?
- What appreciation is reasonably possible?
- What other investment opportunities could the $250,000 fund?
- What level of risk would those alternatives involve?
This is the opportunity-cost test. It prevents you from keeping a property simply because you already own it.
Use a Three-Scenario Rental Test
Instead of building one optimistic forecast, create three scenarios.
| Scenario Assumptions Purpose | ||
| Conservative | Higher vacancy, higher repairs, modest rent growth | Tests downside risk |
| Base | Normal occupancy and realistic expenses | Most likely planning case |
| Optimistic | Strong occupancy, rent growth, controlled costs | Shows potential upside |
If the property only works in the optimistic scenario, be careful.
If it remains acceptable in the conservative scenario, the investment may be more resilient.
Consider the Condition of the Property
A newer or well-maintained house may be easier to rent and may require fewer immediate repairs.
An older property can still be an excellent rental, but you need to budget for maintenance and future capital improvements.
Before renting, inspect:
- Roof and waterproofing
- Plumbing
- Electrical systems
- Heating or cooling systems
- Appliances
- Windows and doors
- Paint and flooring
- Security systems
- Water supply
- Structural issues
Fixing important problems before renting can protect the property's condition and improve tenant satisfaction.
Tenant Quality Matters More Than Maximum Rent
A common mistake is choosing a tenant based only on the highest rent offered.
A reliable tenant who pays on time and takes reasonable care of the property may be more valuable than a tenant who offers slightly higher rent but creates frequent problems.
Follow local laws when screening tenants. Use consistent criteria. Verify information where legally permitted. Use a clear written rental agreement.
Property Management: DIY or Professional?
You can manage the property yourself or hire a professional manager.
Self-Management
- Lower direct management cost
- More control
- More time required
- You handle tenant communication and maintenance coordination
Professional Management
- Less day-to-day involvement
- Local operational support
- Useful for remote owners
- Management fees reduce net income
Include management fees in your financial model even if you initially plan to manage the property yourself. This gives you a more realistic picture of the property's economics.
Technology Can Make Renting Easier
Modern rental management tools can simplify many tasks.
Useful systems include:
- Online rent collection
- Digital rental agreements
- Maintenance request systems
- Automated reminders
- Property accounting
- Tenant communication platforms
- Digital inspection records
- Online marketing and lead tracking
Technology does not eliminate landlord responsibility, but it can reduce repetitive work and improve record keeping.
What If You Plan to Buy Another Home?
If you are moving and buying another property, keeping the old house as a rental can affect your overall finances.
Consider your combined debt, cash reserves, new mortgage, rental income, insurance, maintenance, and ability to handle a vacancy.
Do not assume a lender will treat projected rental income in the same way you do. Financing rules differ by lender and jurisdiction.
What If You Are Moving for Work?
A temporary relocation is one situation where renting can be particularly useful.
If you expect to return in a few years, selling may create unnecessary transaction costs and remove an asset you still value.
If the relocation is permanent, the case for selling may become stronger, especially if the old property produces weak returns or is difficult to manage from a distance.
What If You Are Near Retirement?
Retirement changes the decision.
You may value predictable income, liquidity, lower debt, and lower management responsibilities more than maximum long-term appreciation.
A rental property can create income, but it can also produce irregular expenses. A large repair during retirement can be stressful.
Selling can create a large pool of capital that may be used to reduce debt, diversify investments, fund living expenses, or support other financial goals.
The best decision depends on your overall retirement plan rather than the property alone.
2026 Market Context: Why Local Conditions Matter
Real estate markets are not moving in exactly the same way everywhere. Local supply, employment, infrastructure, household income, financing costs, and buyer preferences all affect the relationship between home prices and rents.
In India, CBRE's 2026 residential outlook describes a market supported by underlying demand and highlights increasing institutional interest in rental housing segments such as student housing, co-living, senior living, and workforce accommodation. Its Q1 2026 market monitor also reported stable residential activity across key cities.
These broad trends do not mean every individual property is a good rental. Your micro-location matters more than a national headline. A house near a strong tenant demand center may perform very differently from a similar house in a low-demand area.
Ask These 12 Questions Before You Decide
- What is my realistic current property value?
- How much mortgage or debt remains?
- How much cash would I receive after selling costs?
- What monthly rent can I realistically achieve?
- What will my annual operating expenses be?
- How much should I reserve for vacancy?
- What maintenance and capital repairs could arise?
- What are the applicable taxes under each option?
- Would I manage the property myself or hire a professional?
- How strong is long-term tenant demand in the location?
- What could I do with the money if I sold?
- Which choice better supports my personal goals for the next five to ten years?
A Simple Sell-or-Rent Scorecard
Give each factor a score from 1 to 5.
| Factor Score 1 Score 5 | ||
| Rental demand | Weak | Very strong |
| Net rental cash flow | Negative | Strongly positive |
| Property condition | Major repairs needed | Excellent |
| Management convenience | Difficult | Easy |
| Long-term location outlook | Uncertain | Strong |
| Liquidity need | Very high | Very low |
| Personal desire to be a landlord | Very low | Very high |
A high rental score suggests keeping and renting deserves deeper analysis. A high need for liquidity, low rental demand, and poor cash flow can point toward selling.
Common Mistakes Homeowners Make
Mistake 1: Comparing Rent With the Mortgage Only
Mortgage payment is only one part of the cost. Include all relevant operating expenses.
Mistake 2: Assuming 100% Occupancy
Vacancy happens. Build a realistic reserve.
Mistake 3: Ignoring Major Repairs
Small monthly profits can disappear after one large repair.
Mistake 4: Assuming Property Prices Always Rise
Real estate markets can decline or remain flat. Use conservative appreciation assumptions.
Mistake 5: Ignoring Your Time
Your time has value. A rental that requires constant attention may not be worth the effort.
Mistake 6: Forgetting Taxes
Tax rules can affect both selling proceeds and rental income.
Mistake 7: Holding a Property Only Because You Are Emotionally Attached
Emotional value matters, but investment decisions should also be based on financial reality.
Sell or Rent: A Practical Rule of Thumb
Consider renting when:
- Rental demand is strong.
- Net cash flow is healthy after realistic expenses.
- You have adequate emergency reserves.
- You can manage the property effectively.
- You want long-term exposure to the property market.
- You do not need the sale proceeds immediately.
Consider selling when:
- Net rental cash flow is weak or negative.
- You need liquidity.
- The property requires major investment.
- You do not want landlord responsibilities.
- Tenant demand is weak.
- You have a stronger use for the capital.
- Holding the property creates too much financial concentration or risk.
Frequently Asked Questions
Is it better to sell a house or rent it out?
Neither is automatically better. Renting may be better when the property has strong demand and healthy net cash flow. Selling may be better when you need liquidity, want to reduce risk, or the rental economics are weak.
How do I know if my house is a good rental?
Estimate realistic rent, subtract vacancy, maintenance, insurance, taxes, management, financing, and other costs, then compare the resulting return with the value of the property and the net proceeds you could receive from selling.
Should I rent my house if I still have a mortgage?
Possibly. A mortgage does not automatically prevent renting. The important question is whether the rental income and expected total return justify the ownership costs and risks. Check your loan documents and local rules before converting the property to a rental.
Can rental income make a property passive income?
Rental property can produce recurring income, but it is not always completely passive. Tenant communication, maintenance, vacancies, compliance, and financial management still require work unless you outsource them.
Should I sell a house that has appreciated significantly?
Not necessarily. Appreciation alone does not determine the best decision. Compare the after-tax sale proceeds with the expected future rental income, appreciation, costs, risk, and alternative uses of the capital.
What is more important: rental yield or property appreciation?
Both matter. Rental yield measures income relative to property value, while appreciation measures potential capital growth. A strong investment usually balances income, growth, risk, and liquidity rather than relying on only one factor.
Should I hire a property manager?
A property manager can make rental ownership easier, especially when you live far away or have limited time. However, management fees reduce your net return. Include the fee in your calculations before deciding.
What if my house does not generate positive cash flow?
Do not immediately sell. First check whether the problem comes from temporary vacancy, unusually high financing costs, under-market rent, or avoidable operating expenses. Then compare the property with the alternatives available for your capital.
Final Decision Framework
The sell-or-rent decision should be treated like an investment decision, not an emotional choice.
Start with the property's current market value. Calculate your equity. Estimate the net cash you would receive from a sale. Then calculate realistic rental income and subtract every meaningful cost. Test the rental using conservative, base, and optimistic scenarios.
Next, consider taxes, financing, property condition, tenant demand, management workload, liquidity needs, and your personal plans.
Finally, ask the most important question:
“If I did not already own this property, would I choose to invest this amount of money in it today?”
If the answer is yes, renting may deserve serious consideration. If the answer is no, selling and redeploying the capital may be the more rational choice.
Conclusion
Deciding whether to sell your house or rent it out is not about finding a universal rule. It is about finding the option that gives you the strongest combination of financial return, flexibility, risk control, and personal convenience.
Renting can turn an existing home into an income-producing asset. It can also preserve future appreciation and provide a long-term source of rental income. But it comes with vacancy risk, maintenance, tenant management, taxes, compliance, and ongoing responsibility.
Selling can provide liquidity, simplify your finances, reduce property-specific risk, and give you capital for other goals. But it also ends your ownership of the asset and removes future rental income and potential appreciation.
The best decision comes from the numbers. Use realistic assumptions. Include the costs that are easy to forget. Stress-test your plan. Consider your time and personal goals. Then make the decision based on the future you want to build, not only the property you already own.
About Digiifrog
Digiifrog helps businesses build stronger digital visibility through practical digital marketing, content, SEO, AI search optimization, and online growth strategies. For more information, visit www.digiifrog.com.
Disclaimer: This article is for general educational and informational purposes only. Real estate, rental, lending, tax, landlord-tenant, and property laws vary by location. Financial and tax examples are illustrative and should not be treated as professional advice. Consult qualified local professionals before making a property sale or rental decision.
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.
Comments (0)
Log in to leave a comment.