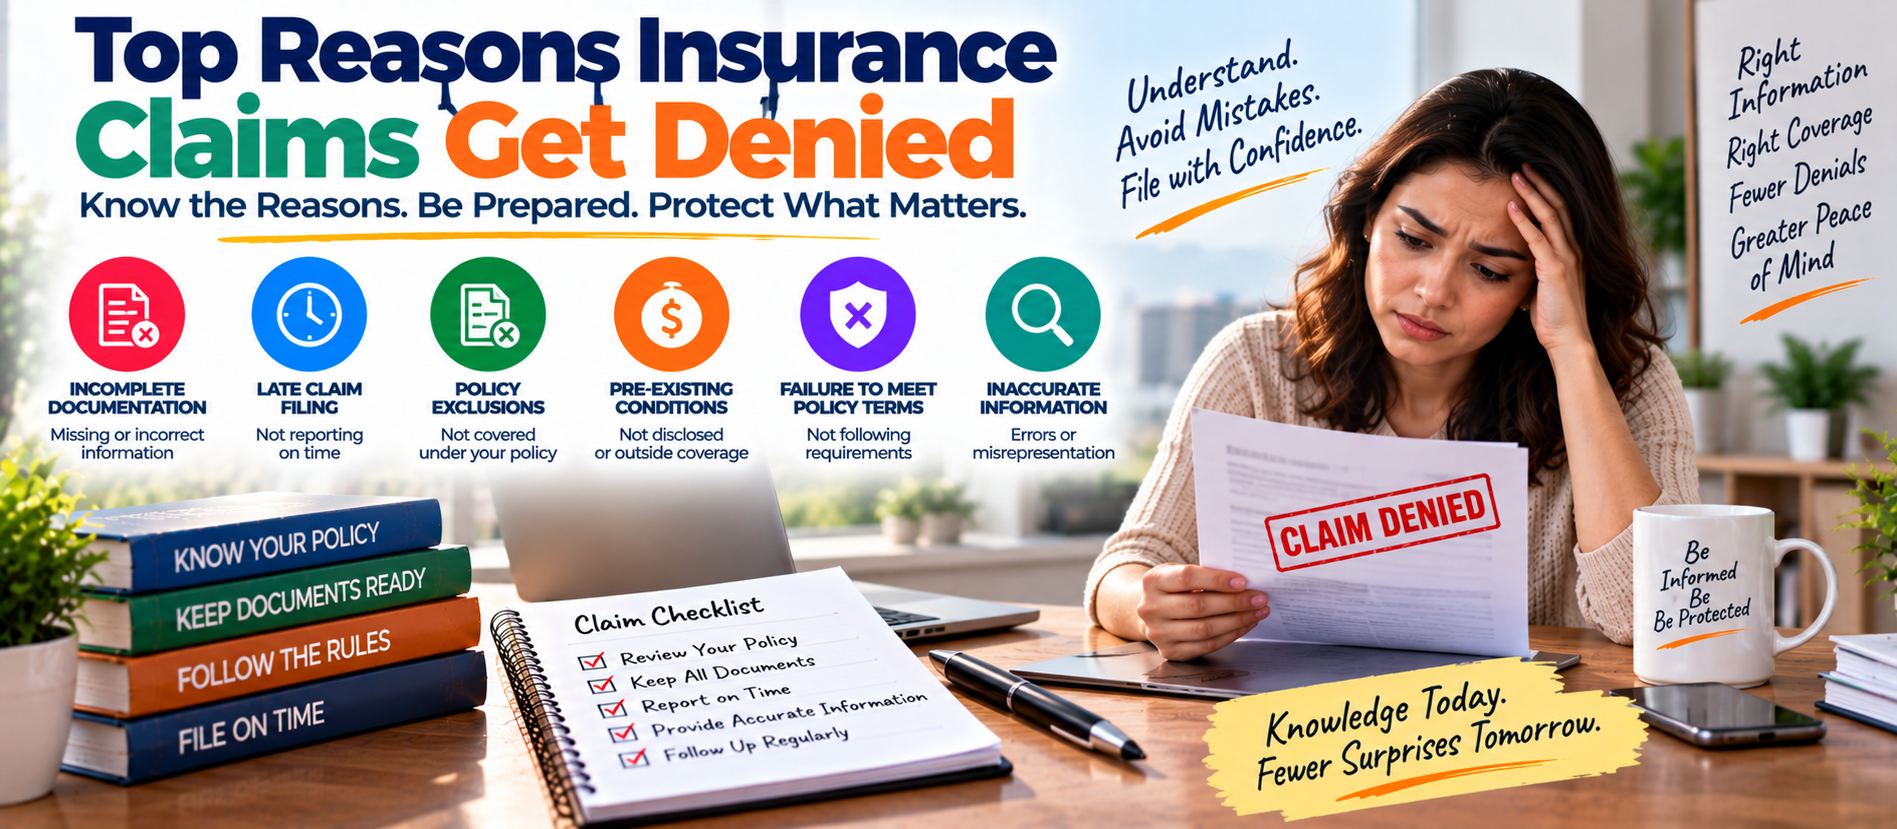
📋 Quick Summary
In this article:
Quick Answer: Why Do Insurance Claims Get Denied?
1. The Loss Is Not Covered by the Policy
2. A Specific Exclusion Applies
3. The Policy Was Not Active
4. The Claim Was Filed Too Late
5. Required Documents Are Missing
6. The Loss Happened Before Coverage Started
7. The Loss Was Already Known
8. Policy Limits Are Too Low
9. The Deductible Applies
10. The Policyholder Did Not Take Required Steps
11. The Claim Involves Normal Wear and Tear
An insurance claim can be denied when the loss, event, documentation, or circumstances do not meet the terms of the policy. A denial can be frustrating, especially when a policyholder believes they are fully covered. However, many claim problems can be reduced by understanding exclusions, policy limits, deadlines, documentation requirements, and the difference between covered and non-covered losses.
Insurance policies are contracts. The insurer reviews a claim against the specific terms of that contract. A premium payment alone does not guarantee that every loss will be covered.
💡 Key Insight
This guide explains the top reasons insurance claims get denied in simple language. It also explains how policyholders can reduce claim problems, what to do after a denial, and how to read important parts of an insurance policy.
Quick Answer: Why Do Insurance Claims Get Denied?
Insurance claims are commonly denied because the event is excluded, the policy does not provide enough coverage, the policy was inactive, required information is missing, the claim was filed too late, the loss resulted from negligence or another excluded circumstance, or the insurer determines that the reported loss does not meet the policy conditions.
Rules differ by insurance type, insurer, and location. Always review the actual policy wording before making assumptions about coverage.
1. The Loss Is Not Covered by the Policy
The most basic reason for a denial is that the policy does not cover the type of loss being claimed.
Insurance policies list covered events and may also contain exclusions. For example, a standard property policy may not automatically cover every natural disaster or maintenance-related problem.
Before filing a claim, review the coverage section and exclusions. If you are unsure, ask the insurer for clarification.
2. A Specific Exclusion Applies
Exclusions are one of the most important reasons insurance claims get denied. An exclusion removes certain events, situations, property, or losses from coverage.
Depending on the policy, exclusions may involve floods, earthquakes, intentional damage, normal wear and tear, certain business activities, risky behavior, pre-existing conditions, or other circumstances.
Never assume that a broad description such as “comprehensive” or “full coverage” means everything is covered.
3. The Policy Was Not Active
A claim may be denied if the policy was not active when the loss occurred.
This can happen because a premium was not paid, a policy expired, coverage was cancelled, or another condition ended the policy.
Keep your policy documents and payment records. Check renewal dates and make sure important policies do not lapse accidentally.
4. The Claim Was Filed Too Late
Insurance policies often require policyholders to report a loss within a specified period or as soon as reasonably possible.
Delays can make it harder to investigate a claim and may violate policy requirements.
After an accident, property loss, theft, medical event, or other potentially insured event, notify the insurer promptly and follow the reporting instructions.
5. Required Documents Are Missing
Insurance claims often require evidence.
Depending on the claim, the insurer may request:
- Photos or videos of the damage.
- Receipts or proof of ownership.
- Police reports.
- Medical records.
- Repair estimates.
- Invoices and bills.
- Travel documents.
- Proof of loss.
Missing information can delay a claim or make it difficult to establish that the loss is covered.
6. The Loss Happened Before Coverage Started
Insurance generally protects against qualifying future events. It is not designed to insure a loss that has already happened.
For example, buying coverage after discovering damage does not normally make that existing damage a new covered event.
Always check the effective date before relying on a policy.
7. The Loss Was Already Known
Known or expected events can create serious coverage issues.
If a policyholder already knows about a problem before purchasing or changing coverage, the event may not qualify as an unexpected insured loss.
Provide accurate information during the application process. Withholding important facts can create claim complications.
8. Policy Limits Are Too Low
A policy may cover a type of loss but still not pay the entire amount because the applicable coverage limit has been reached.
For example, property, liability, medical, baggage, or business coverage may have maximum benefit amounts.
Review limits periodically, especially after buying expensive property, increasing business revenue, renovating a home, or taking on new financial responsibilities.
9. The Deductible Applies
A deductible is the amount the policyholder may need to pay toward a covered loss before the insurer pays the eligible amount.
A claim may appear to be denied when the actual situation is that the covered loss is below the deductible or the payable amount is reduced by the deductible.
Understand your deductibles before assuming that every claim will produce a payment.
10. The Policyholder Did Not Take Required Steps
Policies may require policyholders to take reasonable steps to prevent further damage after a loss.
For example, after certain property damage, a policyholder may need to take reasonable temporary measures to protect the property from additional damage.
Do not make unsafe repairs. Follow the insurer's instructions and keep receipts for reasonable emergency expenses when applicable.
11. The Claim Involves Normal Wear and Tear
Insurance is generally designed to cover unexpected insured events, not ordinary aging or maintenance.
Roof deterioration, old plumbing, worn appliances, gradual corrosion, and similar problems may not be covered as sudden insured losses, depending on the policy.
Regular maintenance can help prevent small problems from becoming larger and more expensive.
12. The Cause of Loss Is Excluded
Sometimes the damage itself looks like something that should be covered, but the underlying cause is excluded.
For example, water damage can have different causes. A sudden covered incident may be treated differently from long-term leakage or poor maintenance.
When reviewing a denial, ask the insurer to identify the specific policy provision and reason used to make the decision.
13. Incorrect or Incomplete Information Was Provided
Insurance applications and claim forms should contain accurate information.
Problems can arise when a policyholder gives incorrect details about property use, vehicle use, drivers, business activities, health information, travel plans, or other relevant facts.
Review forms carefully and correct mistakes as soon as possible.
14. The Claim Involves Fraud or Misrepresentation
False statements, fabricated losses, altered documents, or intentionally misleading information can result in serious consequences, including denial and possible legal action.
Submit only accurate information and genuine documents. If you do not know an exact detail, ask the insurer how it should be reported.
15. A Waiting Period Applies
Some insurance products have waiting periods before certain benefits become available.
This can be particularly important for health insurance, certain specialty coverage, and policies with specific benefit conditions.
Check when each benefit begins rather than assuming that the entire policy provides immediate protection.
16. The Claim Does Not Meet the Definition in the Policy
Insurance policies often define important terms such as accident, disability, covered illness, emergency, theft, or total loss.
A claim may be denied when the event does not meet the policy's specific definition.
This is why reading definitions and conditions is important, especially for specialized coverage.
17. The Property or Person Is Not Properly Covered
A policy may not cover property that was never listed, a vehicle that is not insured, or a person who is not an eligible insured under the policy.
Update insurance information when you buy a new vehicle, move, add household members, purchase valuable property, or make other significant changes.
18. The Loss Is Above a Special Coverage Limit
Some policies have special limits for categories such as jewelry, electronics, collectibles, cash, artwork, or other valuable property.
If you own high-value items, ask whether additional coverage or an endorsement is available.
19. The Required Authorization Was Not Obtained
Certain policies may require prior approval for specific services, providers, repairs, procedures, or treatments.
Failing to obtain required authorization can affect coverage.
Before planned treatment, repairs, or specialized services, check whether pre-approval is required.
20. The Policyholder Did Not Follow Claim Procedures
Every insurer may have a specific claim process. It can include reporting the incident, completing forms, providing documents, cooperating with an investigation, and meeting deadlines.
Following the process carefully can reduce avoidable problems.
How to Reduce the Risk of an Insurance Claim Denial
- Read the policy before you need it.
- Understand exclusions and coverage limits.
- Keep your policy active.
- Report losses promptly.
- Keep receipts and important records.
- Take photographs or videos when appropriate.
- Provide accurate information.
- Follow required claim procedures.
- Ask about authorization requirements.
- Review coverage after major life or business changes.
What to Do If Your Insurance Claim Is Denied
First, read the denial letter carefully. Identify the reason for the decision and the specific policy provision cited by the insurer.
Then collect supporting documents and compare them with the policy wording. If you believe the decision is incorrect, ask the insurer about its internal review or appeal process.
For significant disputes, consider getting advice from a licensed insurance professional, consumer protection authority, attorney, or other qualified adviser in your jurisdiction.
Keep a Strong Insurance Documentation File
Keep copies of:
- Current policies.
- Premium payment records.
- Receipts for valuable property.
- Photos and inventories.
- Inspection and maintenance records.
- Police or incident reports.
SEO, AEO, GEO, and AI Search Optimization
This article uses direct answers, clear headings, practical lists, and FAQs to support modern search experiences.
⚠ Watch Out
SEO targets phrases such as top reasons insurance claims get denied, why insurance claims are denied, insurance claim denial reasons, and how to avoid an insurance claim denial.
AEO answers common questions directly, including “Why was my insurance claim denied?” and “What should I do after an insurance claim denial?”
GEO matters because insurance laws, appeal rights, claim deadlines, coverage rules, and consumer protections vary by country and region.
AI Search optimization is supported through concise definitions, structured lists, question-based headings, and direct explanations.
Frequently Asked Questions
What is the most common reason an insurance claim is denied?
One common reason is that the loss is excluded or is not covered under the policy. Missing documents, late reporting, inactive coverage, and insufficient limits can also cause problems.
Can an insurance claim be denied because of missing documents?
Yes. Missing evidence can make it difficult for an insurer to verify the loss and determine coverage. Provide requested documents promptly.
Can I appeal a denied insurance claim?
Many insurance systems and policies provide some form of review or appeal process. The exact procedure and deadlines vary by insurer and jurisdiction.
Does a denied claim mean I receive no money?
Not always. A denial may be challenged or corrected if additional information shows that the claim meets the policy conditions. Review the denial reason carefully.
How can I avoid insurance claim problems?
Understand your coverage, keep the policy active, provide accurate information, report losses promptly, preserve evidence, and follow the insurer's claim procedures.
Final Thoughts
Insurance claims are often denied because the reported loss does not meet the policy's coverage, conditions, limits, or documentation requirements. Exclusions, late reporting, inactive policies, missing evidence, insufficient limits, waiting periods, and inaccurate information are among the major issues policyholders should understand.
The best way to reduce claim problems is to know your policy before a loss happens. Keep good records, review your coverage regularly, report incidents promptly, and ask questions when policy language is unclear.
If a claim is denied, do not rely only on a verbal explanation. Review the written decision, identify the policy provision involved, collect supporting evidence, and use the available review or appeal process when appropriate.
For more educational content about insurance, personal finance, business, technology, SEO, AEO, GEO, and AI Search optimization, visit www.digiifrog.com.
Disclaimer
This article is for general educational and informational purposes only and does not constitute insurance, financial, legal, medical, or professional advice. Insurance coverage, exclusions, claim procedures, deadlines, appeal rights, and regulations vary by insurer, policy, country, and jurisdiction. Always review the current policy wording and consult a licensed insurance professional or qualified adviser for guidance based on your specific circumstances.
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.

Comments (0)
Log in to leave a comment.