📋 Quick Summary
In this article:
Quick Answer: What Is a Credit Utilization Ratio?
How to Calculate Your Credit Utilization Ratio
Example 1: One credit card
Example 2: More than one credit card
Why Does Credit Utilization Matter?
1. It can affect your credit score
2. It can influence a lender’s view of your finances
3. It helps reveal spending patterns
4. It can matter when you apply for new credit
What Is a Good Credit Utilization Ratio?
Individual Utilization vs. Overall Utilization
Credit utilization ratio is a simple measure of how much of your available credit you are using. It can influence how lenders view your credit habits and may affect your credit score. Understanding this number can help you manage credit cards, plan repayments, and build a healthier credit profile.
This guide explains the meaning of credit utilization, how to calculate it, why it matters, and what you can do to keep it under control. It uses practical examples and includes points relevant to people checking their credit profile in India.
Quick Answer: What Is a Credit Utilization Ratio?
Your credit utilization ratio is the percentage of your available revolving credit that you are currently using. It is most commonly discussed in relation to credit cards. If your credit limit is ₹1,00,000 and your balance is ₹25,000, your utilization ratio is 25%.
A lower ratio generally signals that you are not relying heavily on your available credit. A high ratio may suggest that you are using a large share of your credit limit and could have less room to handle an unexpected expense. Credit bureaus and scoring models may consider utilization when assessing your credit profile.
Important: Credit utilization is only one part of a credit score. It does not guarantee loan approval or rejection, and there is no single percentage that guarantees a particular score.
How to Calculate Your Credit Utilization Ratio
The calculation is straightforward. Divide the balance being considered by the credit limit, then multiply the result by 100.
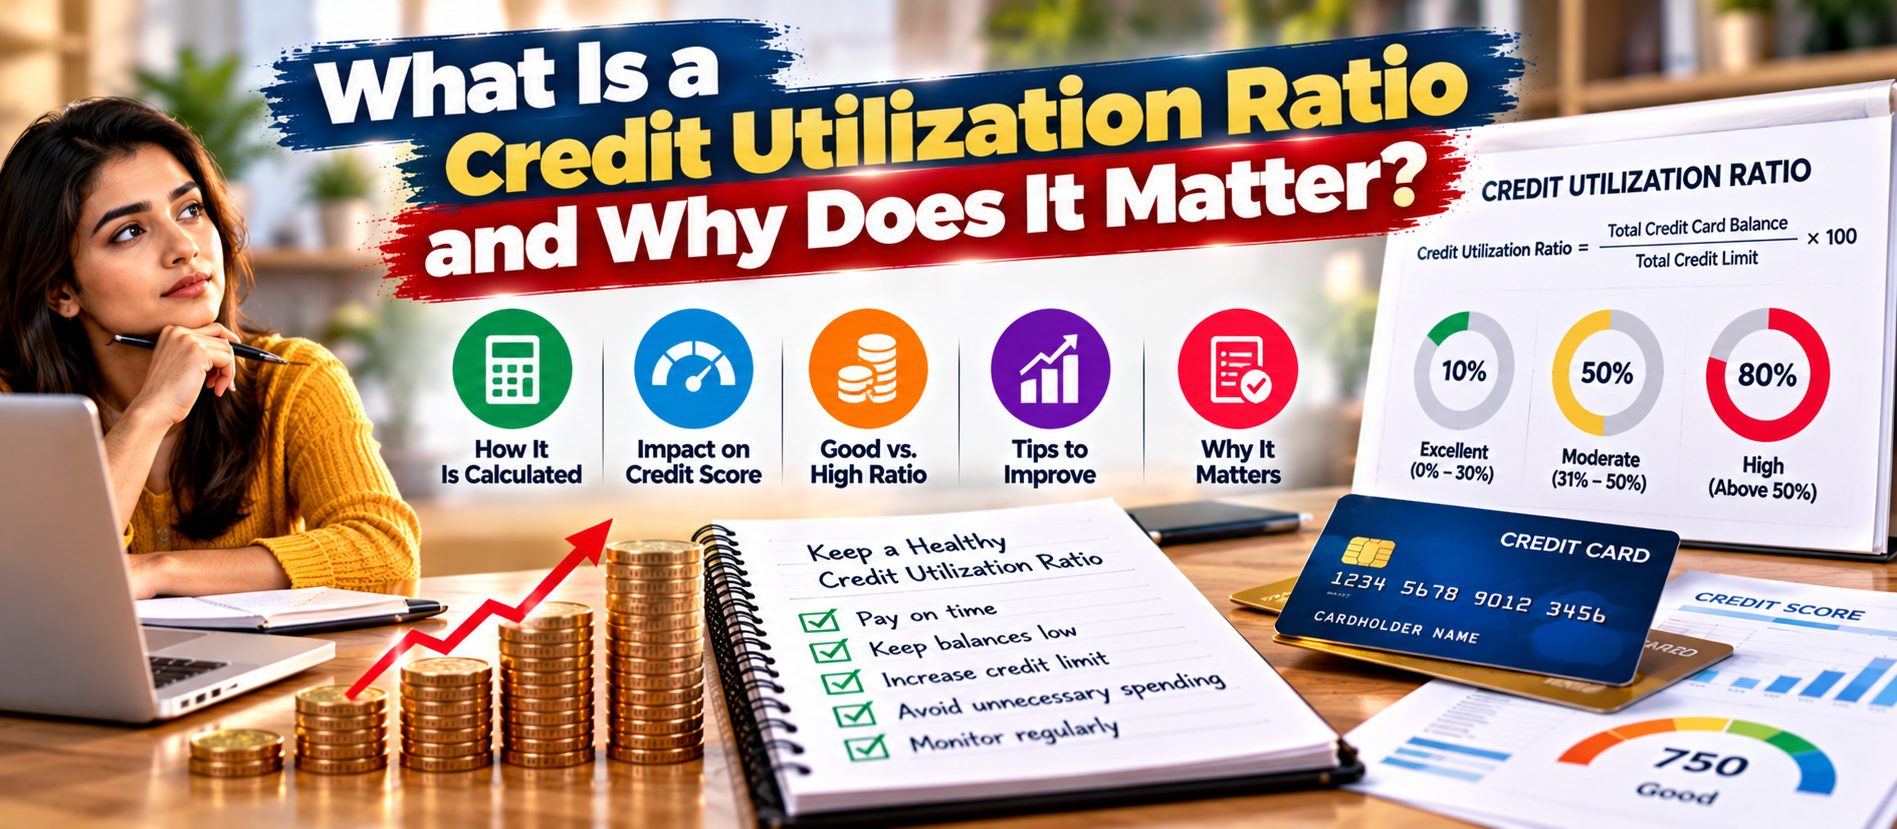
Formula: Credit utilization ratio = (Credit card balance ÷ Credit limit) × 100
Example 1: One credit card
Suppose your credit card has a limit of ₹80,000 and the balance reported for that card is ₹20,000.
- Balance: ₹20,000
- Credit limit: ₹80,000
- Calculation: ₹20,000 ÷ ₹80,000 × 100
- Utilization ratio: 25%
This means you are using one-quarter of that card's credit limit.
Example 2: More than one credit card
Imagine you have two cards. Card A has a limit of ₹1,00,000 and a balance of ₹15,000. Card B has a limit of ₹50,000 and a balance of ₹20,000.
- Total credit limits: ₹1,50,000
- Total balances: ₹35,000
- Overall utilization: ₹35,000 ÷ ₹1,50,000 × 100
- Overall utilization ratio: approximately 23.3%
Looking at the combined ratio is useful, but it is not the whole story. Card B alone has utilization of 40%. Some scoring models may consider both overall utilization and the utilization of individual accounts. Therefore, a low combined percentage does not always hide a heavily used card.
Why Does Credit Utilization Matter?
Credit utilization can help lenders and scoring systems understand how much of your available credit you are using. It is not simply a measure of how much money you owe. It compares that balance with the limit available to you.
1. It can affect your credit score
Credit utilization is a recognised factor in many credit scoring systems. In the United States, the FICO model places the broader “amounts owed” category at around 30% of a typical score calculation. That figure should not be treated as the official weighting for India’s CIBIL Score. Credit scoring models differ, and TransUnion CIBIL does not publish a universal percentage weight for utilization that applies to every consumer.
For practical purposes, keeping reported balances low can support a healthier credit profile. A high ratio may be a warning sign, especially when combined with missed payments or other signs of financial pressure.
2. It can influence a lender’s view of your finances
A person who regularly uses nearly all available credit may appear more dependent on borrowing. A lender may wonder whether that person has enough cash flow to manage a new EMI or an unexpected bill. This is only one part of the assessment, but it can matter when a lender reviews an application.
3. It helps reveal spending patterns
Checking utilization can show whether routine spending is taking up too much of your credit limit. If your card is often close to its limit before payday, you may need a different spending plan or a larger emergency fund. The ratio can act as an early warning before balances become difficult to repay.
4. It can matter when you apply for new credit
When you apply for a personal loan, home loan, car loan, or another credit card, a lender may review your credit report along with your income, existing EMIs, job or business stability, and other details. Lower credit utilization can be helpful, but it cannot replace a reliable payment record or the ability to repay the proposed loan.
What Is a Good Credit Utilization Ratio?
You may often hear that utilization should remain below 30%. This is a common guideline, not a universal cutoff that automatically determines whether a credit score is good or bad. A ratio of 31% does not mean that your score will suddenly fall, and a ratio of 29% does not guarantee an excellent score.
In general, lower utilization is preferable when it can be achieved without harming your cash flow or forcing you to borrow elsewhere. Some people aim for a ratio below 10%, but this is a useful target rather than a promise of a specific score. The effect depends on the scoring model, the information reported, and the rest of your credit history.
Consider these broad examples:
- 10% utilization: You are using a relatively small part of your available limit.
- 25% utilization: You are using one-quarter of your limit. This may be manageable if repayments are affordable.
- 50% utilization: Half of the available limit is in use. Review whether the balance can be reduced comfortably.
- 90% utilization: The card is close to its limit, leaving little room for new spending or emergencies.
These examples are illustrations, not official score bands. Do not carry debt or pay interest just to create a particular utilization percentage. Paying your statement balance in full by the due date is generally a sound habit when you can afford it.
Individual Utilization vs. Overall Utilization
There are two useful ways to review utilization.
Individual card utilization
This compares the balance on one card with that card’s limit. For example, a ₹45,000 balance on a card with a ₹50,000 limit means 90% utilization on that card.
Overall utilization
This compares the combined balances on relevant revolving accounts with their combined limits. If your total limits are ₹2,00,000 and your total balances are ₹40,000, your overall ratio is 20%.
Both views can be useful. If one card has a very high balance, consider paying it down if doing so fits your budget, even if the combined ratio appears low. Remember that different credit scoring systems may treat account types and balances differently.
When Is Credit Utilization Measured?
Your utilization in a credit report may not match the balance you see in your banking app at that exact moment. Card issuers generally send account information to credit bureaus periodically. The balance reported can depend on the issuer’s reporting process and timing.
For example, you might spend ₹30,000 during a billing cycle on a card with a ₹60,000 limit. If the issuer reports a ₹30,000 balance, the reported utilization would be 50%. You might then pay the full bill before the payment due date. That is responsible repayment, but the credit report may still show the earlier reported balance until the next update.
If you want to reduce the balance that is reported, check your statement dates and the issuer’s reporting practices. In some cases, paying part of the balance before the statement closes may reduce the reported amount. Do not rely on a particular date unless your card issuer confirms how it reports information.
Always pay at least the required amount by the due date, and ideally pay the full statement balance when possible. Trying to optimise a reported ratio should never lead to a late payment or unnecessary interest charges.
How to Lower Your Credit Utilization Ratio
If your ratio is high, you can take practical steps to bring it down. Choose actions that are sustainable and do not leave you short of money for rent, food, essential bills, or emergency needs.
1. Pay down outstanding balances
Reducing the balance is usually the most direct way to lower utilization. Start by listing the balance, limit, interest rate, and due date for each card. If you carry debt on multiple cards, make all required payments on time and consider directing extra money toward the balance that is most expensive or closest to its limit. Keep enough cash for essential expenses.
2. Make payments more frequently if it helps your budget
You do not always need to wait until the due date to make a payment. Some people pay part of their card balance after receiving their salary or after a large planned purchase. This can help control spending and may reduce the balance reported, depending on the issuer’s reporting cycle. Only pay money you can spare after essential commitments.
3. Avoid using the card for every expense by default
Credit cards can be convenient, but convenience can make spending less visible. Set a monthly card budget based on the amount you can repay in full. Use a debit card or another payment method for expenses that would push you beyond that budget. Do not treat the full credit limit as additional income.
4. Track each card separately
A combined utilization figure can conceal a card that is close to its limit. Review each account at least once a month. If one card has high utilization, consider shifting future spending to a card with more available room only if you can still repay the total amount. Moving spending between cards does not reduce your total debt.
5. Be cautious about closing a card
Closing a card can reduce the total credit limit available to you. If your balances stay the same, your overall utilization ratio may rise. However, keeping a card open is not always the right decision. An annual fee, fraud risk, overspending, or difficulty managing multiple accounts may justify closing it. Decide based on your circumstances, not utilization alone.
6. Request a credit limit increase only when appropriate
A higher limit can reduce the utilization percentage if your balance stays the same. But an increase is not guaranteed, and the issuer may review your credit profile or income. Do not seek a higher limit if it is likely to encourage extra spending. Also check whether the request could involve a credit inquiry under the issuer’s process.
A limit increase is not a substitute for repayment. If your balance rises along with the limit, your utilization may not improve at all.
7. Set alerts and reminders
Use banking alerts, calendar reminders, or a budgeting app to track statement dates and due dates. A reminder can prevent missed payments and help you notice when spending is higher than planned. Review card transactions regularly so that you can identify unfamiliar charges quickly.
8. Avoid applying for multiple cards just to increase available credit
Opening several accounts can add complexity and may lead to credit enquiries or changes to your credit profile. A new card does not automatically improve financial health. Apply only when you have a clear reason and understand the fees, terms, and repayment responsibilities.
Common Credit Utilization Myths
Myth 1: You must carry a balance to build credit
You generally do not need to pay interest or carry debt from month to month to demonstrate responsible card use. Use credit only for purchases you can afford, then pay the statement balance by the due date. Interest-bearing debt can make your finances more difficult without guaranteeing a better score.
Myth 2: Below 30% guarantees a good score
The 30% guideline is not a universal rule. A low ratio can help, but payment history, length of credit history, recent applications, types of accounts, and other factors may also matter. No single percentage guarantees a particular score.
Myth 3: Paying on the due date always means a low reported balance
The due date and the reporting date may be different. A high balance may be reported before you make your payment. Paying in full on time is still important; understanding the reporting cycle is a separate consideration.
Myth 4: A high credit limit means you should spend more
Your limit is the maximum amount the issuer allows you to borrow under the card terms. It is not a recommended spending target. Spending within your income and repayment capacity matters more than using a large limit.
Myth 5: Utilization is the only thing lenders check
Lenders may review your repayment history, existing debt, income, employment or business stability, credit enquiries, and the details of the product you want. A low utilization ratio cannot erase missed payments or make an unaffordable loan affordable.
Credit Utilization and Your CIBIL Score in India
For consumers in India, TransUnion CIBIL identifies credit utilization as one factor in a credit profile. Its educational materials explain that high utilization can suggest over-reliance on credit. Your CIBIL Score is based on information in your credit report, and lenders may use that score alongside other details when assessing a credit application.
There is no need to assume that every scoring model uses the same calculation or assigns the same weight to utilization. Advice based on US FICO scoring should not be presented as an official CIBIL formula. Use the 30% guideline as a general personal-finance reference, not as a guaranteed Indian scoring threshold.
💡 Key Insight
Check your credit report for accuracy. Confirm that card limits, balances, payment records, and account status are correct. If you find an error, follow the credit bureau’s and lender’s official dispute process. Correcting inaccurate data may be important, but a legitimate high balance will generally need to be addressed through repayment and better credit management.
Remember that a credit score is only one part of borrowing decisions. Lenders set their own eligibility criteria, and approval is never guaranteed by a particular utilization ratio.
A Simple Monthly Credit Utilization Checklist
Use this checklist to keep your credit card habits organised:
- Review the current balance and limit for every credit card.
- Calculate the utilization ratio for each card.
- Add balances and limits to calculate your overall ratio.
- Check statement dates and payment due dates.
- Make every required payment on time.
- Pay the full statement balance when you can afford to do so.
- Reduce high balances without neglecting essential expenses.
- Check your credit report periodically for errors or unfamiliar accounts.
- Review your budget if you repeatedly approach your card limits.
Consistency matters more than trying to achieve a perfect number in a single month. A sustainable budget and reliable repayment habits can help you manage credit over the long term.
Frequently Asked Questions
1. What is a credit utilization ratio in simple terms?
It is the percentage of your available credit limit that you are using. If your balance is ₹10,000 on a card with a ₹50,000 limit, your utilization is 20%.
2. How do I calculate overall credit utilization?
Add the balances across the relevant revolving accounts, add their credit limits, divide total balances by total limits, and multiply by 100. Also check each card individually because a single card can have high utilization even when the overall ratio is low.
3. Is 30% credit utilization good?
Below 30% is a common guideline, but it is not a universal cutoff. Lower utilization may be better for many scoring models, and the impact depends on your complete credit profile and the model being used.
4. Can high credit utilization lower my CIBIL Score?
High utilization can negatively affect how your credit profile is assessed. However, your CIBIL Score also depends on other information in your credit report. There is no guaranteed score change for a particular percentage.
5. Should I pay my credit card before the statement date?
If you want to reduce the balance that may be reported, an earlier payment could help, depending on the issuer’s reporting practices. Do not miss the payment due date, and do not spend money needed for essential expenses just to adjust utilization.
6. Does a zero utilization ratio hurt my credit score?
Scoring models differ, so there is no universal answer. You do not need to carry a balance or pay interest just to build credit. Responsible use and timely payments are more important than borrowing unnecessarily to produce a particular ratio.
7. Will increasing my credit limit improve my score?
If the limit rises and your balance remains unchanged, the utilization percentage may fall. However, the issuer may not approve the request, and a higher limit does not guarantee a score increase. Avoid taking on extra spending simply because more credit is available.
8. Does credit utilization include personal loans?
Credit utilization is generally discussed in relation to revolving credit, such as credit cards. Instalment loans like personal loans are assessed differently by many scoring models, although the outstanding debt and repayment obligations can still matter to lenders.
9. How quickly can utilization improve?
After you reduce a balance, the ratio changes when the relevant account information is updated. The timing depends on the card issuer’s reporting cycle and the credit bureau’s processing. A score may not change immediately or by a predictable amount.
10. Can a low utilization ratio guarantee loan approval?
No. Lenders consider several factors, including income, existing obligations, payment history, credit report details, and their own eligibility rules. A low ratio may support your profile, but it cannot guarantee approval.
Conclusion: Keep Credit Use Manageable and Repay on Time
A credit utilization ratio shows how much of your available revolving credit you are using. It is easy to calculate, but its effect depends on the wider credit profile and the scoring model. A low ratio can support a healthy credit profile, while consistently high utilization may signal that you rely heavily on borrowing.
Start by checking each card’s balance and limit. Calculate both individual and overall utilization. Build a realistic spending plan, pay bills on time, and reduce outstanding balances at a pace that protects your essential needs. Do not carry interest-bearing debt or open new cards simply to chase a target percentage.
For more practical insights on finance, technology, and digital business, explore Digiifrog. Use official credit bureau and card issuer resources for account-specific guidance.
Official and Helpful References
- TransUnion CIBIL: Understanding CIBIL, credit reports, and credit utilization
- TransUnion CIBIL: What Is a CIBIL Score?
- myFICO: What Should My Credit Utilization Be?
- myFICO: How FICO Scores Look at Credit Limits
Disclaimer: This article is for general educational purposes and is not individual financial, legal, or credit-repair advice. Credit scoring methods and lender policies can change. Confirm account-specific details with your card issuer and current guidance from the relevant credit bureau.
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.

Comments (0)
Log in to leave a comment.