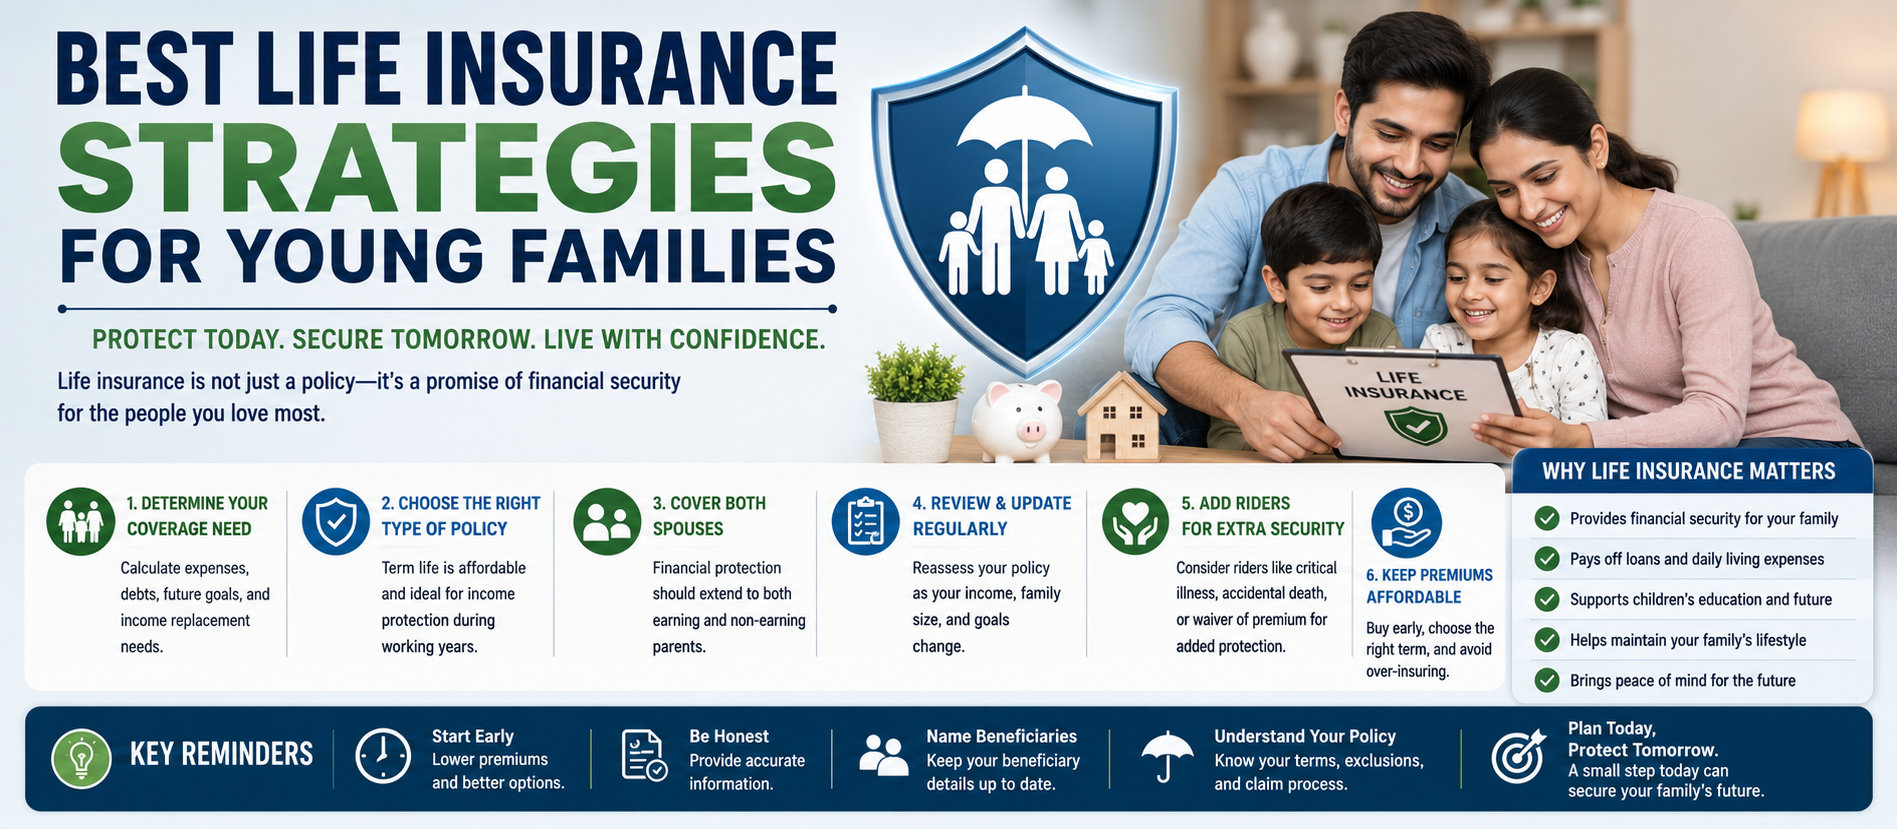
📋 Quick Summary
In this article:
1. Start With Your Family's Financial Needs
2. Calculate How Much Income Would Need to Be Replaced
3. Understand Term Life Insurance
4. Understand Permanent or Cash-Value Life Insurance
5. Match the Policy Term to Your Major Responsibilities
6. Consider Coverage for Both Parents
7. Do Not Rely Only on Employer-Provided Life Insurance
8. Choose Beneficiaries Carefully
9. Keep Beneficiary Information Updated
10. Build Life Insurance Into Your Family Budget
11. Compare Similar Policies From Multiple Providers
12. Understand Riders Before Adding Them
⚠ Watch Out
Focus Keyword: Best Life Insurance Strategies for Young Families
Starting a family changes the way many people think about money. A young couple may have a mortgage, children, regular household expenses, education goals, and long-term financial plans. If one parent or income earner dies unexpectedly, the financial effect can be serious.
Life insurance can help provide financial protection for the people who depend on you. However, choosing a policy is not simply about finding the cheapest premium or buying the largest amount of coverage. A good strategy starts with understanding what your family would need if your income or financial contribution disappeared.
This guide explains the best life insurance strategies for young families in clear, simple language. It covers coverage needs, policy types, beneficiaries, budgeting, policy reviews, and common mistakes. Because insurance rules and products vary by country, state, insurer, and policy, always review official documents before making a purchase.
1. Start With Your Family's Financial Needs
The best starting point is not a policy quote. It is a financial needs review.
Ask a simple question: if I died tomorrow, what financial responsibilities would remain for my family?
Possible needs may include:
- Replacing lost income.
- Mortgage or rent payments.
- Personal loans or other debts.
- Childcare costs.
- Daily household expenses.
- Education costs.
- Final expenses.
- Financial support during a transition period.
Every family is different. A single-income household may have different needs from a dual-income family. A stay-at-home parent may also make a major financial contribution through childcare and household work, even without a traditional salary.
Do not choose a coverage amount only because a friend, relative, or online advertisement suggests a specific number. Build your estimate around your own responsibilities and goals.
2. Calculate How Much Income Would Need to Be Replaced
Income replacement is often one of the largest parts of life insurance planning for young families.
Consider how much of the household budget depends on each adult's income. Then think about how long the family might need support. Some parents want coverage that helps support children until they become financially independent. Others may want to cover a mortgage or other long-term obligation.
A simple starting exercise is to list annual household expenses and identify which costs would continue after one person's death. Do not assume that every current expense would disappear or remain unchanged.
Also consider existing resources such as savings, employer benefits, investments, and other insurance. These resources may reduce the amount of additional protection needed, but they should be evaluated realistically.
3. Understand Term Life Insurance
Term life insurance provides coverage for a specified period. If the insured person dies during the covered term and the policy conditions are met, the death benefit is paid to the named beneficiary or beneficiaries.
For young families, term insurance can be attractive because coverage can be matched to a temporary financial need. For example, a family may want protection while children are young or while a mortgage balance is still significant.
Term insurance generally does not build cash value. It is designed mainly to provide a death benefit during the chosen coverage period.
Before buying, understand:
- How long the coverage lasts.
- Whether premiums are level during the term.
- What happens when the term ends.
- Whether renewal is available.
- Whether conversion to another type of policy is available.
A low initial premium is useful only if the policy also provides the protection your family actually needs.
4. Understand Permanent or Cash-Value Life Insurance
Permanent life insurance is designed for longer-term coverage and may include a cash-value component, depending on the policy type. Whole life and universal life are examples of permanent insurance.
These policies can be more complex and may have higher premiums than term insurance. The cash value, policy charges, guarantees, investment features, and long-term performance can vary.
Permanent coverage may be useful in some financial plans, but it is not automatically the best choice for every young family.
Before purchasing a cash-value policy, ask for a clear explanation of:
- Guaranteed benefits and values.
- Non-guaranteed illustrations or assumptions.
- Premium requirements.
- Policy fees and charges.
- Cash-value access rules.
- Loans and withdrawals.
- What could cause the policy to lapse.
If the policy is difficult to understand, ask more questions before signing. Insurance should fit the family's needs, budget, and long-term plan.
5. Match the Policy Term to Your Major Responsibilities
A practical strategy is to connect the insurance period with the period when your family has the greatest financial dependence.
For example, a young family may have a 20-year mortgage and children who will need financial support for many years. The appropriate insurance term will depend on the family's circumstances and may not match the mortgage exactly.
Think about future changes. A child may become financially independent before the mortgage is fully paid. On the other hand, one family member may require longer-term support.
Choose coverage based on the financial risk you are trying to protect against, not simply the longest or shortest term available.
6. Consider Coverage for Both Parents
A common mistake is insuring only the highest earner. Both adults may provide important financial value to the household.
If a stay-at-home parent dies, the surviving parent may face new childcare, transportation, household, and other expenses. If both adults work, the loss of either income could change the family's financial situation.
Each person's coverage should be based on the financial effect of their absence. The amounts do not need to be identical.
7. Do Not Rely Only on Employer-Provided Life Insurance
Employer-provided life insurance can be a valuable benefit. However, young families should understand the amount of coverage and whether the coverage continues after a job change.
A workplace benefit may provide useful basic protection but may not fully cover a family's mortgage, income needs, childcare costs, and long-term goals.
Review your employer policy carefully. Understand the death benefit, eligibility rules, portability or conversion options, and what happens if employment ends.
Some families use employer coverage as one part of their overall protection rather than assuming it solves every need.
8. Choose Beneficiaries Carefully
A life insurance beneficiary is the person or organization named to receive the death benefit. This decision is central to the strategy.
Review the exact legal name and contact information requested by the insurer. Consider naming both primary and contingent beneficiaries where appropriate.
A contingent beneficiary may receive the proceeds if the primary beneficiary dies before the insured person or cannot receive the benefit under the policy terms.
Young parents should be especially careful when planning for minor children. Directly naming a minor can create legal and administrative issues because insurance companies generally cannot simply pay proceeds directly to a child. A trust or other legal arrangement may be appropriate depending on local law and family circumstances.
For complex family arrangements, seek advice from a qualified estate-planning or legal professional.
9. Keep Beneficiary Information Updated
Life changes quickly. Marriage, divorce, the birth or adoption of a child, the death of a beneficiary, or a major change in family relationships can make an old designation unsuitable.
Review beneficiary information regularly and after major life events.
Do not assume that an old will automatically changes the beneficiary listed on a life insurance policy. The relationship between beneficiary designations, estate planning documents, and local law can be complex.
Keep policy information in a secure place and make sure a trusted person knows that the policy exists and can locate the relevant documents.
10. Build Life Insurance Into Your Family Budget
Life insurance should protect the family without creating unnecessary financial stress.
When comparing policies, look beyond the first monthly or annual premium. Understand whether the premium is guaranteed, how long it remains level, and whether future costs may change.
A policy that is difficult to maintain may not be a strong long-term solution. Choose a payment structure that fits your realistic budget.
Do not sacrifice essential emergency savings, debt obligations, or basic household needs simply to purchase a larger policy than you can comfortably maintain.
11. Compare Similar Policies From Multiple Providers
Life insurance is a competitive market. Once you know what type and amount of coverage you are considering, compare similar policies.
Do not compare only the premium. Also review the insurer, policy features, exclusions, riders, renewal rules, financial strength information, customer service, and policy terms.
Use official insurer documents and, where applicable, your local insurance regulator's resources. Verify that the company and agent are properly authorized to sell insurance in your location.
Comparison shopping can help you understand the market, but the lowest price is not automatically the best value.
12. Understand Riders Before Adding Them
A rider is an optional feature that changes or adds benefits to a policy. Examples may include accelerated death benefits, waiver of premium features, accidental death benefits, or child-related coverage, depending on the insurer and policy.
Every rider has its own conditions, costs, definitions, and limitations.
Do not add a rider simply because it sounds useful. Ask:
- What specific risk does it address?
- How much does it cost?
- When does it apply?
- What exclusions or limitations exist?
- Do I already have similar protection elsewhere?
Optional features can improve a policy in the right situation, but unnecessary additions can increase the cost.
13. Review Your Coverage After Major Life Changes
Life insurance should not be treated as a one-time decision that is never reviewed again.
Review your coverage after events such as:
- Marriage or divorce.
- The birth or adoption of a child.
- Buying or selling a home.
- A major increase or decrease in income.
- Starting or selling a business.
- A major change in debt.
- A serious change in a dependent's financial needs.
You may need more coverage, less coverage, a different beneficiary, or no change at all. The important step is to review the decision rather than assuming an old policy still fits.
14. Do Not Cancel Existing Coverage Before New Coverage Is Active
If you are replacing an existing policy, be careful about timing.
Do not assume that a new application will automatically result in an approved policy on the same terms you expected. Underwriting, health information, and other factors may affect the result.
In general, review the new policy carefully and confirm that it is active before canceling existing protection. Replacing insurance can also involve surrender charges, new waiting conditions, or other consequences depending on the policy.
Ask the insurer or a qualified professional to explain the risks of replacing an existing policy.
15. Keep Accurate Policy Records
A life insurance policy cannot help your family if nobody knows it exists or cannot find the information needed to make a claim.
Maintain a secure record of:
- The insurance company's name.
- Policy number.
- Coverage amount.
- Agent or company contact information.
- Beneficiary information.
- Where the policy documents are stored.
Tell beneficiaries or another trusted person enough information to locate the policy when needed. Avoid sharing sensitive details insecurely.
16. Avoid Common Life Insurance Mistakes
Young families can avoid many problems by understanding a few common mistakes.
Waiting too long to review insurance
Coverage needs can change after marriage, a new child, or a home purchase.
Choosing only by price
A cheap policy may not provide enough coverage or the features your family needs.
Buying more complexity than necessary
If you do not understand the policy, keep asking questions. Complex features should have a clear purpose.
Forgetting beneficiary updates
Old beneficiary information can create unintended results.
Ignoring the end of a term
Know what happens when term coverage expires and what options may be available.
Letting a policy lapse accidentally
Track premium due dates and keep contact information current.
17. Coordinate Life Insurance With Your Overall Financial Plan
Life insurance is one part of a larger family financial strategy.
It can work alongside emergency savings, health insurance, disability protection, retirement savings, debt management, education planning, and estate planning.
A young family should avoid treating one financial product as the solution to every risk. Each tool has a different purpose.
For example, life insurance generally addresses the financial consequences of death. Emergency savings can help with unexpected short-term expenses. Disability coverage may address the loss of income caused by an illness or injury, subject to policy terms.
18. Think About Inflation and Future Costs
A coverage amount that appears sufficient today may have less purchasing power in the future. Young families often have financial responsibilities that can change over many years.
Consider possible increases in living costs, education expenses, childcare, and housing. This does not mean you must predict inflation perfectly. It means your coverage estimate should consider that future expenses may differ from today's numbers.
Reviewing the policy periodically is one way to keep this issue under control.
19. Use a Simple Coverage Review Worksheet
Before speaking with an insurer or adviser, prepare a basic list of your family's financial responsibilities.
- Outstanding mortgage balance.
- Other significant debts.
- Estimated annual household expenses.
- Income that would need to be replaced.
- Childcare needs.
- Education goals.
- Final expenses.
- Existing savings and investments.
- Existing life insurance.
This worksheet is not a substitute for professional advice. It is a starting point that can help you ask better questions and avoid choosing coverage without understanding your needs.
20. Ask Better Questions Before Buying
Before purchasing life insurance, ask direct questions and keep the answers.
- What exactly does this policy cover?
- How long does coverage last?
- Is the premium fixed or can it change?
- What happens if I miss a payment?
- What exclusions apply?
- Can I renew or convert the policy?
- How are beneficiaries paid?
- What riders are included or optional?
- What are the policy's guaranteed benefits?
- Which values or illustrations are not guaranteed?
Clear answers are essential. Do not feel pressured to buy a policy before you understand it.
A Simple Life Insurance Strategy Checklist for Young Families
- List the people who depend on you financially.
- Estimate income and household costs that would need support.
- Review major debts and future goals.
- Check existing employer-provided coverage.
- Compare term and permanent insurance based on your needs.
- Choose a realistic coverage period.
- Consider coverage for both parents.
- Name primary and, where appropriate, contingent beneficiaries.
- Consider professional guidance for minor children or complex estate issues.
- Compare similar policies from multiple authorized providers.
- Understand riders, exclusions, and premium requirements.
- Store policy information securely.
- Review coverage after major life events.
SEO, AEO, GEO, and AI Search Optimization for Life Insurance Content
People researching life insurance usually want direct answers to practical questions. Clear headings and simple explanations help readers understand complex financial topics.
SEO can improve traditional search visibility. AEO focuses on answering specific questions clearly. GEO and AI Search optimization help content remain understandable when generative systems summarize and connect information.
Useful questions include:
- How much life insurance does a young family need?
- Is term life insurance good for young parents?
- Should both parents have life insurance?
- What is the difference between term and permanent life insurance?
- How do I choose a life insurance beneficiary?
- When should I review my life insurance policy?
- Can employer life insurance be enough for a family?
Short paragraphs, direct definitions, practical checklists, and balanced explanations make insurance content easier for both readers and AI-powered search systems to understand.
Frequently Asked Questions
What type of life insurance is often considered by young families?
Many young families consider term life insurance because it provides coverage for a selected period and is generally less expensive than permanent insurance in the early policy years. The right choice depends on the family's financial needs and long-term goals.
Should both parents have life insurance?
Both parents may have financial value to the household. The need for coverage should be based on the financial effect of losing each person's income, childcare, household contribution, or other support.
How often should young families review life insurance?
A review is useful after major life events such as marriage, a new child, a home purchase, a major income change, or a change in debt. An annual check of beneficiary and contact information can also help keep records current.
What is a contingent beneficiary?
A contingent beneficiary is generally named to receive policy proceeds if the primary beneficiary dies before the insured or cannot receive the benefit according to the policy terms.
Can a young child be named directly as a life insurance beneficiary?
Rules vary, but directly naming a minor can create legal or administrative complications. Families with minor children should consider obtaining qualified legal or estate-planning advice about the appropriate arrangement.
Is employer-provided life insurance enough?
It may provide useful protection, but the amount and portability may be limited. Compare the benefit with your family's actual financial needs before relying on it as your only coverage.
Final Thoughts
The best life insurance strategy for a young family is built around real financial responsibilities, not a one-size-fits-all formula.
Start by identifying who depends on you and what financial needs would remain if you died. Compare policy types, understand the duration of coverage, choose beneficiaries carefully, and make sure the premium fits your long-term budget.
💡 Key Insight
For many young families, the biggest protection needs occur while children are dependent, debts are significant, and household income is essential. As life changes, insurance should be reviewed to make sure it still matches the family's situation.
Read the official policy documents carefully. Ask questions about coverage, exclusions, renewals, conversion options, beneficiaries, and costs. For complex estate, tax, or insurance decisions, consult appropriately qualified professionals.
For practical SEO, AEO, GEO, and AI Search optimized content, visit Digiifrog at www.digiifrog.com.
Disclaimer: This article is for general educational and informational purposes only. It is not legal, tax, investment, estate-planning, or personalized insurance advice. Life insurance laws, products, underwriting, beneficiary rules, and consumer protections vary by jurisdiction and policy. Review official policy documents and consult licensed or otherwise qualified professionals for guidance about your individual circumstances.
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.
Comments (0)
Log in to leave a comment.