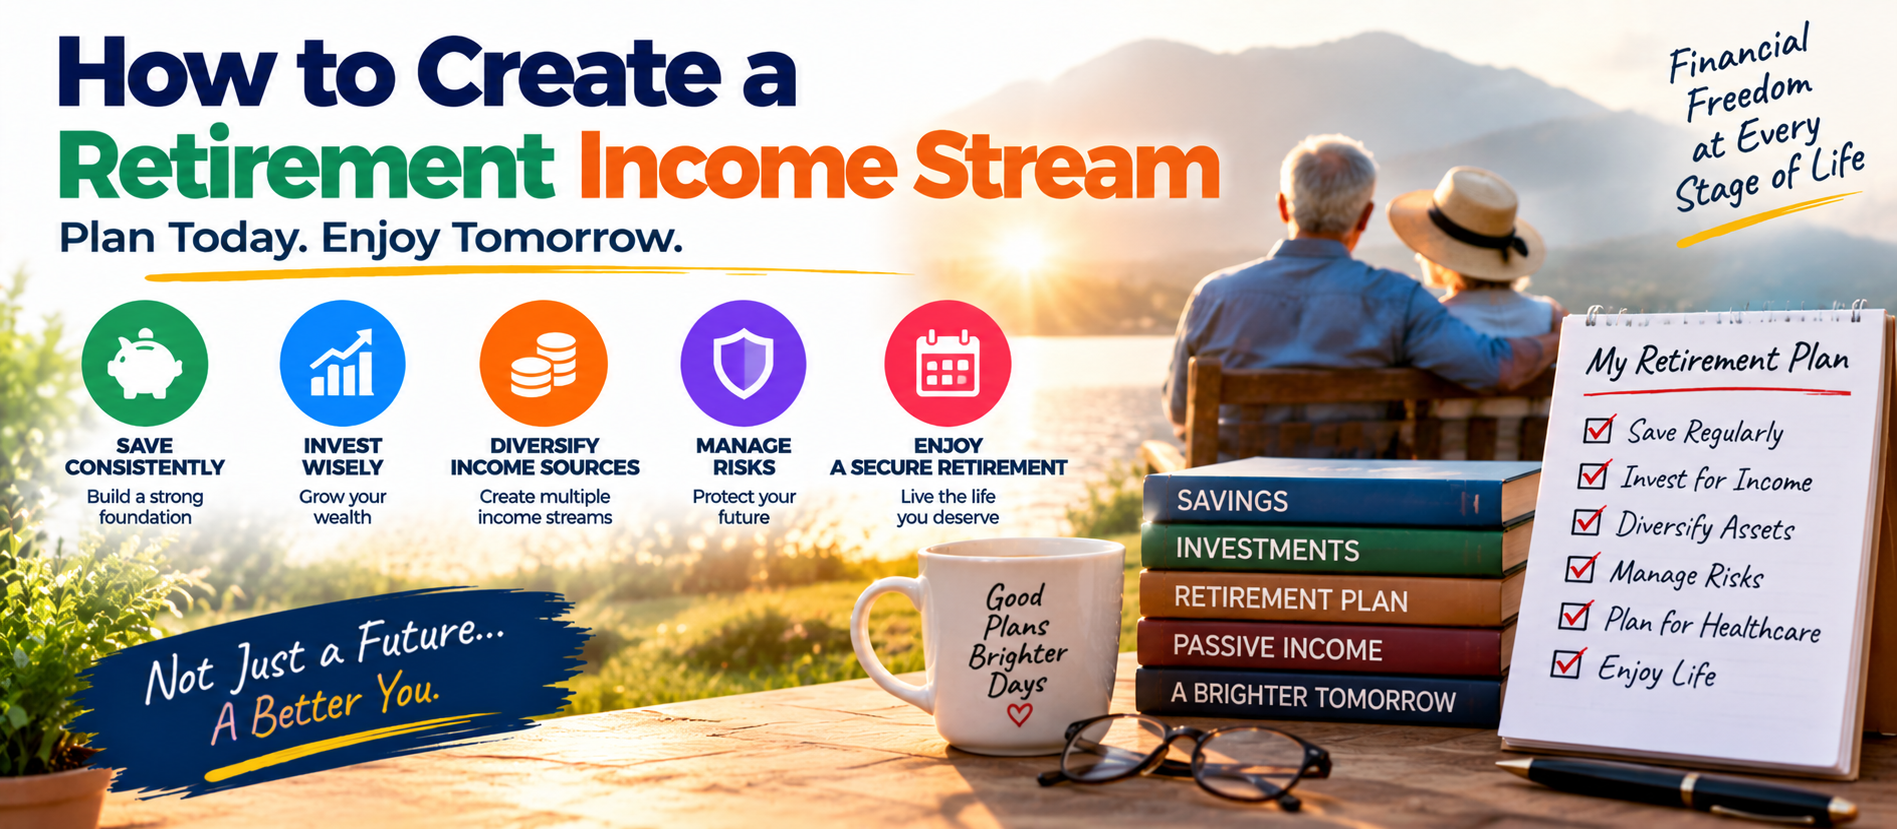
📋 Quick Summary
In this article:
Quick Answer: How Do You Create a Retirement Income Stream?
What Is a Retirement Income Stream?
Step 1: Estimate Your Retirement Expenses
Step 2: Identify Your Existing Retirement Income Sources
Step 3: Calculate the Income Gap
Step 4: Build Multiple Income Sources
Step 5: Create a Retirement Withdrawal Strategy
💡 Key Insight
Creating a retirement income stream is one of the most important parts of retirement planning. During your working years, your primary income may come from a salary or business. After retirement, you may need other sources of income to cover housing, food, healthcare, transportation, insurance, and everyday expenses.
A retirement income plan can help you understand where your future money may come from and how long it may need to last. The right approach depends on your savings, retirement age, lifestyle, location, expected expenses, taxes, health needs, and other personal circumstances.
This guide explains how to create a retirement income stream using clear and practical language. It covers common income sources, planning strategies, diversification, withdrawal considerations, inflation, and risk management.
Quick Answer: How Do You Create a Retirement Income Stream?
A retirement income stream can be created by combining reliable income sources, personal savings, investments, retirement accounts, and other assets in a way that supports your expected expenses. A strong plan usually starts with estimating retirement spending, identifying available income sources, managing withdrawal risk, and reviewing the plan regularly.
The best approach depends on individual financial circumstances and local retirement rules.
What Is a Retirement Income Stream?
A retirement income stream is the money you receive or withdraw regularly to support your lifestyle after leaving full-time work.
Retirement income may come from several sources, including:
- Government retirement benefits, where available.
- Employer pensions.
- Retirement accounts.
- Personal savings and investments.
- Dividend or interest income.
- Rental income.
- Part-time work or business income.
- Annuities or other financial products.
Depending on only one source may create financial risk. Many retirement plans use a combination of income sources.
Step 1: Estimate Your Retirement Expenses
Before creating an income stream, estimate how much money you may need each month or year.
Start by listing your expected expenses:
- Housing or rent.
- Food and household costs.
- Utilities.
- Healthcare and insurance.
- Transportation.
- Debt payments.
- Travel and entertainment.
- Family responsibilities.
- Emergency expenses.
Your spending may change after retirement. Some work-related costs may decline, but healthcare or leisure expenses may increase.
It is useful to separate expenses into three groups:
- Essential expenses: Costs you must pay.
- Flexible expenses: Costs that can be reduced if necessary.
- Unexpected expenses: Emergency or unplanned costs.
Step 2: Identify Your Existing Retirement Income Sources
Next, make a complete list of income sources that may be available after retirement.
Government Benefits
Many countries offer government-supported retirement benefits. Eligibility rules, payment amounts, and starting ages vary by location. Understanding when benefits begin can help you plan the rest of your retirement income.
Employer Pensions
Some employers provide defined-benefit pensions or other retirement benefits. If you have a pension, learn how payments are calculated and whether benefits include options for spouses or beneficiaries.
Retirement Accounts
Retirement accounts may become an important source of income. Withdrawal rules and tax treatment can vary based on your country and the type of account.
Personal Investments
Stocks, bonds, ETFs, mutual funds, and other investments may provide a source of retirement income through withdrawals, dividends, interest, or asset sales.
Other Income
Rental property, consulting, part-time work, and small businesses may also contribute to retirement income.
Step 3: Calculate the Income Gap
After estimating your expenses and expected income, calculate the difference.
Retirement Income Gap = Expected Retirement Expenses − Reliable Retirement Income
For example, if expected annual expenses are $60,000 and reliable income sources provide $35,000, the estimated income gap is $25,000.
Your investments and savings may need to help cover this difference.
Step 4: Build Multiple Income Sources
One of the main principles of retirement planning is diversification. Just as investors may diversify investments, retirees may benefit from having more than one source of income.
A retirement income plan could combine:
- Reliable or predictable income for essential expenses.
- Investment income for additional spending.
- Cash reserves for short-term needs.
- Flexible income sources for lifestyle expenses.
The goal is to create a manageable plan that supports your financial needs.
Step 5: Create a Retirement Withdrawal Strategy
For many retirees, deciding how much to withdraw from savings is one of the biggest challenges.
Withdraw too much too early, and your savings may not last as long as expected. Withdraw too little, and you may unnecessarily limit your lifestyle.
Important factors include:
- Total savings and investments.
- Expected lifespan.
- Investment returns.
- Inflation.
- Taxes.
- Healthcare costs.
- Market conditions.
A fixed withdrawal amount may be simple, but it may not work equally well in every market or economic environment.
Fixed Withdrawal Strategy
A fixed withdrawal strategy involves taking the same amount of money at regular intervals.
This approach can make budgeting easier. However, inflation may reduce the purchasing power of a fixed income over time.
If investment markets perform poorly for several years, fixed withdrawals may also place additional pressure on the portfolio.
Percentage-Based Withdrawal Strategy
Another approach is to withdraw a percentage of the portfolio value.
When the portfolio value rises, the withdrawal amount may increase. When the portfolio declines, the withdrawal amount may decrease.
This method may help preserve assets, but income can become less predictable. Retirees using this approach may need flexibility in their spending.
Flexible Withdrawal Strategy
A flexible strategy adjusts spending based on market conditions and personal needs.
For example, a retiree may reduce discretionary spending after a significant market decline and increase spending when the portfolio performs well.
Flexibility can help manage risk, but it requires careful planning and regular monitoring.
Step 6: Consider the Bucket Strategy
The bucket strategy divides retirement assets based on when the money may be needed.
Short-Term Bucket
This may contain cash or relatively stable assets for near-term expenses.
Medium-Term Bucket
This portion may contain investments intended to support expenses over the next several years.
Long-Term Bucket
The long-term portion may focus more on growth and may include investments intended for future spending needs.
The exact structure depends on individual circumstances. The main idea is to avoid placing all retirement assets into one type of investment.
Step 7: Plan for Inflation
Inflation is a major retirement planning challenge because the cost of goods and services can increase over time.
A retirement income that appears sufficient today may have less purchasing power in the future.
When planning for inflation, consider:
- Expected long-term spending needs.
- Potential increases in healthcare costs.
- Housing and utility expenses.
- Whether some income sources adjust for inflation.
- Whether part of the investment portfolio has long-term growth potential.
Ignoring inflation can cause retirees to underestimate how much income they may need later in life.
Step 8: Maintain an Emergency Fund
Unexpected expenses can occur at any stage of retirement. A financial emergency may force you to sell investments at an unfavorable time if you do not have accessible savings.
An emergency reserve can help cover unexpected costs such as major home repairs, urgent travel, or other financial needs.
The appropriate amount depends on your spending level, income stability, insurance coverage, and personal circumstances.
Step 9: Manage Investment Risk
Retirement does not necessarily mean you should eliminate all investment risk. Many retirees need some long-term growth to help address inflation and longevity.
However, taking excessive risk can create large portfolio losses at a time when regular withdrawals are required.
A retirement portfolio should consider:
- Stock market risk.
- Interest-rate risk.
- Inflation risk.
- Credit risk.
- Liquidity risk.
- Longevity risk.
The appropriate balance between growth and stability depends on the individual's financial situation.
Step 10: Consider Reliable Income for Essential Expenses
Some retirees prefer to cover essential expenses using relatively reliable income sources where available.
Examples may include:
- Government retirement benefits.
- Employer pensions.
- Certain guaranteed-income products, subject to their terms and risks.
Investment portfolios may then be used to support flexible or discretionary expenses.
Whether this structure is appropriate depends on personal goals, available products, costs, and local financial regulations.
Taxes and Retirement Income Planning
Taxes can have a significant effect on retirement income.
Different income sources may be taxed differently depending on your country, account type, and tax laws.
Important questions may include:
- Which retirement withdrawals are taxable?
- How are investment gains taxed?
- Are government benefits taxable?
- Will your tax rate change during retirement?
Tax laws can change, and rules differ by location. Consider consulting a qualified tax or financial professional for personalized guidance.
Common Mistakes When Creating a Retirement Income Stream
1. Starting Without an Expense Plan
Without knowing expected spending, it is difficult to determine how much retirement income may be required.
2. Depending on One Income Source
Relying heavily on a single pension, investment, property, or benefit can create concentration risk.
3. Ignoring Inflation
Long retirements can last decades. Purchasing power may decline significantly over time.
4. Withdrawing Too Aggressively
Large early withdrawals can reduce the amount available for future needs.
5. Keeping Too Much or Too Little Investment Risk
Too much risk may create severe losses. Too little growth potential may increase inflation risk.
6. Ignoring Taxes and Fees
Taxes, investment expenses, and financial product costs can reduce available income.
7. Failing to Review the Plan
A retirement plan should change when life circumstances change.
How Often Should You Review Your Retirement Income Plan?
Many people benefit from reviewing their retirement plan periodically and after major life events.
You may need to reassess the plan after:
- A major change in expenses.
- Retirement or loss of employment.
- A large market movement.
- A change in health or family circumstances.
- A change in tax or retirement rules.
A review does not always mean making changes. Sometimes the purpose is simply to confirm that the existing plan still supports your goals.
A Simple Framework for Building a Retirement Income Stream
- Estimate your expected retirement expenses.
- Identify reliable income sources.
- Calculate the income gap.
- Determine how savings and investments may support the gap.
- Create a withdrawal approach.
- Maintain an emergency reserve.
- Consider inflation and taxes.
- Review investment risk and diversification.
- Update the plan as circumstances change.
Frequently Asked Questions
What is the best way to create retirement income?
The best approach depends on individual circumstances. Many retirement plans combine government benefits, pensions, savings, investments, and other income sources to support essential and lifestyle expenses.
How many income streams should a retiree have?
There is no required number. The focus should be on whether total income is sufficient, reliable enough for your needs, diversified appropriately, and sustainable over time.
Can investment income support retirement?
Investments may support retirement through withdrawals, dividends, interest, or asset sales. However, investment values and income can fluctuate, and all investments involve risk.
Should retirees keep investing?
Some retirees maintain investments for long-term growth and inflation protection. The appropriate level of investment risk depends on personal circumstances, income needs, and time horizon.
How often should a retirement income plan be reviewed?
A periodic review and reassessment after major life or financial changes can help determine whether the plan still supports your needs.
Final Thoughts
Creating a retirement income stream starts with understanding your future expenses and identifying reliable sources of income. The goal is to create a sustainable plan that can support your lifestyle while managing inflation, market volatility, taxes, and unexpected expenses.
For many people, a combination of income sources may provide greater flexibility than relying on a single source. Savings, investments, pensions, government benefits, and other income may each play a role.
Retirement planning is not a one-time activity. Regular reviews can help keep your strategy aligned with changing circumstances.
For more helpful content about personal finance, investing, business, technology, SEO, AEO, GEO, and AI Search optimization, visit www.digiifrog.com.
Disclaimer
This article is for general educational and informational purposes only and does not constitute investment, financial, legal, or tax advice. It is not a recommendation to buy, sell, or hold any investment or financial product. Retirement planning involves risk, and financial outcomes cannot be guaranteed. Rules, taxes, benefits, and investment options vary by location and may change. Consider consulting a qualified financial, tax, or legal professional before making significant retirement decisions.
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.

Comments (0)
Log in to leave a comment.