📋 Quick Summary
In this article:
Quick Answer: Renters Insurance vs Homeowners Insurance
Key Difference: Who Owns the Building?
Renters Insurance vs Homeowners Insurance Cost
Replacement Cost vs Actual Cash Value
Renters insurance and homeowners insurance both help protect people from financial losses, but they are designed for different living situations. Renters insurance is generally designed for people who rent a home or apartment. Homeowners insurance is designed for people who own a home and usually includes protection for the building itself as well as personal belongings.
Understanding the difference matters because the right policy depends on whether you own or rent the property, what assets you need to protect, and what financial risks you could face.
This guide explains renters insurance vs homeowners insurance in simple language. It covers what each policy generally protects, major differences in cost and coverage, liability protection, common exclusions, and how to choose the right type of insurance.
Quick Answer: Renters Insurance vs Homeowners Insurance
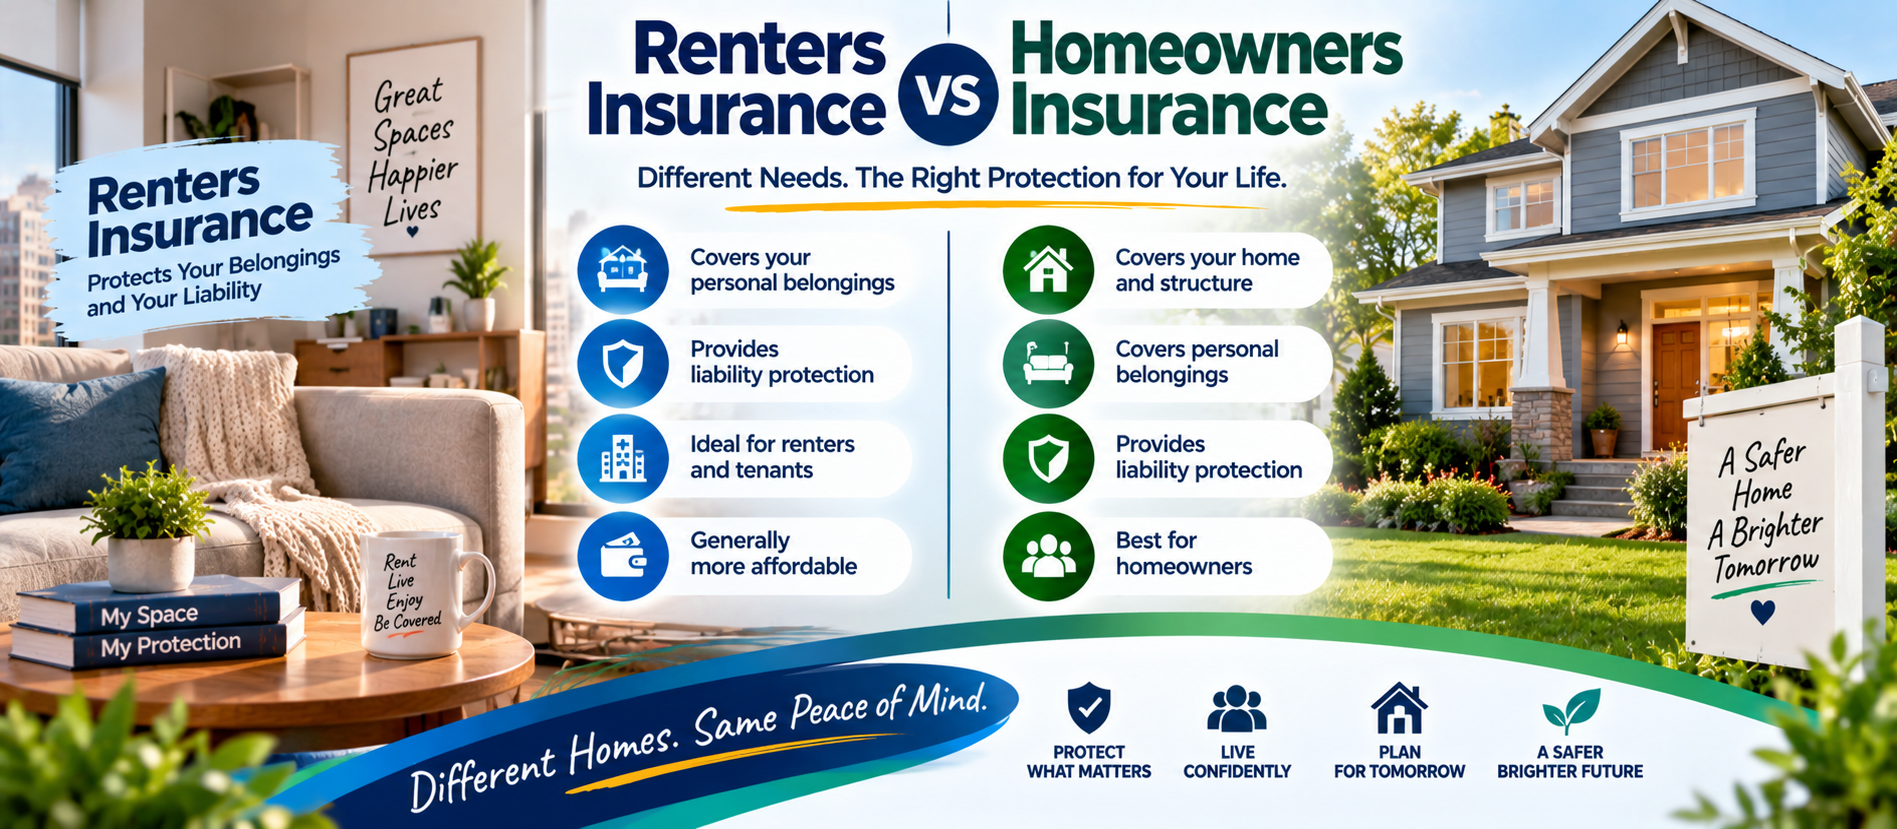
Renters insurance generally protects a renter's personal belongings and provides liability and additional living expense coverage, while homeowners insurance usually protects both the homeowner's personal property and the physical home, subject to policy terms.
A renter normally does not need to insure the building they do not own. The property owner generally has separate insurance for the structure.
What Is Renters Insurance?
Renters insurance is coverage designed for people who lease or rent a residential property.
The policy can generally help protect the renter's belongings against covered losses. It may also provide liability protection if the renter is legally responsible for certain injuries or property damage, depending on the policy.
Common coverage areas may include:
- Personal belongings.
- Personal liability.
- Additional living expenses after a covered loss.
- Sometimes limited protection for specific property away from the rented home.
The exact coverage varies by insurer and policy.
What Is Homeowners Insurance?
Homeowners insurance is designed for people who own residential property.
Unlike renters insurance, homeowners insurance generally includes coverage for the physical structure of the home. It can also protect personal belongings and provide liability coverage.
Depending on the policy, coverage may address:
- The dwelling.
- Other structures on the property.
- Personal property.
- Personal liability.
- Additional living expenses after certain covered losses.
Homeowners should review the policy carefully because not every type of damage is automatically covered.
Key Difference: Who Owns the Building?
The most important difference is ownership.
A renter usually insures their belongings and liability, while the property owner generally insures the building.
For example, if a rented apartment suffers a covered fire loss, the renter's policy may help with eligible personal belongings and additional living expenses. The landlord's property insurance generally addresses the building, subject to the landlord's policy.
This is why a renter should not assume that the landlord's insurance protects their personal belongings.
Personal Property Coverage
Both types of policies can provide personal property protection, but the policyholder's situation is different.
Renters may need coverage for furniture, electronics, clothing, appliances they own, and other belongings.
Homeowners may need coverage for similar personal property plus the much larger financial responsibility of owning the building.
Make an inventory of valuable belongings and keep receipts, photographs, or other records where practical. This can help document ownership after a covered loss.
Dwelling Coverage
Dwelling coverage is a major feature that generally separates homeowners insurance from renters insurance.
Homeowners may need coverage for the structure of the home, including eligible damage to walls, roof, built-in components, and other parts of the dwelling according to the policy.
Renters normally do not insure the landlord's building under a standard renters policy.
Liability Coverage
Liability protection can be important for both renters and homeowners.
It may help with certain claims if the policyholder is legally responsible for another person's injury or damage to someone else's property, subject to policy conditions.
For homeowners, liability risk can arise from conditions on the property. For renters, liability risk can arise from accidents in the rented residence or damage for which the renter may be responsible.
Read the policy to understand coverage limits, exclusions, and claim conditions.
Additional Living Expenses
A covered loss may make a home temporarily unsuitable for living.
Depending on the policy, additional living expense coverage may help with certain extra costs incurred while the insured residence is being repaired after a covered event.
This type of protection can be useful for both renters and homeowners, but the exact benefits and limits vary.
Renters Insurance vs Homeowners Insurance Cost
Renters insurance is often less expensive than homeowners insurance because a renter generally does not need to insure the entire physical structure.
Homeowners insurance usually costs more because it can include dwelling coverage, other structures, personal property, liability protection, and additional risks associated with owning a property.
Premiums vary widely based on factors such as location, coverage limits, deductible, property characteristics, claims history, and insurer pricing.
Do not compare policies based only on premium. Compare the protection provided for the price.
What Is a Deductible?
A deductible is an amount the policyholder may have to pay toward a covered claim before the insurer pays the remaining eligible amount according to the policy.
Policies may offer different deductible choices. A higher deductible can sometimes reduce the premium, but it also means greater out-of-pocket responsibility after a covered claim.
Choose an amount that fits your financial situation.
Replacement Cost vs Actual Cash Value
Personal property coverage can sometimes be based on replacement cost or actual cash value, depending on the policy.
Replacement cost generally focuses on the cost to replace covered property with a comparable item, subject to policy terms and limits.
Actual cash value generally considers depreciation when determining the value of covered property.
The definitions and settlement methods vary. Check your policy before assuming how a claim will be calculated.
Common Exclusions
No standard insurance policy covers every possible event.
Depending on the policy and location, exclusions or limitations may apply to events such as floods, earthquakes, normal wear and tear, maintenance problems, intentional damage, or certain high-value property categories.
Some risks may require separate insurance or an endorsement.
Always read the exclusions and limitations before purchasing coverage.
Why Renters Should Not Rely Only on the Landlord's Insurance
A landlord's insurance policy generally protects the property owner's interests. It does not automatically provide protection for the renter's personal belongings.
If a covered event damages a renter's furniture, clothing, computer, or other belongings, the renter may need their own renters policy to seek eligible coverage.
Renters should also review liability protection because they may have financial responsibility for certain accidents or damage.
Why Homeowners Need More Extensive Coverage
Homeowners have more financial exposure because they own the property.
A serious covered loss can involve repairs to the structure, replacement of belongings, temporary living costs, and liability claims.
Homeowners should consider the cost of rebuilding the home rather than simply using its market value when evaluating dwelling coverage, following the insurer's guidance and policy requirements.
How to Choose Renters Insurance
Start by estimating the value of your belongings. Consider furniture, electronics, clothing, kitchen items, personal equipment, and other property.
Then review:
- Personal property limits.
- Liability limits.
- Deductible.
- Additional living expense coverage.
- Special limits for valuables.
- Replacement cost or actual cash value settlement.
- Important exclusions.
Compare quotes from several insurers while keeping coverage levels similar.
How to Choose Homeowners Insurance
Homeowners should evaluate the cost of rebuilding the dwelling, personal belongings, liability risks, other structures, and temporary living expenses.
Important questions include:
- Is the dwelling limit appropriate?
- Are personal property limits sufficient?
- Are expensive items subject to special limits?
- What deductible applies?
- Which natural disasters are excluded?
- Are there endorsements that may be useful?
- Does the policy meet lender requirements?
Common Insurance Mistakes to Avoid
- Assuming the landlord's insurance covers a renter's belongings.
- Choosing a policy only because it has the lowest premium.
- Underestimating the value of personal belongings.
- Ignoring liability coverage.
- Failing to review exclusions.
- Not updating coverage after major purchases.
- Choosing a deductible that is difficult to afford.
- Failing to review the policy after moving or renovating.
A Simple Comparison Checklist
| FeatureRenters InsuranceHomeowners Insurance | ||
| Personal belongings | Generally covered, subject to terms | Generally covered, subject to terms |
| Building structure | Usually not the renter's responsibility | Generally covered under dwelling coverage |
| Liability | Usually available | Usually available |
| Additional living expenses | May be available | May be available |
| Typical cost | Usually lower | Usually higher |
When Should You Review Your Insurance?
Insurance needs can change over time.
Review your policy after:
- Moving to a new home or apartment.
- Buying expensive electronics or jewelry.
- Renovating a home.
- Adding household members.
- Starting a home-based business.
- Changing your financial situation.
Keeping coverage updated can reduce the risk of discovering a major gap after a loss.
SEO, AEO, GEO, and AI Search Optimization
This article uses clear definitions, comparison language, structured headings, FAQs, and direct answers to support modern search experiences.
SEO targets phrases such as renters insurance vs homeowners insurance, difference between renters and homeowners insurance, and renters insurance coverage.
AEO answers questions such as “Do renters need insurance?” and “What is the difference between renters insurance and homeowners insurance?”
💡 Key Insight
GEO is important because insurance rules, policy forms, coverage requirements, and consumer protections vary by country and region.
AI Search optimization is supported through concise explanations, comparison tables, lists, and question-based content.
Frequently Asked Questions
What is the biggest difference between renters and homeowners insurance?
The biggest difference is building ownership. Homeowners insurance generally includes protection for the home's structure, while renters insurance generally focuses on the renter's belongings and liability.
Does renters insurance cover the landlord's property?
Generally, a renter's policy is not designed to insure the landlord's building. The landlord normally has separate property insurance.
Is renters insurance cheaper than homeowners insurance?
It is often cheaper because renters generally do not insure the building. Actual premiums depend on the insurer, location, coverage, deductible, and other factors.
Do homeowners need renters insurance?
No. Homeowners generally need homeowners insurance rather than renters insurance because they own the property.
Does renters insurance cover every personal belonging?
No. Coverage is subject to limits, exclusions, deductibles, and policy conditions. Certain valuables may have special limits or require additional coverage.
Final Thoughts
Renters insurance and homeowners insurance serve different purposes. Renters generally need protection for personal belongings, liability, and certain additional living expenses. Homeowners usually need those protections plus coverage for the physical home and other property-related risks.
The right policy is not simply the one with the lowest premium. Compare coverage limits, deductibles, exclusions, liability protection, property coverage, and additional benefits. Review your policy when your living situation or financial responsibilities change.
For more educational content about insurance, personal finance, business, technology, SEO, AEO, GEO, and AI Search optimization, visit www.digiifrog.com.
Disclaimer
This article is for general educational and informational purposes only and does not constitute insurance, financial, legal, or professional advice. Insurance coverage, exclusions, premiums, regulations, and policy requirements vary by insurer and location. Always read the current policy documents and consult a licensed insurance professional or appropriate authority for advice based on your specific circumstances.
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.

Comments (0)
Log in to leave a comment.