📋 Quick Summary
In this article:
Quick Answer: Is Single-Trip or Annual Travel Insurance Better?
What Is Single-Trip Travel Insurance?
Advantages of single-trip insurance
What Is Annual Multi-Trip Travel Insurance?
Advantages of annual travel insurance
Single-Trip vs Annual Travel Insurance: Key Differences
Medical Emergency Cover: A Priority for International Travel
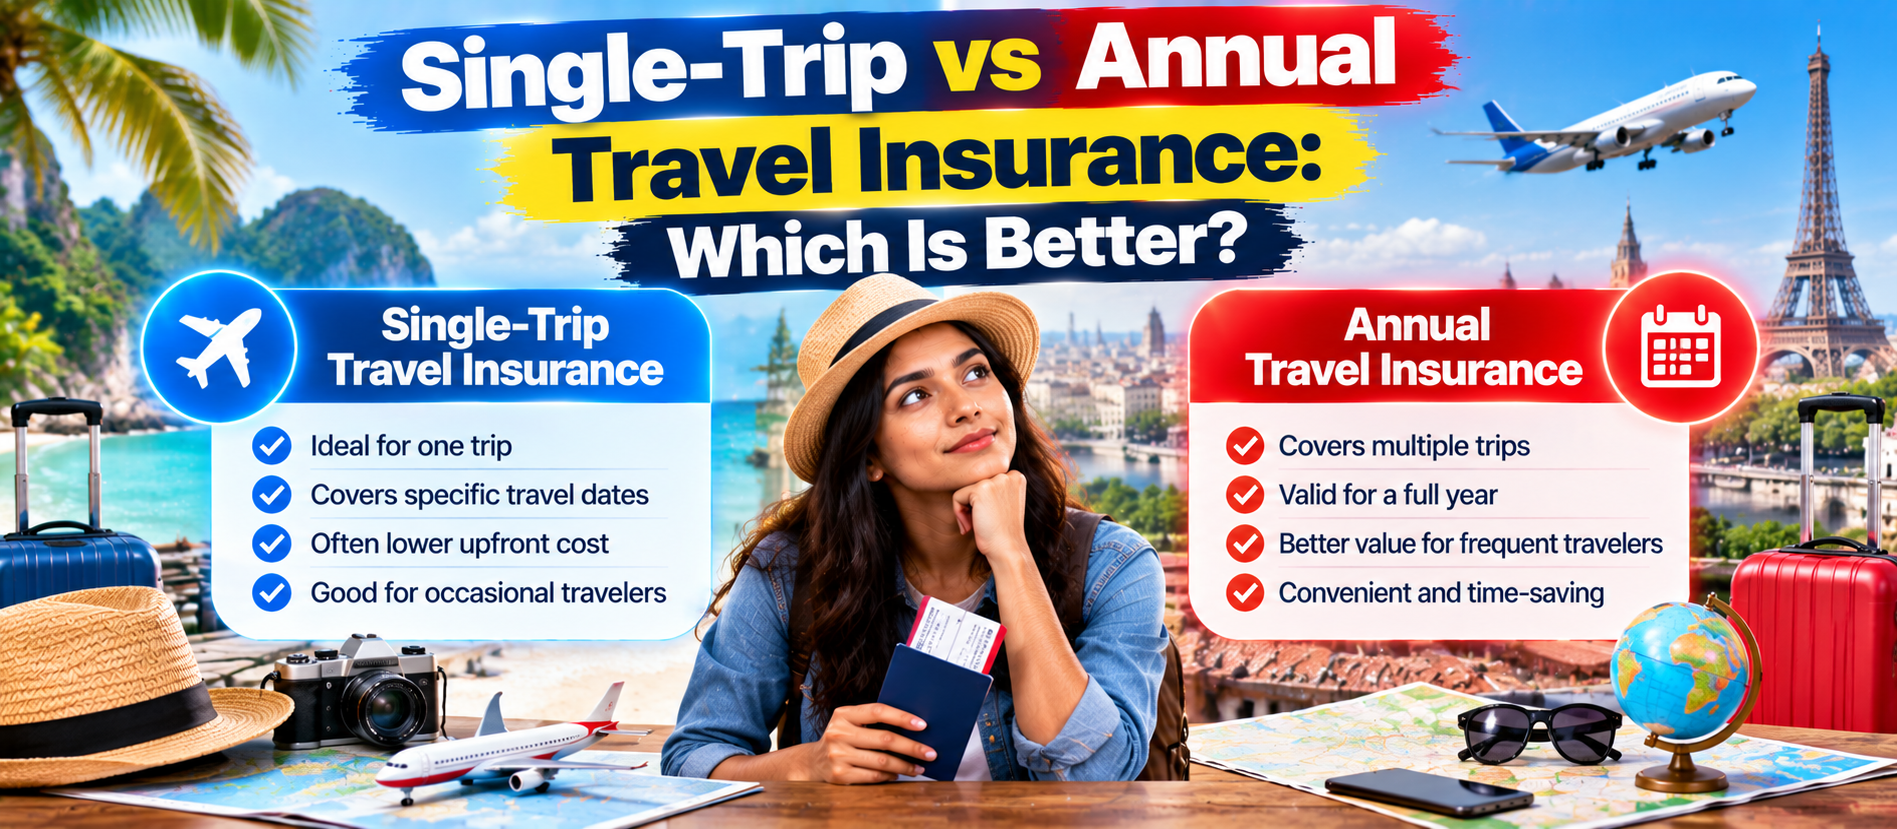
The best travel insurance option depends on how often you travel, where you go, how long you stay, and what protection you need. Single-trip insurance covers one journey. Annual travel insurance, often called annual multi-trip insurance, can cover several eligible trips during a 12-month policy period.
Annual cover may suit frequent travelers, while single-trip cover may be more practical for one holiday or a single business journey. However, price is only one part of the decision. Trip-length limits, medical cover, cancellation benefits, exclusions, and destination rules can all affect which policy offers better value.
Quick Answer: Is Single-Trip or Annual Travel Insurance Better?
Choose single-trip insurance if you are taking one journey or do not expect to travel often during the next year. It can be tailored to a specific destination and travel period.
Consider annual multi-trip insurance if you expect to take several trips within 12 months. It may be more convenient and can cost less than buying separate policies for every trip. But annual policies often limit the length of each trip and may restrict certain destinations or activities.
Compare the total cost of the policies you would actually buy. Check medical limits, emergency assistance, cancellation cover, baggage benefits, excesses, and exclusions. The policy with the lowest price is not automatically the best choice.
What Is Single-Trip Travel Insurance?
Single-trip travel insurance is designed for one journey. Cover normally begins and ends on dates shown in the policy, subject to its terms. Depending on the plan, it may cover eligible medical emergencies, trip cancellation or interruption, baggage loss or delay, travel delays, and emergency assistance.
For example, a traveler going abroad for a two-week holiday may buy a policy for that specific journey. The cover can be selected for the destination and travel dates, and some insurers allow optional benefits to be added.
Advantages of single-trip insurance
- Suitable for occasional travelers: You pay for a particular journey rather than a full year of cover.
- Trip-specific options: You may be able to choose cover that matches the destination, trip duration, and planned activities.
- Useful for longer journeys: Some single-trip policies allow longer stays than annual multi-trip plans, although maximum durations vary.
- Clear travel dates: The cover period is tied to one planned journey, subject to the policy wording.
- Can suit unusual itineraries: A specialist single-trip policy may be easier to match to a long or complex journey.
Possible disadvantages
- You may need to buy a new policy for every separate trip.
- Several separate policies can cost more than one annual plan if you travel frequently.
- You must remember to arrange cover for each new journey.
- A new policy may have different terms, exclusions, or eligibility rules from a previous one.
What Is Annual Multi-Trip Travel Insurance?
Annual multi-trip travel insurance provides cover for multiple eligible journeys during one policy year. You buy the policy once and can travel several times without purchasing a separate policy for every trip, as long as each journey meets the policy rules.
These policies are often designed for people who take regular holidays, visit family, or travel for business. A policy may cover trips to selected regions or worldwide destinations, but worldwide cover can have different options and pricing.
Advantages of annual travel insurance
- Convenience: You do not need to arrange a new policy for each eligible trip.
- Potential savings: It may cost less than several separate policies, depending on trip count, destinations, ages, and cover levels.
- Useful for frequent travelers: It can suit people who take regular short breaks or business trips.
- Consistent policy terms: Eligible trips are generally covered under one policy, subject to its conditions and limits.
- Less repeated administration: Once the policy is active, arranging cover for each eligible journey is usually simpler.
Possible disadvantages
- Each trip may have a maximum duration, such as a set number of days.
- Long stays may need an extension or a separate single-trip policy.
- Some policies limit the number of trips or define what counts as a separate trip.
- Not all destinations, sports, work activities, or travel purposes are covered.
- The annual premium may not be worthwhile if you take only one trip.
Single-Trip vs Annual Travel Insurance: Key Differences
| Feature Single-trip policy Annual multi-trip policy | ||
| Coverage period | One specified journey | Multiple eligible trips during the policy year |
| Best suited to | Occasional travelers | Frequent travelers |
| Buying process | Usually purchased for each trip | Usually purchased once per policy year |
| Trip length | May allow longer journeys, depending on the plan | Usually has a maximum duration for each trip |
| Cost | May be economical for one journey | May offer value across several trips |
| Destination options | Can be selected for the specific destination | Usually based on selected regional or worldwide cover |
| Policy limits | Apply to the insured journey and benefits | May apply per trip, per policy year, or both |
| Renewal | New policy needed for a future trip | Renewal may be needed each year |
Exact features vary by insurer and country. Always check the policy wording rather than assuming every policy follows the same rules.
Which Option Costs Less?
There is no single price rule that applies to every traveler. The cheaper option depends on the number of trips, each trip’s length, destinations, traveler ages, medical history, activities, selected benefits, and policy limits.
To compare costs, estimate how many trips you expect to take over the next 12 months. Then request a single-trip quote for each planned journey and compare the combined price with an annual policy quote that covers the same destinations and benefits.
Example cost comparison
Imagine a traveler expects to take four short trips in one year. They could add together the prices of four single-trip policies and compare that total with an annual multi-trip quote. If the annual plan costs less and provides suitable protection, it may be better value.
Now imagine someone plans only one trip. A single-trip policy may cost less because the traveler is not paying for a full year of multi-trip cover. These are examples of the comparison method, not price predictions. Actual quotes can differ significantly.
Do not compare price alone
A policy with a low premium may have a high excess, low medical limits, narrow cancellation protection, or strict exclusions. A slightly more expensive policy may offer more suitable protection. Compare the same benefits and limits wherever possible.
Medical Emergency Cover: A Priority for International Travel
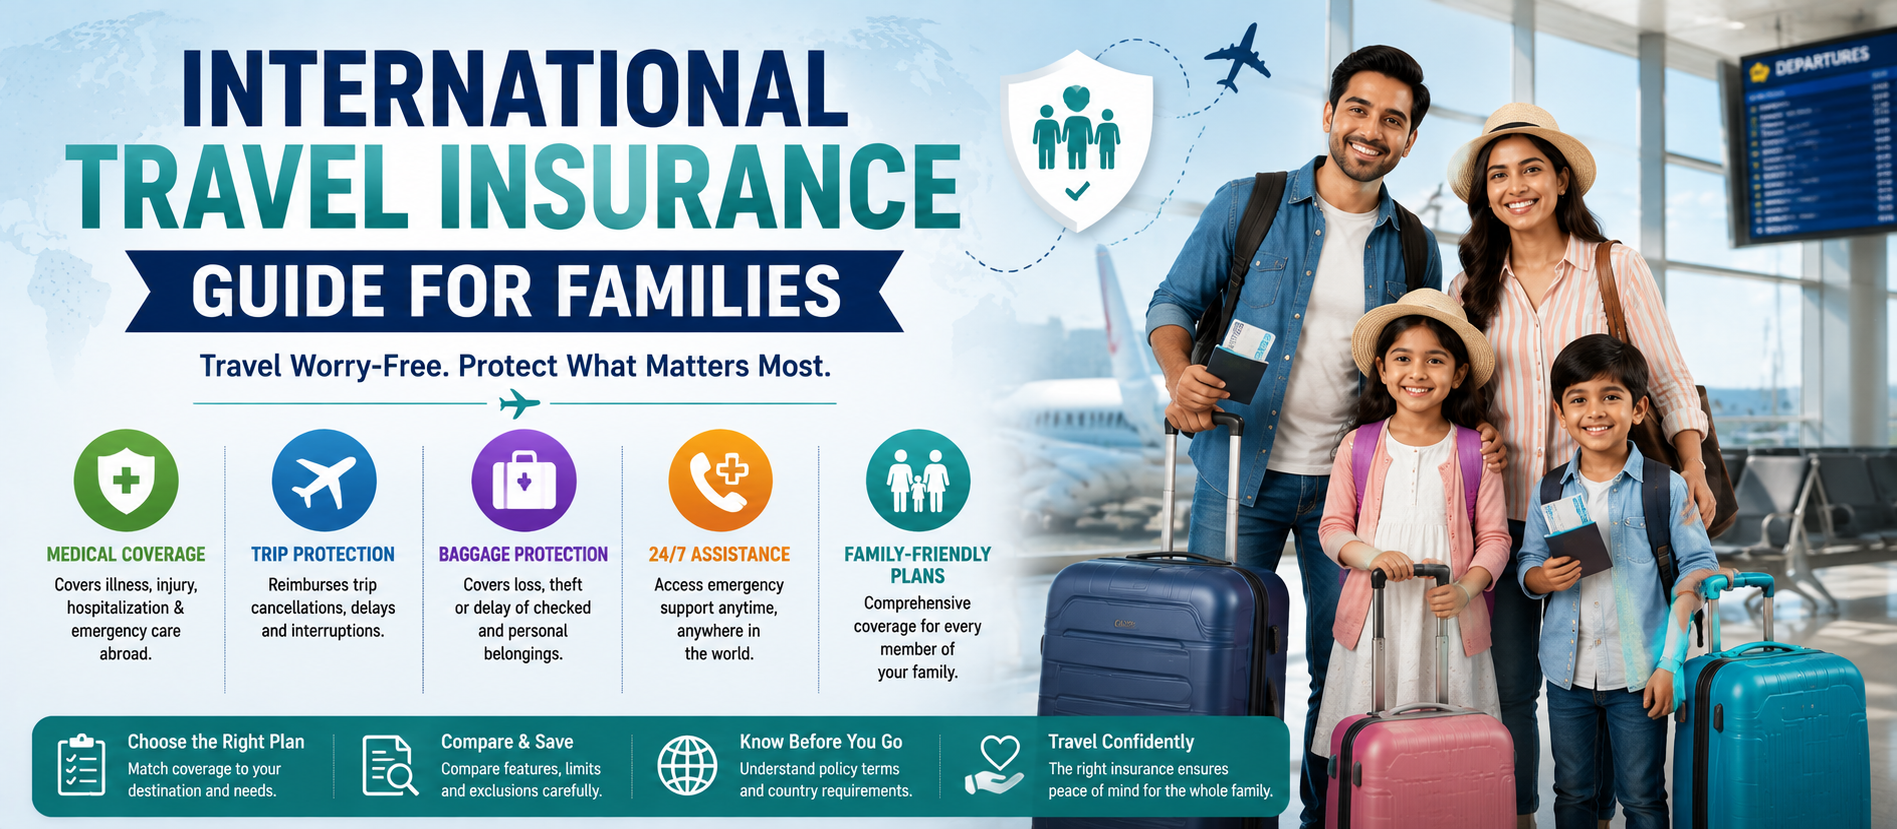
Medical expenses can be high in some destinations. Travel insurance may help with eligible emergency treatment, hospital stays, ambulance costs, or medical evacuation, subject to the policy terms. It may also provide access to a 24-hour emergency assistance service.
Review the medical limit and how emergency evacuation is handled. Ask whether the insurer must approve treatment or transport before costs are incurred, except where the policy allows otherwise in an emergency.
Declare medical conditions accurately when the insurer asks for them. Some conditions may be excluded unless accepted by the insurer or covered through an added benefit. Do not assume that a condition is covered simply because the policy includes medical expenses.
Also check whether the policy covers medical expenses related to infectious diseases, pregnancy, or planned activities if those issues are relevant to your trip. Terms vary, so read the exclusions and eligibility rules carefully.
Trip Cancellation and Interruption Benefits
Cancellation cover may reimburse certain prepaid, non-refundable travel costs when a covered reason forces you to cancel before departure. Trip interruption cover may help with eligible costs if a covered event makes you cut a journey short or disrupts your plans.
Covered reasons are defined by the policy. They may include certain unexpected illnesses, injuries, or serious events, but not every change of plan is covered. A change of mind, a known event, or a circumstance excluded by the contract may not qualify.
Check the maximum benefit, the events covered, the excess, and any requirements for documentation. Buy insurance soon after making eligible bookings if you want to understand whether time-sensitive benefits apply. Some benefits may have purchase deadlines or special conditions.
Baggage, Personal Belongings, and Travel Delays
Travel policies may cover certain losses involving checked baggage, personal belongings, travel documents, or delayed luggage. Some plans also provide benefits for long travel delays or missed connections caused by covered circumstances.
These benefits usually have limits and exclusions. Valuable electronics, cameras, jewelry, cash, and work equipment may have lower sub-limits. You may need to report a loss to the airline, police, or another relevant authority and provide supporting documents.
Read the definitions of baggage loss, theft, delay, and unattended property. Keep receipts for essential purchases made during a covered baggage delay. A benefit may require a minimum delay period and may not reimburse every purchase.
Trip Duration and Destination Rules
Trip length is one of the biggest differences between single-trip and annual policies. An annual plan may cover many journeys but limit each journey to a specific number of days. If one trip exceeds that limit, the insurer may not cover the entire journey unless an extension is available and approved.
Check whether travel days are counted from departure to return, whether a return to your home country affects eligibility, and whether the policy has rules about where a trip must begin and end. Do not assume you can leave for an extended period and remain covered simply because the annual policy has not expired.
Destination categories also matter. Some plans offer regional cover, while others provide worldwide cover with or without certain countries. Higher-risk destinations or official travel warnings may affect eligibility or claims. Confirm that every country on your itinerary is included.
Adventure Sports, Cruises, and Business Travel
Standard travel insurance may not cover every activity. Skiing, scuba diving, mountaineering, motorbike riding, or other higher-risk sports may require an optional benefit or specialist policy. Check activity limits, equipment cover, and any requirements for licensed guides or safety gear.
Cruise travel may also need specific cover. Ask about missed port departures, cabin confinement, emergency evacuation, and medical treatment at sea. These benefits are not automatically included in every plan.
Business travelers should review cover for work equipment, business-related cancellation, and the activities they will perform. Personal travel insurance may exclude certain manual work or professional risks. An employer may provide some protection, but confirm what is included and what you must arrange yourself.
Pre-Existing Medical Conditions and Other Exclusions
Exclusions can be as important as the benefits listed in a policy summary. Read the full wording for exclusions related to medical conditions, alcohol or drug use, unattended belongings, reckless behavior, travel against medical advice, and events known before cover began.
Pre-existing medical conditions are handled differently by different insurers. Some policies may cover certain conditions after disclosure and acceptance; others may exclude them or charge an additional premium. Answer medical questions truthfully. Incorrect or incomplete answers can affect a claim.
Ask the insurer to confirm in writing whether a relevant condition, activity, or destination is covered. If a standard policy does not fit your needs, compare specialist providers rather than relying on assumptions.
How to Choose the Right Policy for Your Travel Style
Choose single-trip cover if:
- You expect to take one trip during the next year.
- You are planning a long journey that may exceed an annual policy’s trip limit.
- You need cover for a specific itinerary or activity.
- You want to compare cover tailored to one destination.
Consider annual multi-trip cover if:
- You expect to take several trips in the next 12 months.
- You take regular short holidays or business journeys.
- You prefer to arrange eligible travel cover once for the policy year.
- The annual policy’s trip limits, destination rules, and benefits match your plans.
These are starting points, not strict rules. A frequent traveler may still need a single-trip policy for a long or unusual journey. A person taking two trips may find annual cover worthwhile if the price and benefits compare favorably.
How to Compare Travel Insurance Quotes Step by Step
- List your trips. Note dates, destinations, trip length, travelers, and planned activities.
- Estimate your prepaid costs. Record flights, accommodation, tours, and other eligible non-refundable bookings.
- Review medical needs. Check medical limits, emergency evacuation, and the rules for pre-existing conditions.
- Get comparable quotes. Compare single-trip quotes for each journey with annual quotes covering the same destinations and benefits.
- Check deductibles and excesses. Understand how much you may need to pay toward a claim.
- Read exclusions. Look for restrictions on activities, countries, trip duration, and cancellation reasons.
- Research the provider. Check licensing or authorization where applicable, complaint resources, assistance services, and claims instructions.
- Read the policy documents. Confirm the start date, end date, eligibility, limits, and any required disclosures before paying.
Common Travel Insurance Mistakes to Avoid
- Buying only on price: A low premium may come with low limits or narrow cover.
- Ignoring the maximum trip duration: This is especially important for annual policies.
- Assuming all medical conditions are covered: Disclosure and insurer acceptance may be required.
- Leaving insurance until the last minute: Some cancellation benefits may depend on when the policy is purchased.
- Overlooking exclusions: Activities, destinations, and known events may be excluded.
- Not checking cancellation limits: The limit may be lower than the total amount you could lose.
- Assuming every traveler is automatically covered: Check age, residency, family, and traveler eligibility rules.
- Failing to keep evidence: Booking confirmations, receipts, medical records, and incident reports can support a claim.
Travel Insurance Considerations by Country
Travel insurance products and consumer rules vary by country. Your place of residence, where the policy is issued, and the destination can affect which policies are available and how claims work.
If you live in India, check the insurer’s current policy wording, eligibility rules, exclusions, and claims process. You can consult the Insurance Regulatory and Development Authority of India (IRDAI) for official insurance information and consumer guidance. If you live elsewhere, consult the relevant local insurance regulator. Do not assume that a policy sold in one country is available or suitable in another.
For international trips, also review the destination’s entry requirements and official travel advice. Travel insurance does not replace a visa, required health documentation, or sensible travel planning.
Frequently Asked Questions
Is annual travel insurance better than single-trip insurance?
Annual travel insurance can be better for people taking several eligible trips within a year. Single-trip cover may suit occasional travelers or longer journeys. Compare total cost, benefits, exclusions, and maximum trip duration before deciding.
How many trips make annual travel insurance worthwhile?
There is no fixed number. It depends on the cost of separate policies, the annual premium, destinations, ages, and cover selected. Add up the quotes for your expected trips and compare that total with an annual quote.
Does annual travel insurance cover long holidays?
It may not cover a long holiday in full. Annual multi-trip policies often set a maximum number of days for each trip. Check the policy limit and ask whether an extension is available before traveling.
Can I buy single-trip insurance for an international holiday?
Yes, if the insurer offers a policy for your country of residence and destination and you meet its eligibility rules. Choose dates and benefits that match the journey, and disclose relevant information accurately.
Does travel insurance cover pre-existing medical conditions?
It depends on the insurer and policy. Some conditions may be covered after disclosure and acceptance, while others may be excluded or require additional payment. Read the terms and obtain confirmation before buying.
Will travel insurance cover a canceled trip for any reason?
No. Standard cancellation cover usually applies only to specified covered reasons. A policy may offer an optional cancel-for-any-reason benefit in some markets, but it can have strict conditions, deadlines, and reimbursement limits.
Does annual travel insurance cover every destination?
No. Coverage depends on the region or worldwide option selected, policy exclusions, and travel advisories or restrictions. Check every country on your itinerary with the insurer.
Can I use annual travel insurance for business trips?
Some annual policies cover business travel, but not all do. Check whether work activities, equipment, and the purpose of travel are included. Specialist cover may be needed for certain jobs or risks.
What should I do if I need to make a claim?
Contact the insurer or emergency assistance service as soon as practical and follow its instructions. Keep booking documents, receipts, medical records, and incident reports. For urgent medical emergencies, seek appropriate care first and contact the insurer when it is safe to do so.
Can I buy both single-trip and annual travel insurance?
In some situations, a traveler may have an annual policy and a separate policy for a longer or specialist trip. Check for overlapping benefits, exclusions, and coordination rules. Do not assume two policies will pay twice for the same loss.
Final Verdict: Which Travel Insurance Should You Choose?
Single-trip and annual travel insurance serve different needs. Single-trip cover is often a practical choice for one journey, a long stay, or a trip that needs tailored benefits. Annual multi-trip cover can be convenient for frequent travelers and may offer better value when several trips are planned.
Before deciding, compare the full cost of the policies you need, medical and cancellation limits, trip-duration rules, deductibles, exclusions, and the insurer’s assistance service. Read the policy documents and make sure the cover fits your actual itinerary. A suitable policy is one you understand and can rely on under its stated terms.
Explore more practical guides at Digiifrog — www.digiifrog.com.
Disclaimer: This article is for general educational purposes only. It is not insurance, legal, or financial advice. Policy terms, benefits, and eligibility rules vary by provider and location. Read the full contract and consult a licensed insurance professional or relevant regulator if you need advice for your circumstances.
Ready to Grow?
Talk to us about a strategy tailored to your brand — we will help you stand out in search, AI discovery and social.
Comments (0)
Log in to leave a comment.